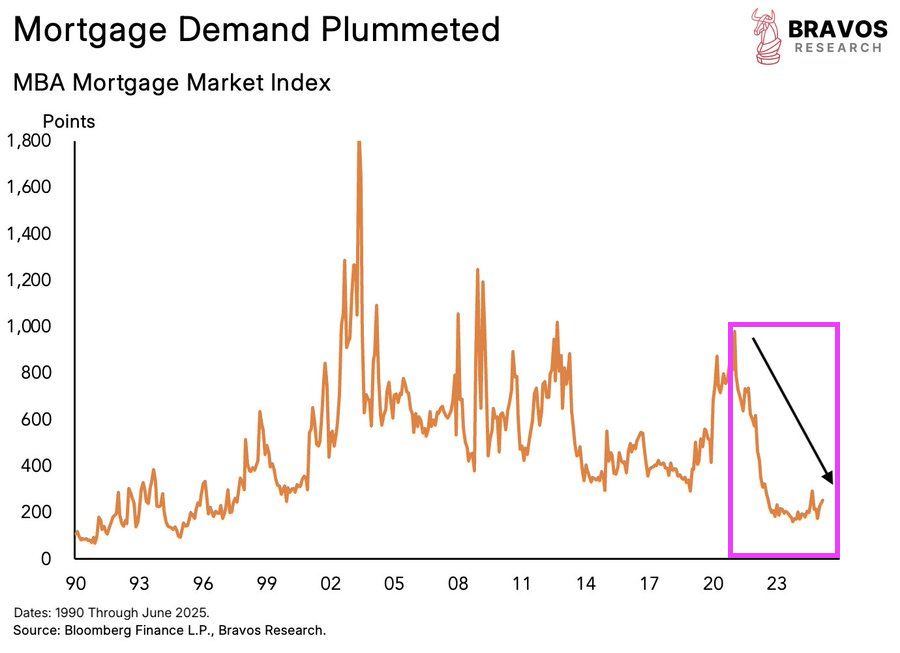
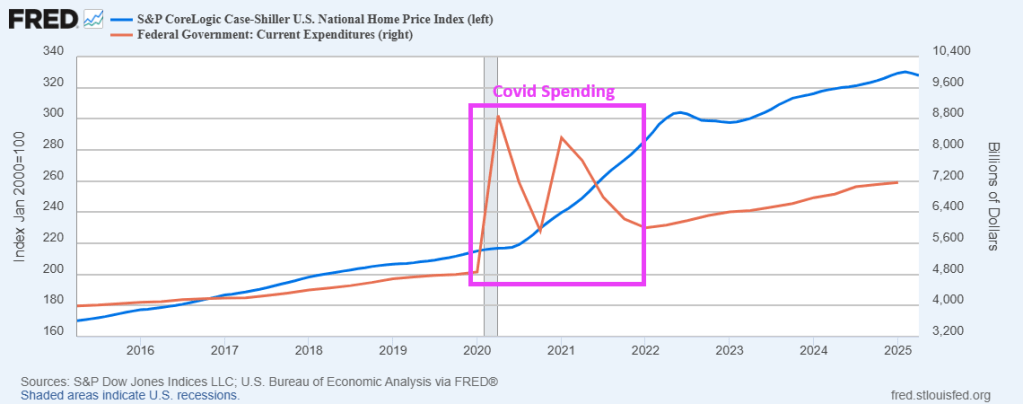
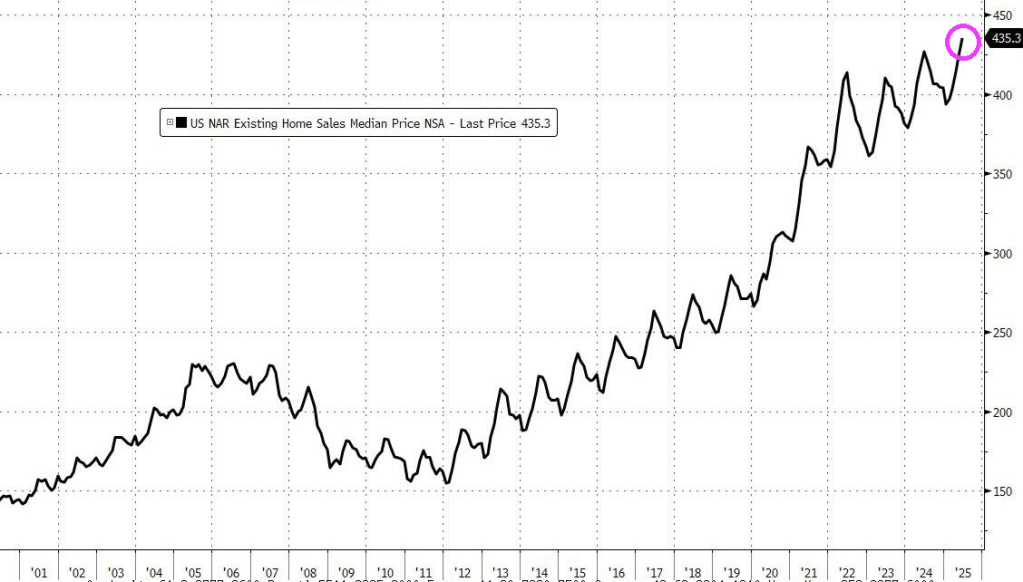
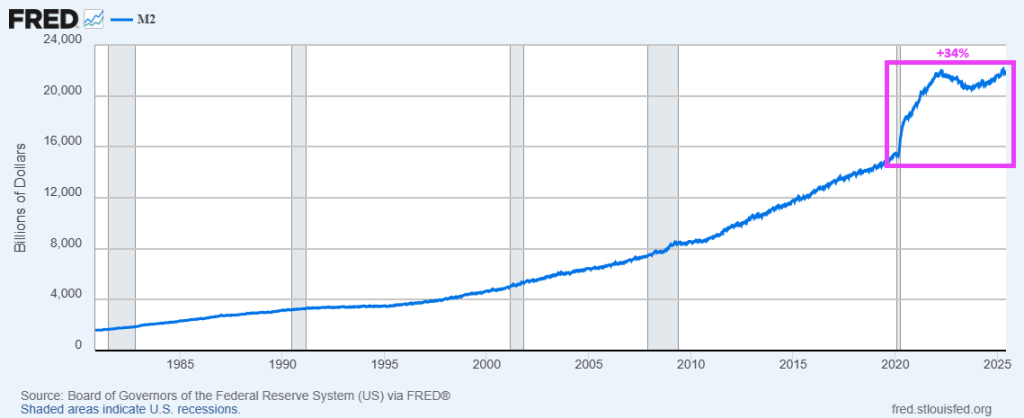
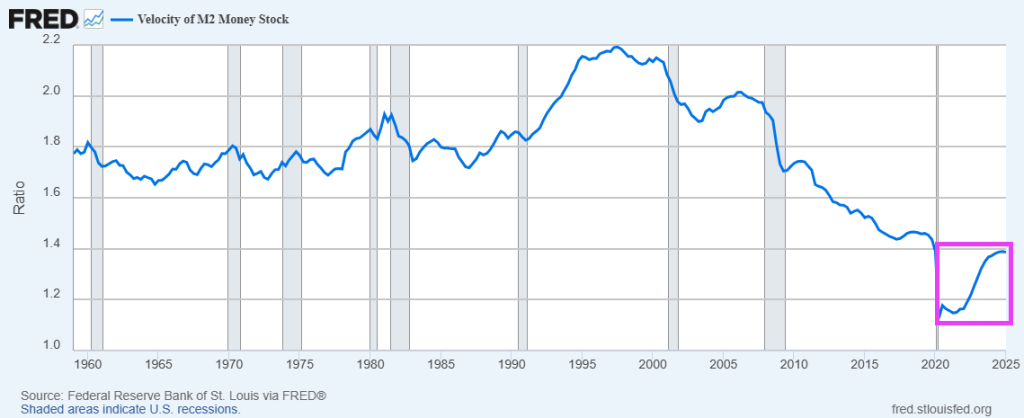
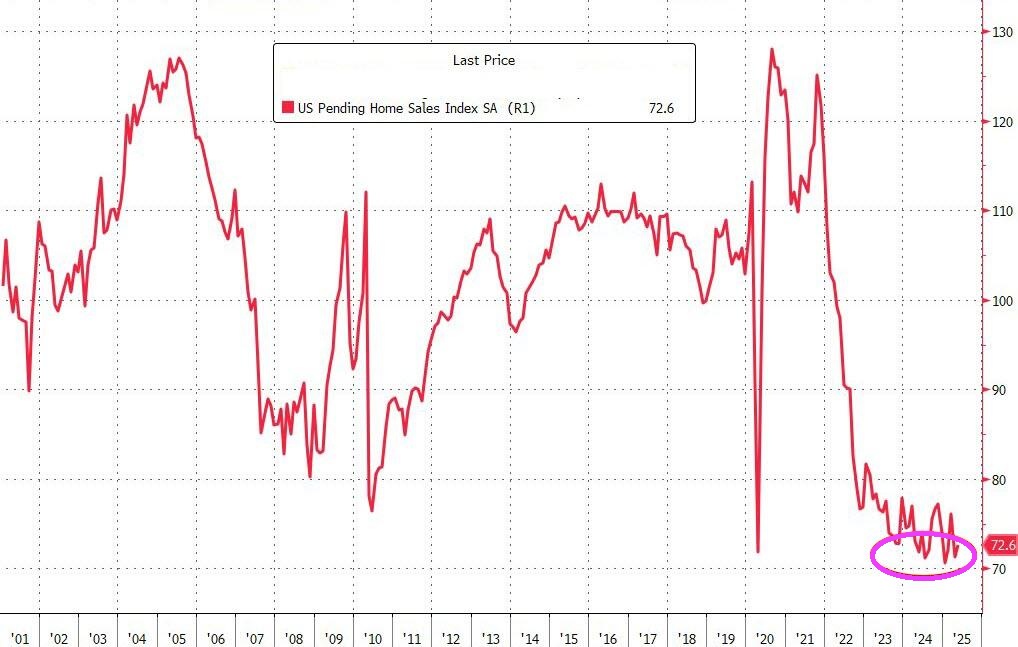
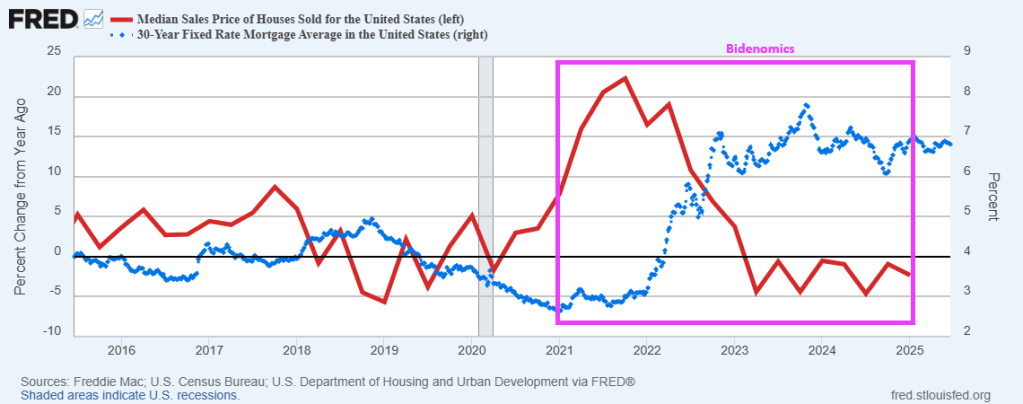
China unleashed the Wuhan virus on the globe, Anthony Fauci convinced Congress to binge spend like drunken sailors on Covid prevention and relief. Homes prices soared, mortgage demand sank and nothing has been the same.
Here is a chart of the Case-Shiller national home price index post Covid outbreak and the hysterical overreaction by Congress and the Administration (including Anthony Fauci).
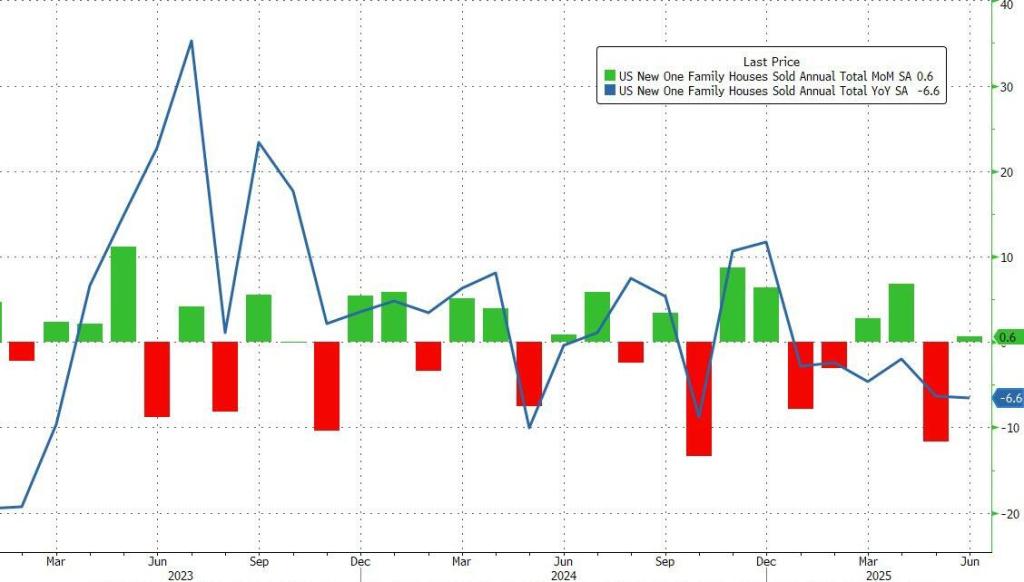
Another example? New home sales are down 6.6% YoY.
Who do we blame? China? Yes. Anthony Fauci? Yes. Congress? Yes.
Thank goodness “Statist Joe” Biden is gone. Kamala Harris is still lingering around the edges, while the mortgage and housing markets are still suffering from the Biden/Harris regulatory overreach.
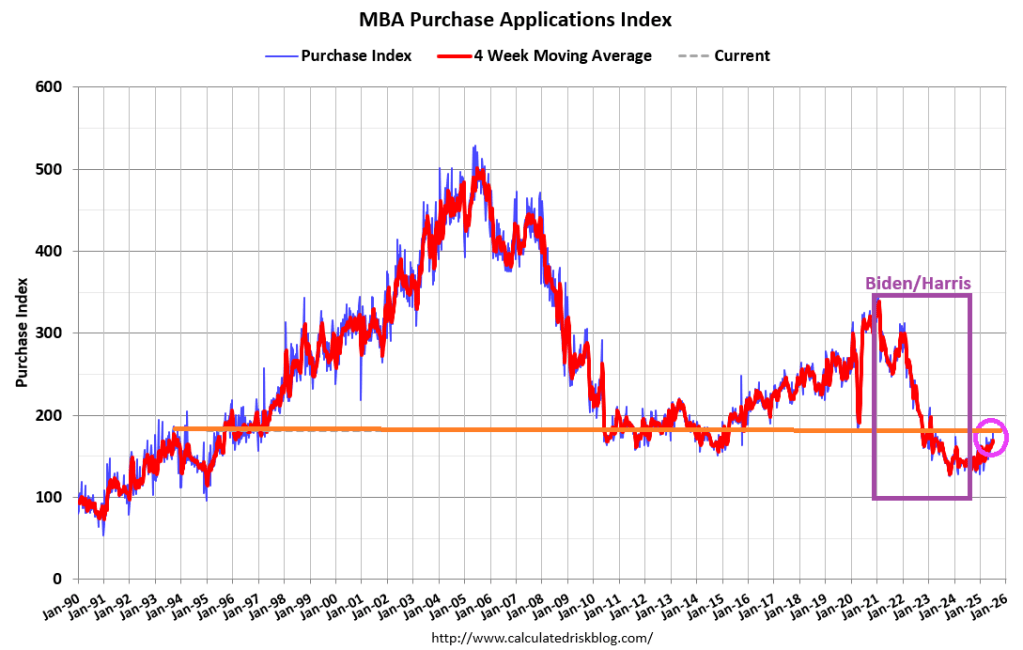
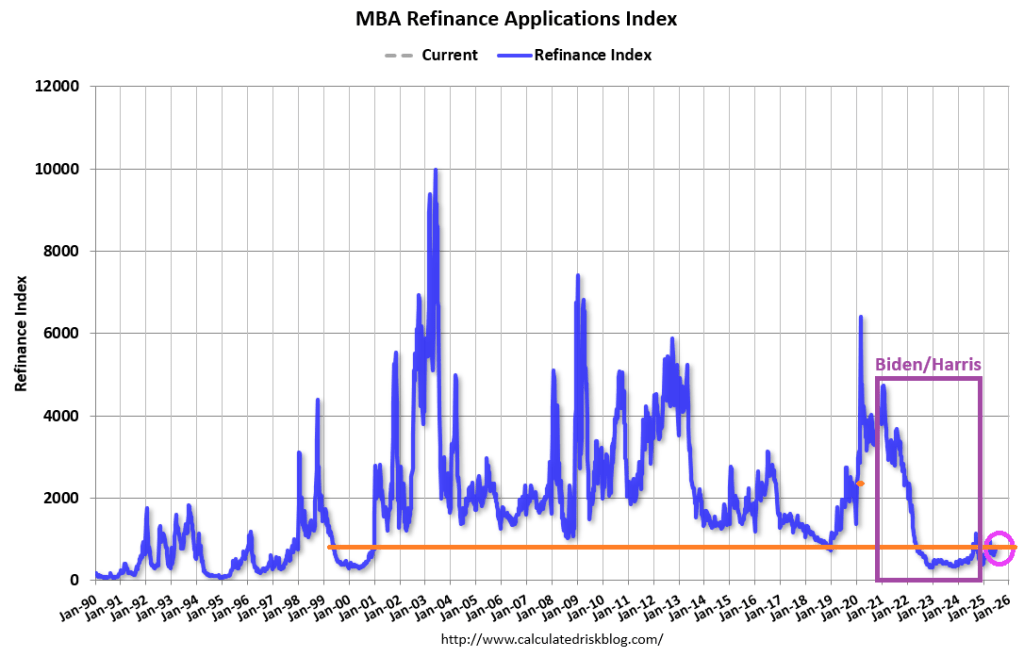
Mortgage applications increased 9.4 percent from one week earlier, according to data from the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey for the week ending July 4, 2025. Last week’s results included an adjustment for the July 4th holiday.
The Market Composite Index, a measure of mortgage loan application volume, increased 9.4 percent on a seasonally adjusted basis from one week earlier. On an unadjusted basis, the Index decreased 13 percent compared with the previous week. The seasonally adjusted Purchase Index increased 9 percent from one week earlier. The unadjusted Purchase Index decreased 13 percent compared with the previous week and was 25 percent higher than the same week one year ago.
The Refinance Index increased 9 percent from the previous week and was 56 percent higher than the same week one year ago.
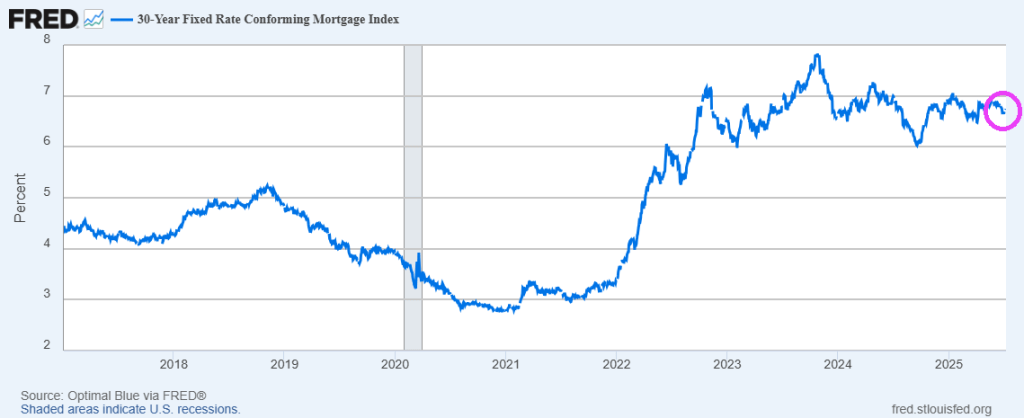
Mortgage rates moved lower last week, with the 30-year fixed rate decreasing to 6.77 percent, its lowest level in three months. After adjusting for the July 4th holiday, purchase applications increased to the highest level of activity since February 2023 and remained above year-ago levels.
Biden claims the foreign leaders have been calling him for advice. Here is one example.
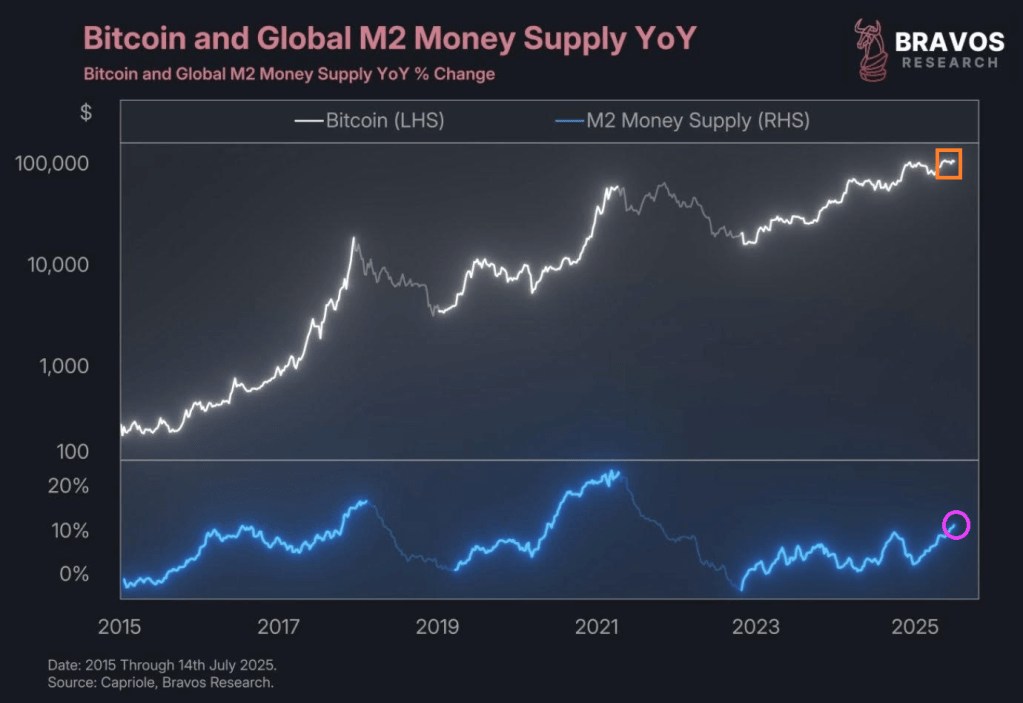
Finally, US government debt growth (YoY) was approximately equal to US nominal GDP growth in Q1 2025.
Unfortunately, the BBB (Big Beautiful Bill) is projected to add $3.9 trillion of debt. Unfortunately, there are insufficient spending cuts in the BBB. And the Senate just nixed kicking illegal immigrants off of Federal healthcare programs.
Unfortunately, GDP growth is only expected to be modest with debt growth once again rising faster than GDP growth. As Diane Feinstein once said, politicians are elected to spend money. This, of course, was a ridiculous statement embraced by spend-crazy Democrats and RINOs.
So, Congress has committed American taxpayers to debt slavery.
I sure hope this isn’t a repeat of the financial crisis! But new homes for sale have ballooned to financial crisis levels.
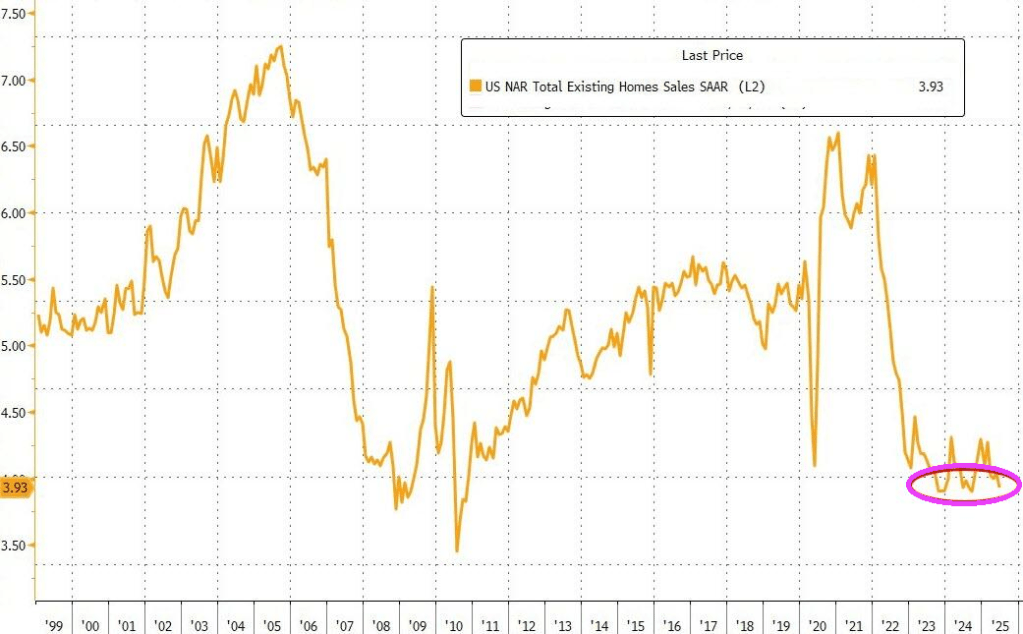
Home sales have dropped below year-ago levels, presaging likely declines in mortgage supply and turnover. With completed-home inventories hitting post-global financial crisis (GFC) highs, regional surpluses are emerging as key home-price factors, setting the stage for widening pockets of price weakness in the months ahead.
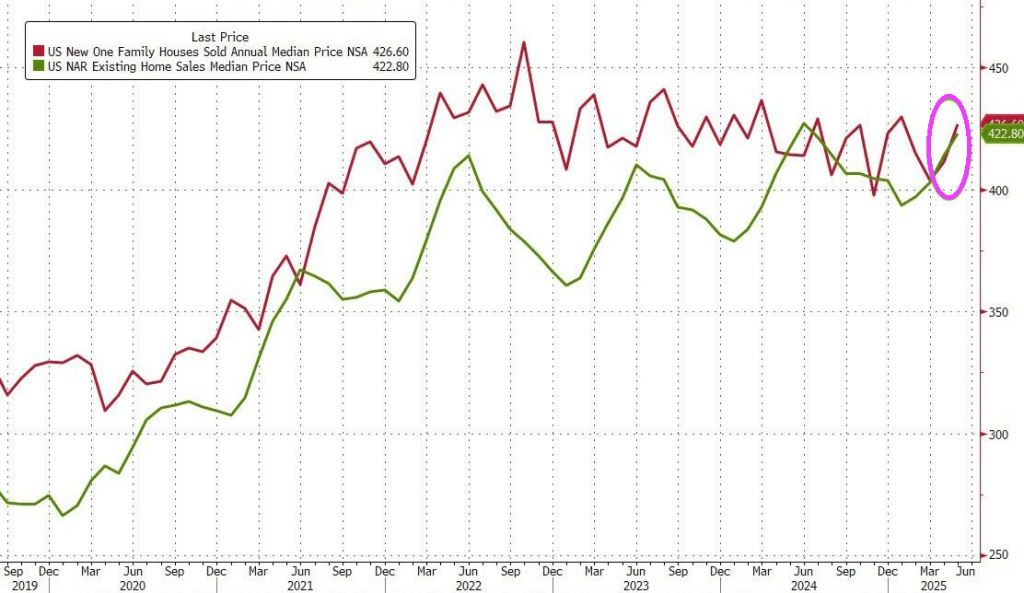
Contributing to the glut of new homes for sale is the rising prices AND higher mortgage rates.







 Confounded Interest - Anthony B. Sanders

You must be logged in to post a comment.