Inflation under President Biden (aka, Bidenflation) has hit 7.9%, the highest in 40 years. And no Joe, the inflation surge was well underway before Russia invaded Ukraine on February 24, 2022.
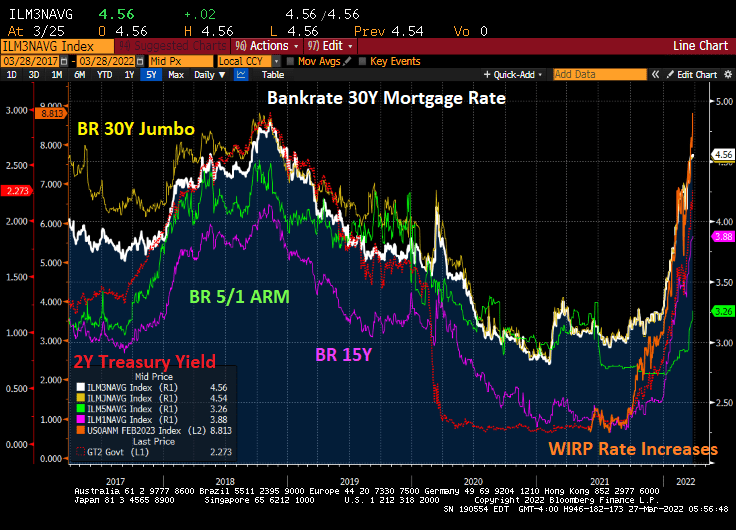
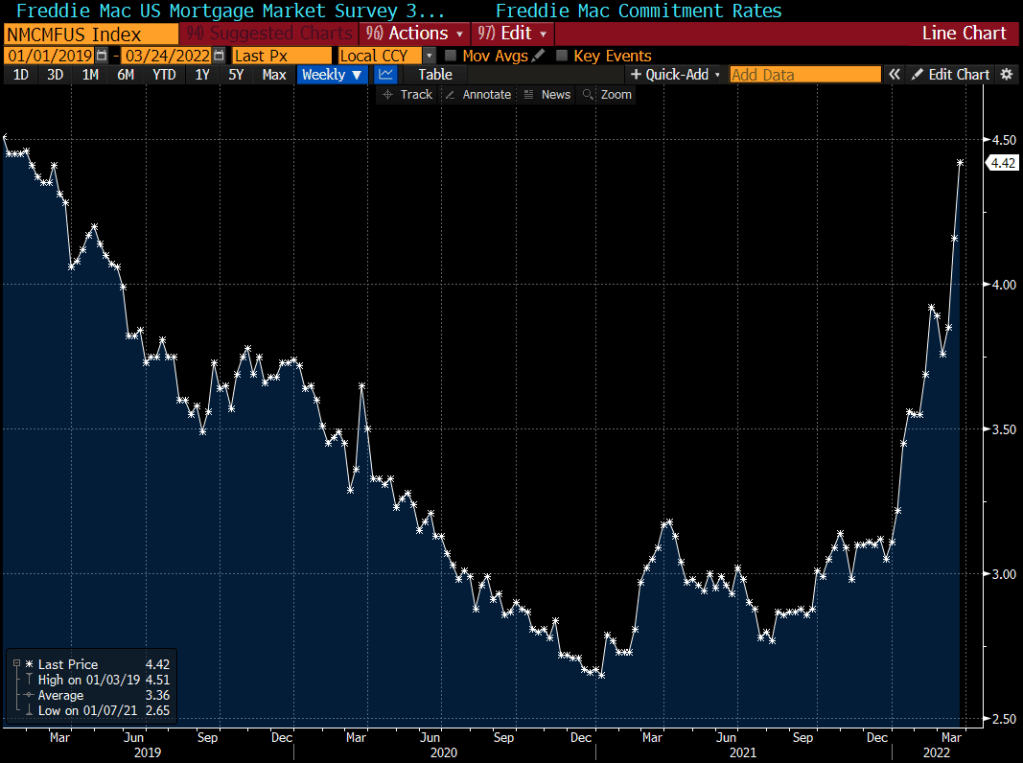
As The Federal Reserve is allegedly going to try to fight inflation by raising their target rate, the 30-year mortgage rate has risen from 2.88% on Biden’s inauguration to 4.56% today.
The surge in mortgage rates from 2.88% to 4.56% represents a 58.3% increase in mortgage rates under Biden. That translates to an increase in the 30-year fixed-rate mortgage (FRM) payment of 23%. Apparently Biden-Powell (not to be confused with Baden-Powell, the founder of the Boy Scouts) are not interested in keeping homes affordable for most Americans.
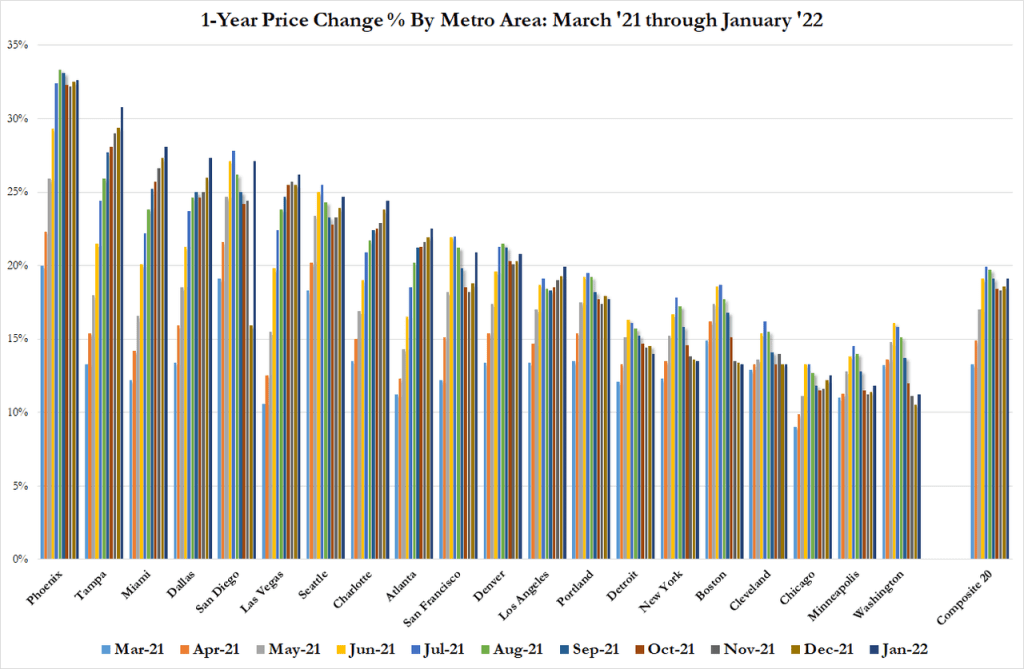
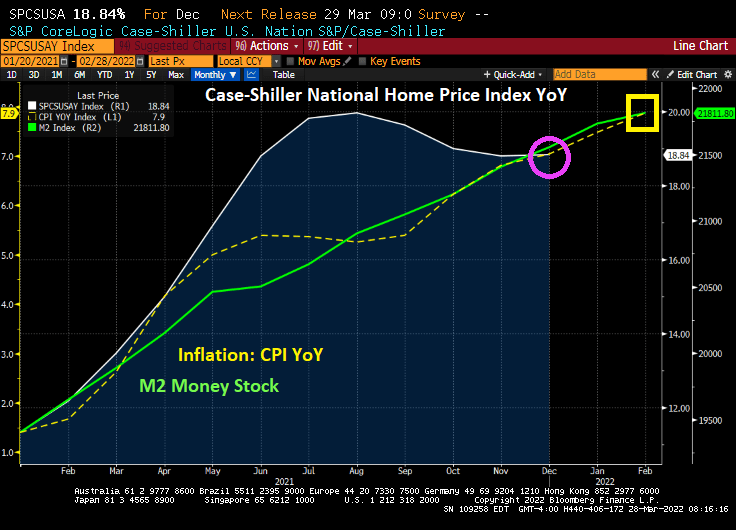
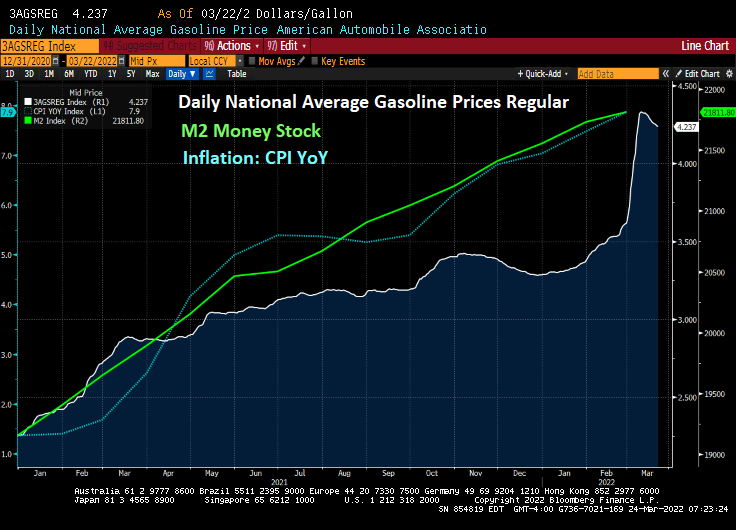
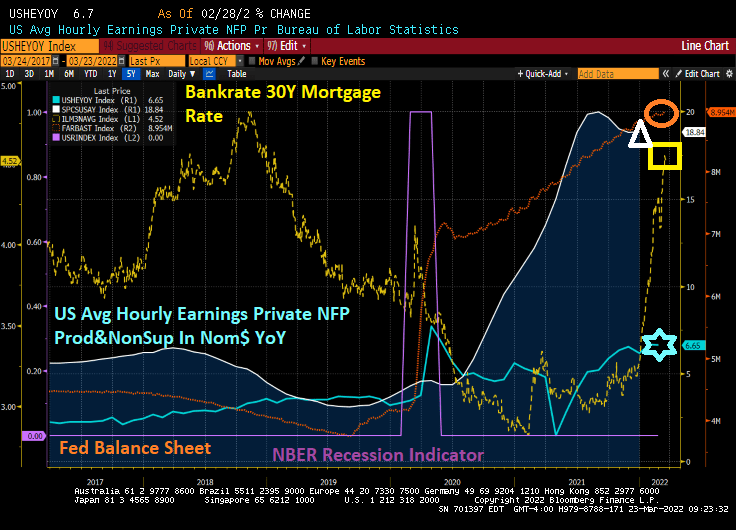
I summarize the predicament facing Americans in the following chart. Home prices were growing at a 19% YoY pace in December (Case-Shiller updates will be available tomorrow for January). Inflation is growing at 7.9% and M2 Money continues to grow.
US fertilizer prices are up 166% under Biden while regular gasoline prices are up 77% under Biden. But to be fair, fertilizer and gasoline prices jumped with Russia’s invasion of Ukraine. Fertilizer prices were up 66% under Biden BEFORE Russia invaded Ukraine and regular gasoline prices were up 50%.
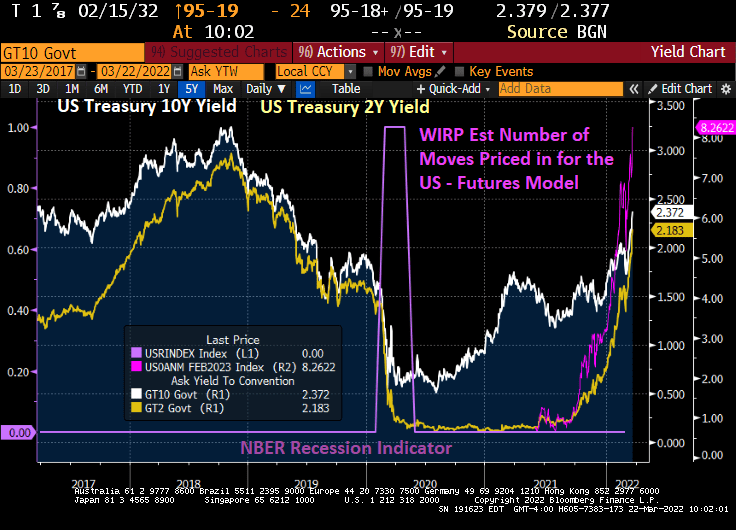
Meanwhile, back at the fixed-income ranch, the US Treasury 10Y-2Y curve has flattened to 14.5 BPS as Fed Funds Futures signal 9 rate hikes over the coming year.
And the US Treasury 10Y-5Y curve continues to invert.
In short, Biden and Congress are anti-fossil fuel, pro-renewable energy helping to drive up energy prices and inflation PRIOR to Russia invading Ukraine. Powell and The Federal Reserve are trying to fight what Biden and Congress did with creating energy-related inflation.
The reason why the fear of ARMs is unwarranted is that ARMs generally have CAPS on rate increases, either in a given period or over the life of the loan. Of course, READ the loan terms to ensure that the ARMs has restrictive caps on rate increases.
Currently, the 5/1 ARM is at 3.26% while the 30-year FRM is at 4.56%, a spread of 130 basis points.
Mortgage rates of all flavors are rising rapidly with the expectation of Federal Reserve Quantitative Tightening (QT). There are several headwinds that could counter The Fed’s QT efforts such as low GDP growth (Atlanta Fed’s GDPNow real-time GDP tracker is at 0.9% for Q1), the Russia-Ukraine invasion, approaching midterm elections, etc. But as of today, The Fed seems on a collision course with rising mortgage rates.
With the increasing likelihood of Fed rate hikes over the next year, we are seeing an increase in US ARM loan share from 4% to 7.9%, almost a doubling of ARM share. But FRMs are still over 90% of all mortgage originations.
Lending institutions would prefer consumers to use ARMs rather than FRMs since ARMs allow for the transfer on long-term interest rate risk to the borrower, while the FRM sticks the lender with long-term interest rate risk. Hence, we have Fannie Mae and Freddie Mac, the Government Sponsored Enterprises (GSEs) that allow lenders to originate FRMs and sell them to F&F. We are the only country with twin GSEs.
So, while most consumers would be better-off with an adjustable-rate mortgage, the structure of the mortgage market (particularly after the financial crisis) encourages lenders to originate FRMs and sell them to Fannie Mae and Freddie Mac.
But FEAR drives many US mortgage borrowers into the FRM space rather than getting an ARM with a lower interest rate, even if ARM caps would prevent the mortgage rate from rising more than 100 basis points over the life of the loan.
Unfortunately, the US Breakeven 10Y inflation rate hit another all-time high as West Texas Intermediate Crude Oil (Cushing Spot) soars.
But note that the WTI Crude spot rate is still lower than it previous peak in June 2008. What is notable in the above chart is that M2 Money growth YoY has slowed after Covid “Stimulypto”. But M2 is still growing at an 11% YoY clip, much faster growth than pre-Covid rates. So, Federal stimulypto is still in place, helping to drive inflation to the moon.
As The Biden Administration and Congress pushes Green Energy and demonizes fossil fuels, we are seeing Green Energy commodities such as Lithium (for batteries) soar even faster than oil prices.
And just an update on The US Dollar, Crypto Currencies and Gold. This is just a sample of alternatives to the US Dollar for transactions. Freedom of choice is a great thing!
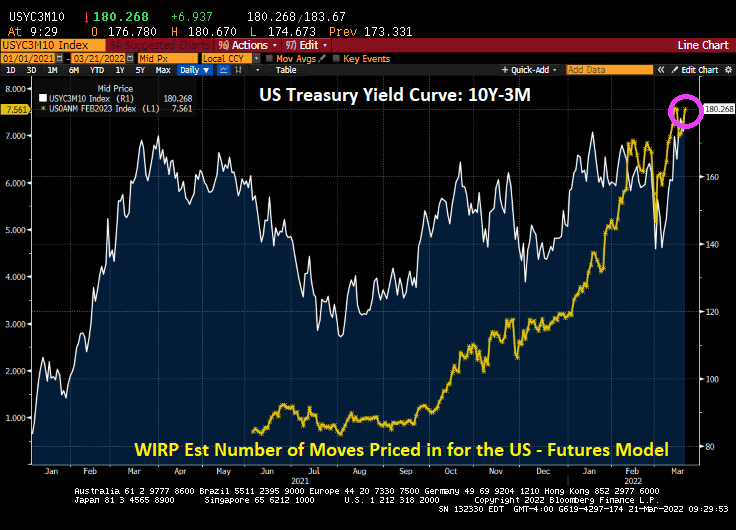
According to Fed Funds Futures data, The Federal Reserve is now forecasting 9 rate increases over the next year.
Fed Funds Futures are pointing to 8.924 rate hikes by the Fed FOMC meeting on February 1, 2023.
The US Treasury 10Y-2Y curve flattened by 5.5 bps today with the entire curve downshifting.
The Federal Reserve reminds me of The Office episode “Malone’s Cones.” They can’t really explain why they kept rates so low for so long (policy error) and seem to risk collapsing the market with rapid rate hikes without much sensible explanation.
The U.S. breakeven 10 year (USGGBE10 Index) went above 3% for the first time EVER.
Breakeven inflation is the difference between the nominal yield on a fixed-rate investment and the real yield (fixed spread) on an inflation-linked investment of similar maturity and credit quality.
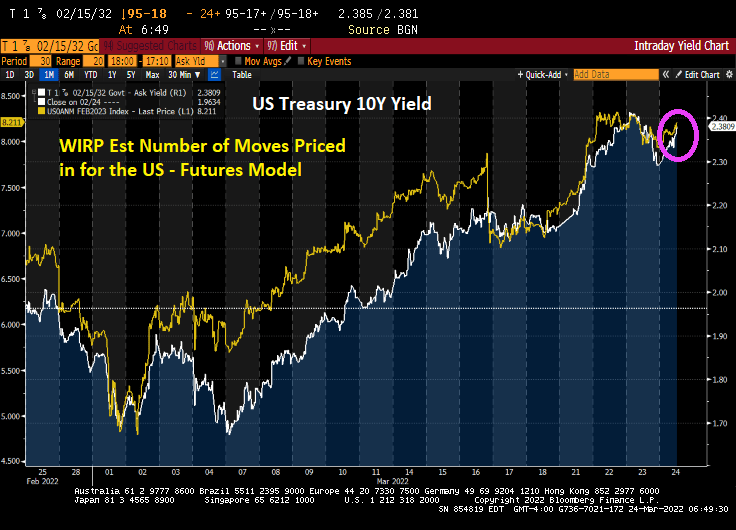
Overnight, the US Treasury yield rose to 2.38% as the number of forecast Fed rate hikes rose to 8.211. So, enjoy “low” rates while you can.
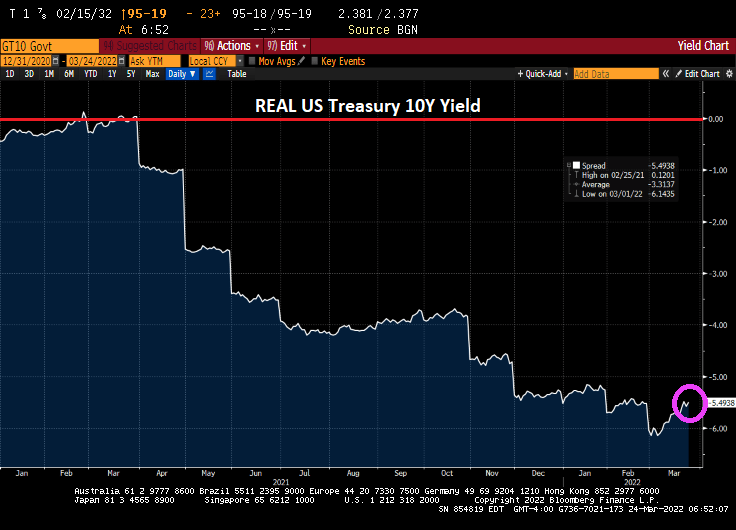
If we back out the highest inflation rate in 40 years, the REAL 10Y Treasury yield is -5.50%.
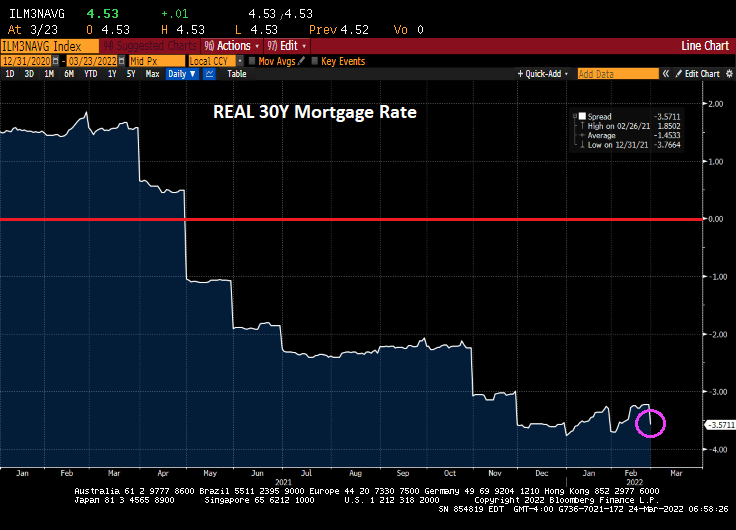
And the REAL 30Y mortgage rate is -3.57%.
Of course, the meteoric rise in inflation is due largely to Biden’s attack on the fossil fuel industry (until Russia’s invasion of Ukraine distracted from Biden’s inflation fiasco). Remember, Russia didn’t invade Ukraine until February 2022.
Wait. I thought the purpose of Biden’s executive orders was to reduce dependence on fossil fuels by driving up gasoline and natural gas prices producing a shift to “green energy.” Won’t these “gas rebates” simply continue the consumption of gasoline and natural gas? And increase inflation??
As Winston Churchill once said, “Never let a crisis go to waste.”
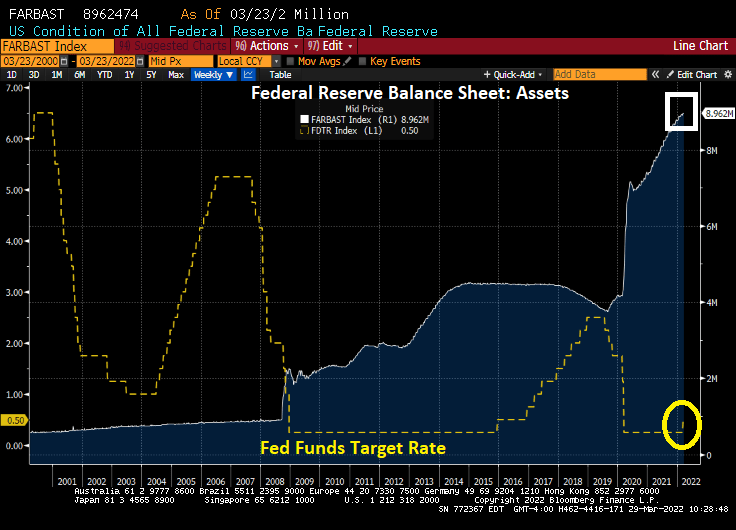
US mortgage rates are soaring, US home prices are soaring, The Fed’s balance sheet is still growing, and US average hourly earnings are growing at a fraction of home price growth.
The unafforable nature of US housing prices is similar to that of 2005-2007 when home price growth greatly exceeded wage growth.
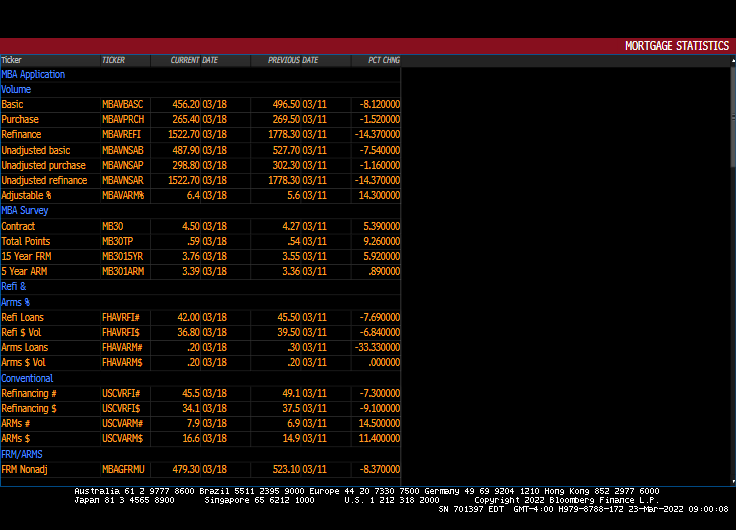
Another side effect of soaring mortgage rates: MBA refinancing applications plunged 14.37% from the preceding week.
Oil prices are soaring as US President Biden pleads like a homeless person to foreign countries for oil rather than let the US produce more oil to drive down prices. Meanwhile, the US Treasury yield curve 10Y-3M is at its steepest (rising 10Y yields while The Fed keeps short rates at near zero).
But if we look at the belly of the beast, so to speak, the 10Y-5Y slope, we can see that the Treasury curve has declined to a mere 0.278 basis points as inflation rages.
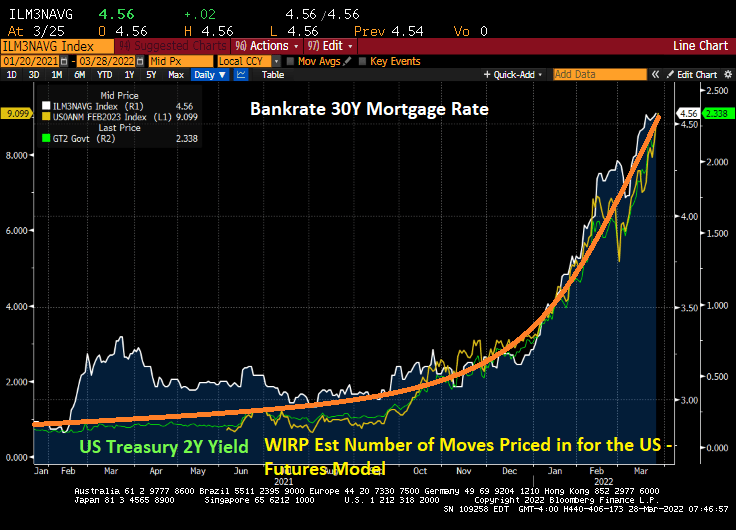
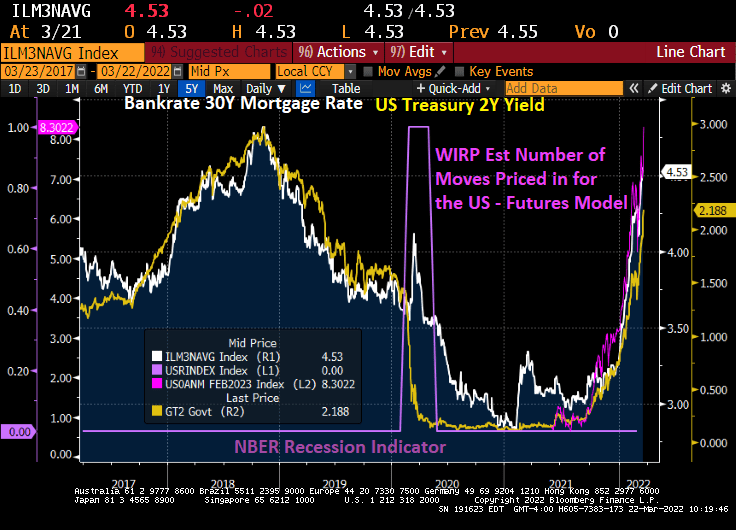
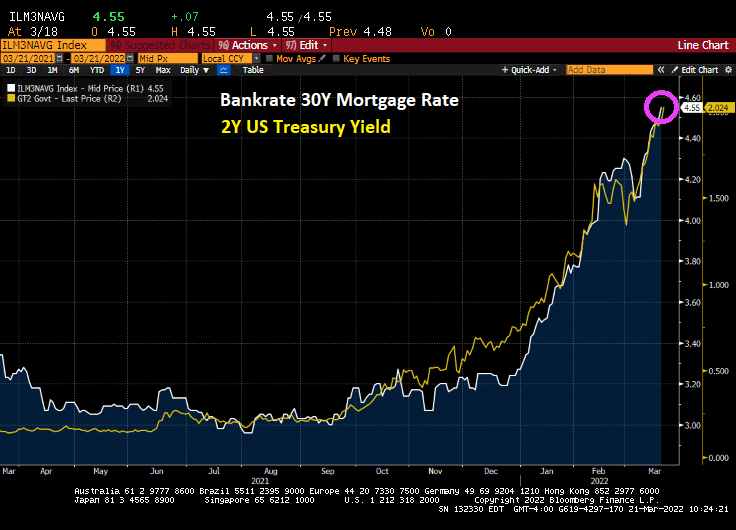
Bankrate’s 30-year mortgage rate keeps on climbing and has hit 4.55% as the 2-year Treasury yield rises rapidly.
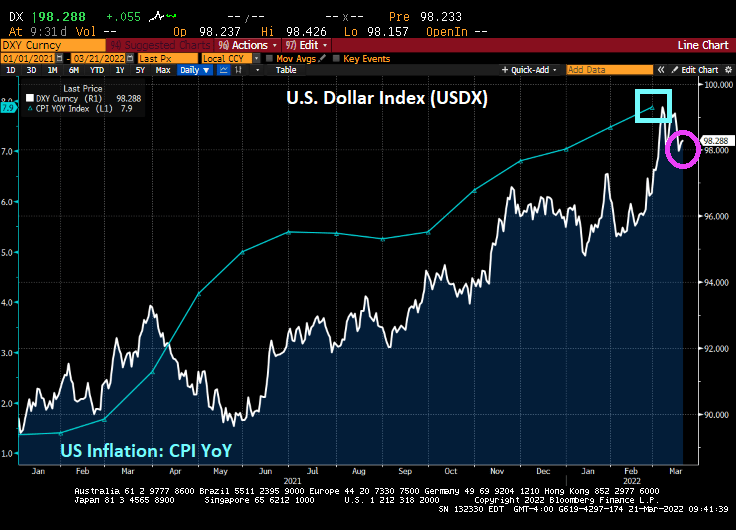
The US Dollar Index has risen dramatically as US inflation has increased dramatically.
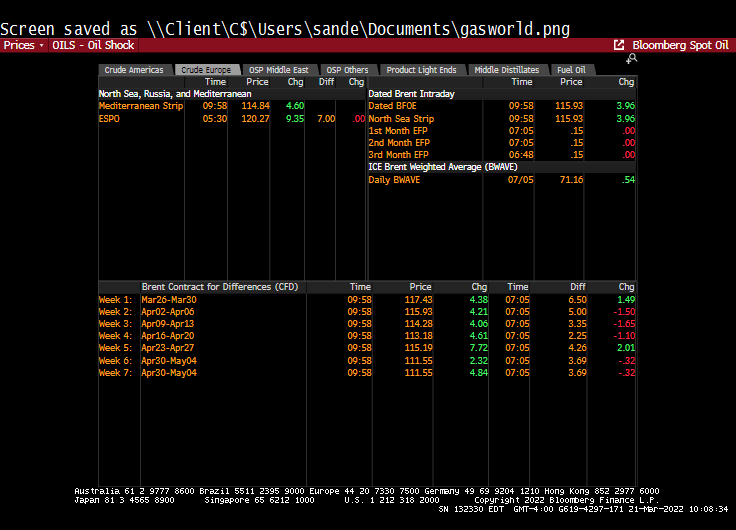
Oil? Oil is up over 4% in the US. Mexican Mix (not a #3 meal at Chuy’s) is up 7.32%.
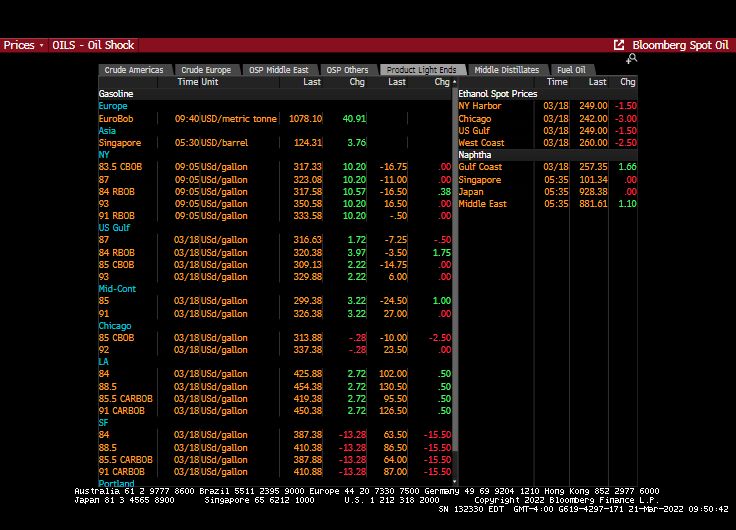
Gasoline? NY prices are up over 10%.
Russian oil is up 9.35%.
Ah, for the good old days of 30 cents a gallon gasoline, although I always wondered about Gulf’s marketing campaign. “Good Gulf” seems to imply that the other Gulf gasolines aren’t good. And Gulf’s “No-nox” seems to imply that the other Gulf gasolines knock like Biden’s knees as he pleads for foreign oil.














You must be logged in to post a comment.