The NEW Banking Crisis In One Chart (Hint: Inflation = Fed Rate Hikes = Treasury/MBS Duration Increases = Bond Losses = Bank Runs) Bond Volatility Highest Since 2008

So, the Biden Administration made a horrible error by guaranteeing deposits at Silicon Valley Bank for deposits over $250,000. Essentially, Biden bailed out big tech that kept their deposits at SVB.

But what triggered the run on SVB and other banks? Simple. Biden and Congress spent like drunken sailors with Covid and The Federal Reserve went nuts printing money. Viola! We got inflation. But with inflation came The Fed’s attempt to get inflation back to its 2% target (difficult since Biden/Congress refuse to return spending to pre-Covid levels). But as interest rates rise, duration (weighted average life of MBS) rose dramatically meaning that risk increased. But banks like SVP ignored the risk, or didn’t hedge, or were spending time worrying about non-bank related issues.

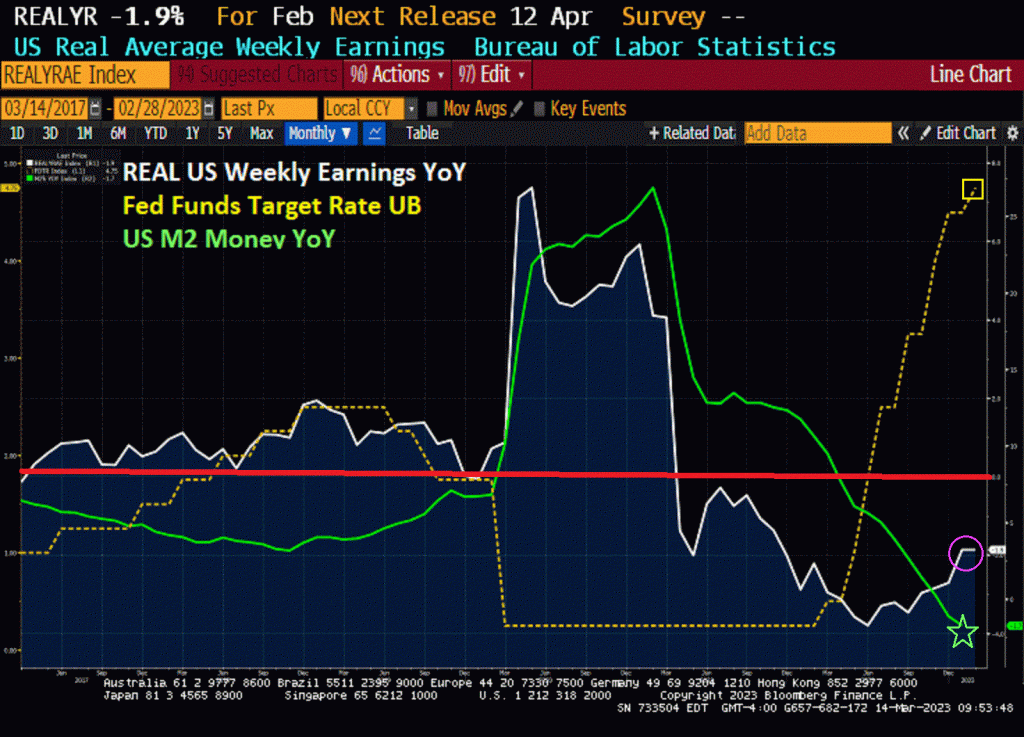
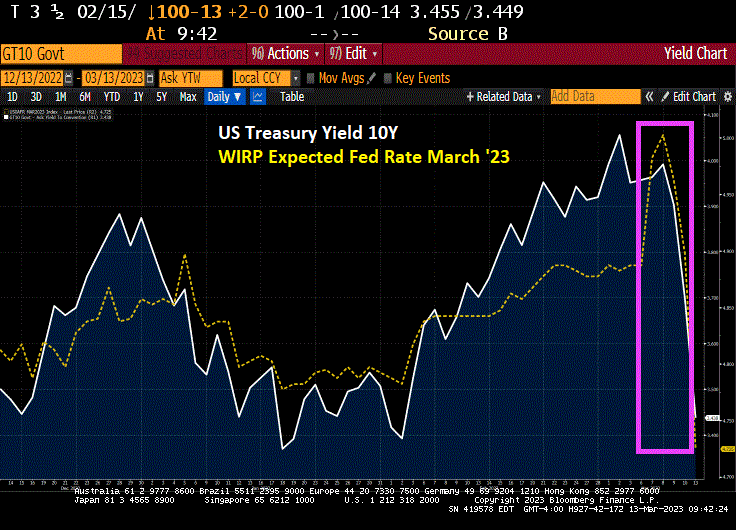
So, what happened? Banks are holding Treasuries and MBS (orange line) that are getting clobbered with rate hikes (yellow line).

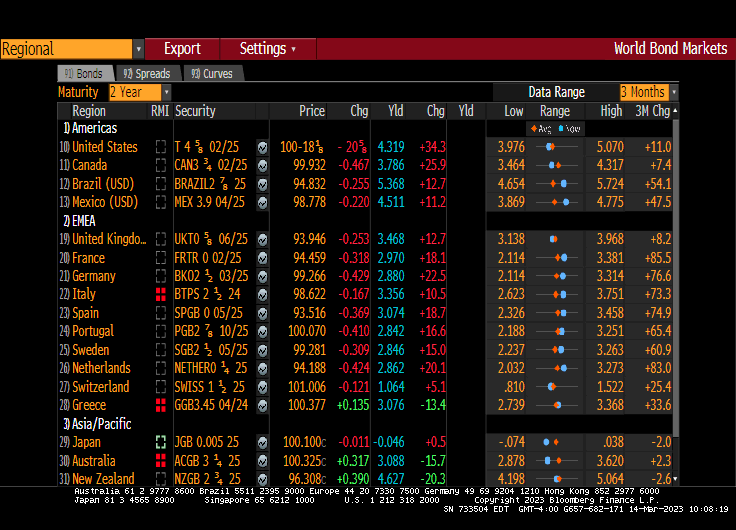
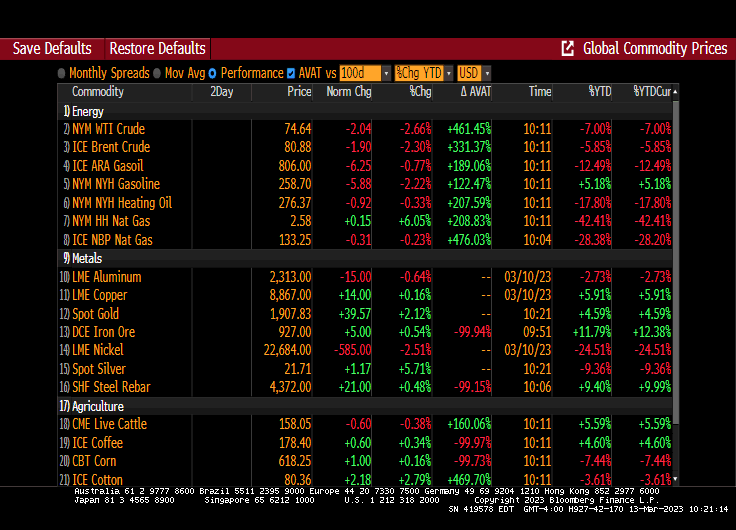
Talk about volatility. Today, the 2-year Treasury yield is up over 20 basis points as bond volatility hits levels last seen in 2008, just prior to the subprime credit crisis.

So, Biden’s bailout of SVP depositors stopped the deposit run for the moment. But if The Fed keeps hiking rates, banks are going to be hurting worse and worse. They could rebalance their portfolios and/or hedge. But with Uncle Spam (Biden) at the helm, bailouts are always on the table.

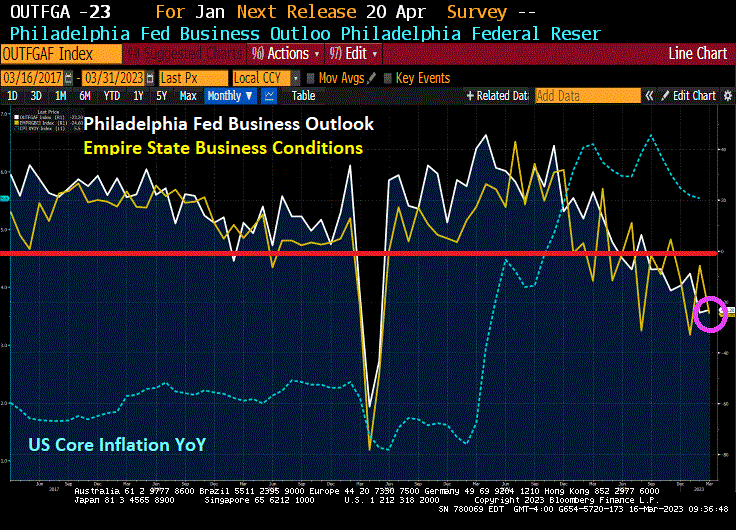
Not Always Sunny! Philadelphia Business Outlook Declines To -23 After Yesterday’s Dismal Empire State Print (Biden’s Magic Trick!)

It’s not always sunny in Philadelphia.

The Philadelphia Business outlook remains grim at -23. This comes after yesterday’s terrible Empire State print.

Between Biden’s energy policies and massive spending by Biden/Congress, we are seeing the raging effects of inflation on the economy.

Here is Biden’s Press Secretary trying to explain how marvelous the US economy is.

Snookered! US Housing Starts Rise 9.77% In Feburary, Mostly Multifamily At 24%, 1-Unit Starts Only 1.1% (23 Months Of Negative Wage Growth And Still High Home Prices Killing 1-Unit Starts)

Now that The Fed-induced-banking crisis has cooled … for the moment … I can focus on that mysterious positive homebuilder sentiment release from yesterday.

The sentiment was driven by 5+ unit (multifamily) starts which were up 24% in February, which 1-unit (single-family detached) starts were up only 1.10%. 23 consecutive months of NEGATIVE real wage growth and still ultra-high home prices begat lots of multifamily housing starts.

The problem for Americans is the real weekly wage growth has been negative for 23 consecutive weeks while home prices remain high, particularly after the Covid bailout by The Fed.

Here is the rest of the story.

So, 1-unit detached housing is snookered.

Don’t Cry For Argentina! Inflation Hits 102.5% As M2 Printing Hits 80% YoY (Suicide By Printing Press)

Don’t cry for Argentina! Their leaders did this to them.

Argetina’s inflation rate just hit 102.5% as their M2 Money printing hit 80%

Argentina’s central bank is considering raising its benchmark rate on Thursday for the first time since September after inflation data showed prices increased by more than 100% annually last month, according to two people with direct knowledge.

The monetary authority’s board will consider an increase after leaving the key Leliq rate unchanged at 75% for several months, the people said, asking not to be named discussing internal decisions. The board has not yet decided on the size of the hike in case they opt for such move, they said.

A cautionary tale for Washington DC spendacrats and Fed officials.

Brought to the same country that gave us Statist Juan Peron and his wife Eva.

Reversal Of Fortune! Fed Expected To Hike Once By 25 BPS, Then Cut Rates By 125 BPS By End Of 2023

Market now expects FED to hike max. one more time by 25bps followed by 125bps cuts in total by end of 2023.

And bond volatility is up the most since … the last financial crisis.

No, not the Klaus von Bulow “Reversal of Fortune.” Just a Fed/Biden murder of the US economy.

US Inflation Comes In Hotter Than Expected, Real Weekly Earnings At -1.9% YoY, Negative For 23rd Consective Week (Treasury 2-year Yield Rises 34 Basis Points!)

The Federal Reserve is some hard thinking to do. Inflation came in hotter than expected, so raise rates to fight inflation or lower rates to prevent bank contagion. Similar to Kevin Malone’s “Double fudge brownies or Angela” debate.

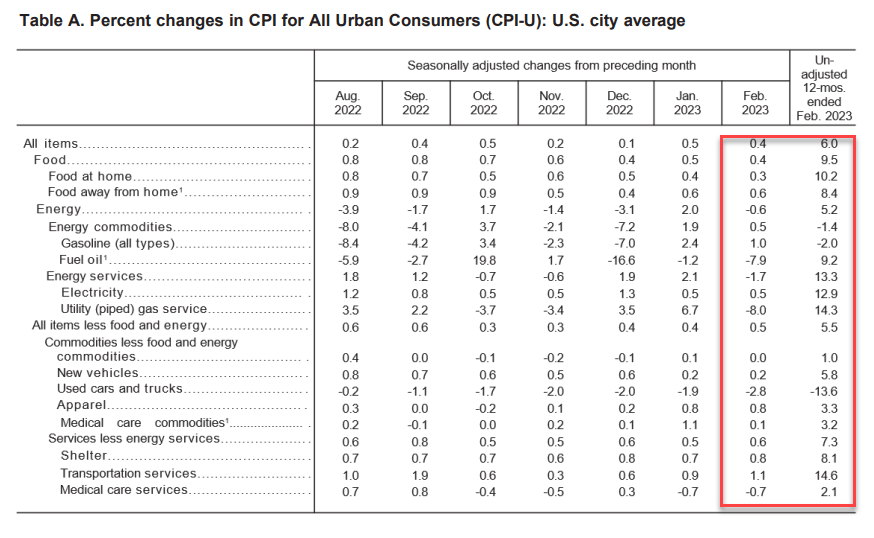
While headline inflation (CPI) came in a 6% (considerably higher than The Fed’s 2% target), core inflation came in at 5.5% year-over-year (YoY), which was expected.

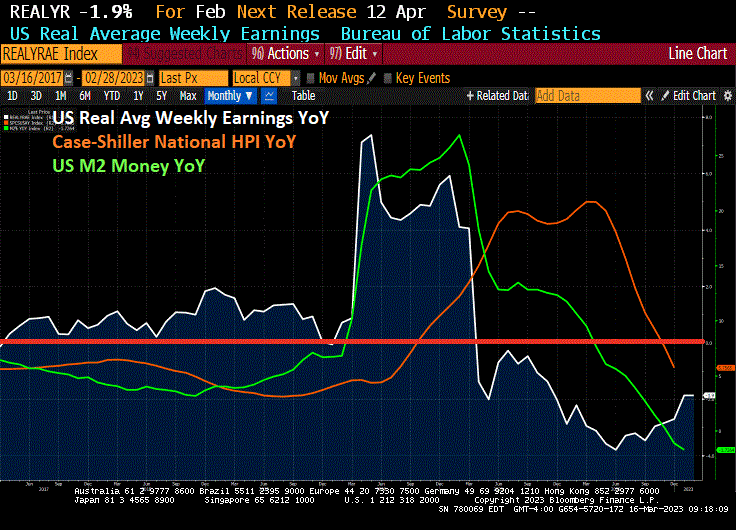
The truly nasty number is today’s inflation report is that weekly earnings YoY remained the same at a terrible -1.9%. Meaning that inflation is higher than nominal wage growth. This is the 23rd straight month of negative real weekly earnings. Well done, Fed and Biden!

Food is up 10.2% YoY. Electricity up 12.9%, shelter up 8.1%.

On the news, the US Treasury 2-year yield rose 34.3 basis points.

Somehow I doubt that Biden’s press secretary will tout 23 straight months of negative weekly earnings growth as one of Biden’s economic accomplishments.

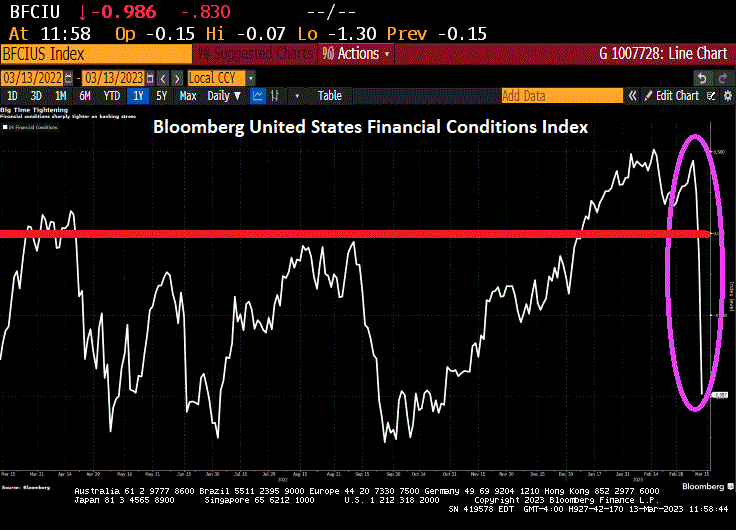
US Financial Conditions Collapse On Fed Failures (Bank Stocks Continue To Fall Despite Biden’s Assurances)

The Fed (Bernanke, Yellen, Powell) kept rates too low for too long (their new moto?), and hell is now being paid.

US financial conditions index collapsed on the 3 bank failures … so far.

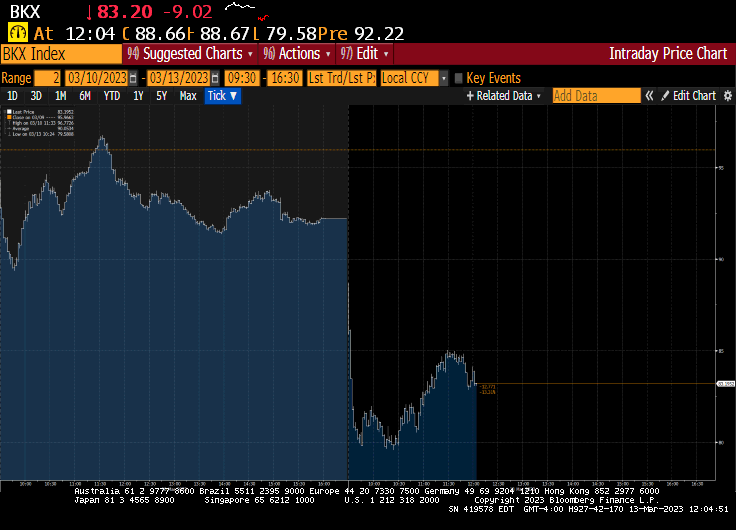
Despite what Resident Biden said about banks, bank stocks fell again today.

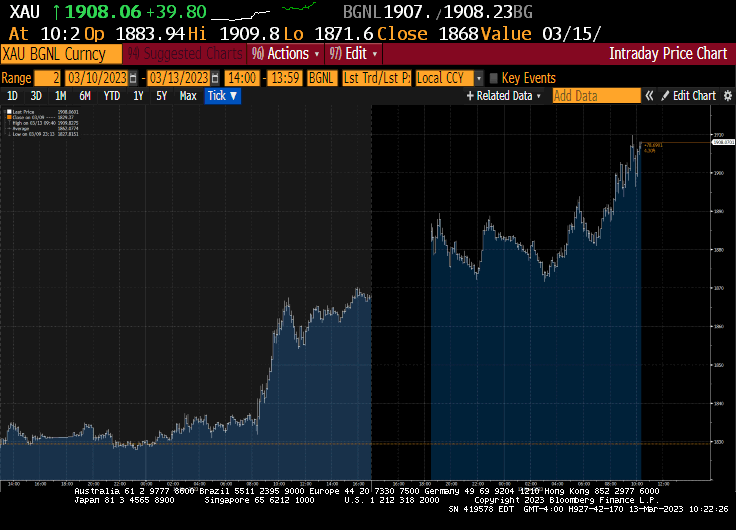
Gold Soars 2% On Failure Of Fed And Bank Regulators

All together now. The Fed has been printing too much money for too long and Biden restricts fossil fuel production. Ad in rampant Federal spending and we have INFLATION. Inflation led to The Fed to raise rates. And with rate increases and down go the banks.

Of course, The Fed and Biden Administration will overeact (e.g. offering deposit insurance on ALL deposits above $250,000 creating moral hazard risk). As such, we are seeing gold prices soar by 2% this AM.

In adddition to gold rising 2%, natural gas futures are up 6%

US Treasury Yields Drop -26 Basis Points As Fed Expected To Drop Fed Rate To 4.7% (Regulators Suddenly Awaken And Panic, Biden Calls For MORE Regulations)

The Silicon Valley Bank failure (along with NY’s Signature Bank) are sending shock waves through the global economy. Not because of the incompetence of bank regulators, but because of the reaction function from the FDIC and Fed.

The 10-year Treasury yield is down -26 basis points in the AM. And the Fed Funds Target Rate is expected to drop to 4.7%.

Its not just the US Treasury yield that declined -26 basis points. European sovereign yields are down too (Germany 10-year is down -32.9 basis points).

Look at the 2-year Treasury yield. Its down -54.6 basis points.

On a sad note, Resident Biden is calling for stricter regulations for the banking industry, already one of the most regulated sectors of the economy. How about less politics and just make them do their ^*T^R jobs!

Are You Ready? Banks Postitioned For A Bail-in As Silicon Valley Bank Fails (FDIC, Fed Weigh Special Vehicle After SVB Collapses, AOC Alert!)

Are you ready?

Despite cries from Summers, Yellen and other the DC illuminati (Biden is oddly silent), US banks are NOT fine. In fact, banks in general are suffering from Fed rates increases due to holding of long-term Treasuries and MBS.

In fact, The Federal Reserve’s fight against inflation is causing serious problems, as exemplified by AOC. No, not THAT AOC. but bank Accumulated Other Comprehensive Income.

Accumulated Other Comprehensive Income (AOCI) are special gains and losses that are listed as special items in the shareholder equity section of a company’s balance sheet. The AOCI account is the designated space for unrealized profits or losses on items that are placed in the other comprehensive income category.

On the regulatory call reports, AOCI is added to regulatory capital. Since SVB’s AOCI was negative (because of its unrealized losses on AFS securities) as of Dec. 31, it lowered the company’s total equity capital. So a fair way to gauge the negative AOCI to the bank’s total equity capital would be to divide the negative AOCI by total equity capital less AOCI — effectively adding the unrealized losses back to total equity capital for the calculation.

Getting back to our list of 10 banks that raised similar red margin flags to those of SVB, here’s the same group, in the same order, showing negative AOCI as a percentage of total equity capital as of Dec. 31. We have added SVB to the bottom of the list. The data was provided by FactSet:

Or this chart of vulnerable banks from Morningstar of unrealized losses and liquidity risk.

Here is a snapshot of SVB’s balance sheet. Or UNbalanced sheet.

After Congress passed the greatly flawed Dodd-Frank banking legislation, bailouts of banks are prohibited. But bank BAIL-INs still exist. Banks use money from their unsecured creditors, including depositors and bondholders, to restructure their capital to stay afloat. Put simply, they can convert their debt into equity to increase their capital requirements. Although depositors run the risk of losing some of their deposits, banks can only use deposits in excess of the $250,000 protection provided by the Federal Deposit Insurance Corporation (FDIC).

In any case, the FDIC and Fed are weighing a special vehicle after SVB swiftly collapses. Special vehicle? Sounds an awful like the mega bank bailout of 2008 under Hank Paulson.

No, not THIS AOC!