Fed Fireball! 30-year Mortgage Rate Breaches 5% As Fed Goes On The Offensive (Minutes Indicate Balance Sheet Shrinking Of $95 Billion Starting In May)

As the US Treasury 2-year yield hits 2.507% (up from 0.128% when Biden was installed as President) and the number of Fed rate hikes over by February 2023 hits 9.6, Bankrate’s 30-year mortgage rate breached the 5% mark at 5.04%.

The most recent data from on existing home sales show YoY sales in negative territory as The Fed begins in monetary fireball tightening.

St Louis Fed’s Bullard said The Fed is “behind the curve.” Ya think??
The Fed’s minutes from the most recent meeting indicates that The Fed will shedding $95 billion a month from it swollen balance sheet. At almost $9 trillion mostly populated by Treasuries will be the first asset to run-off the balance sheet (there is almost $1 trillion of Treasuries maturing in 2022 and $856 billion maturity in 2023, etc), The Fed plans to shrink the balance sheet while, at the same, raising The Fed Funds target rate from it near zero levels.

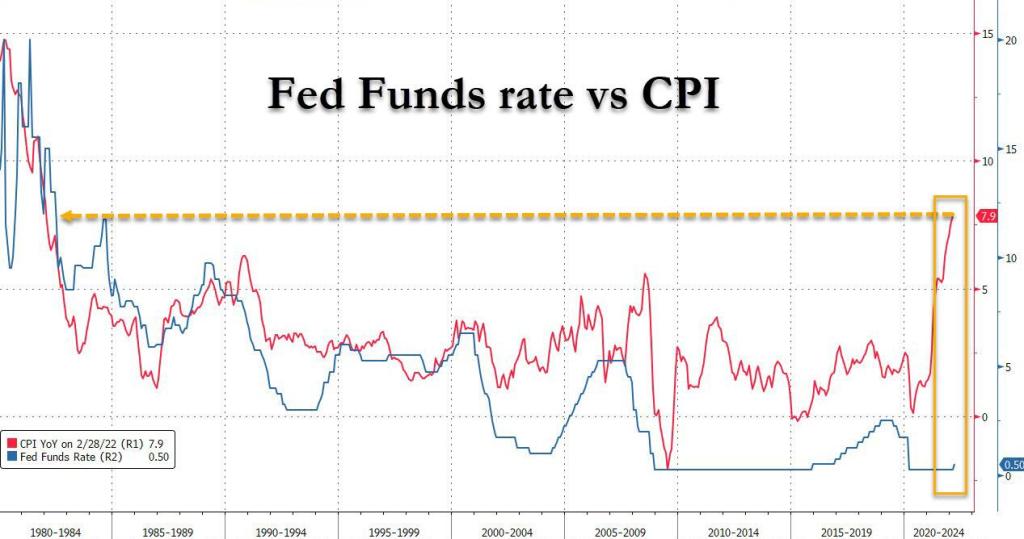
The Federal Reserve has ignoring rules like the Taylor Rule since the financial crisis of 2008-2009, but seemingly are paying attention to the Taylor Rule because of 7.9% inflation. The Taylor Rule is suggesting a 20.42% Fed Funds target while the current target rate is 0.50%. Now THAT would be a real shock to the economy.

Powell: “Unleash the Fed Fireball on the 99%!”
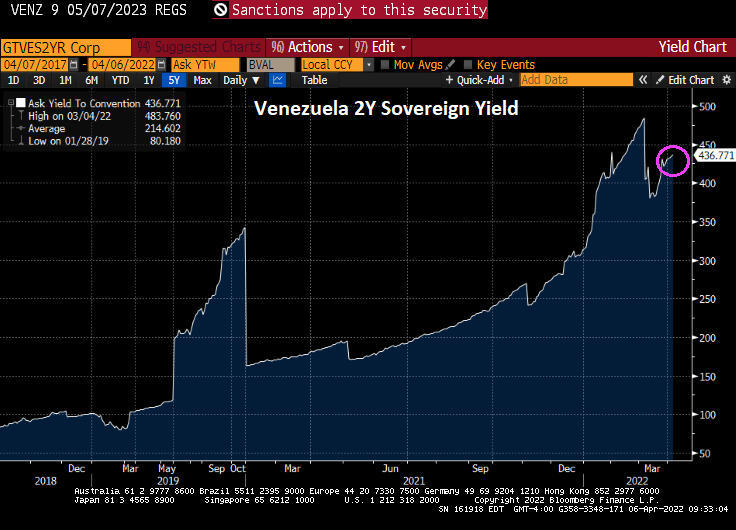
Alarm! Treasury 10Y Term Premium Remains Deeply Negative As Fed Plans Its Attack On Mortgage Rates And Treasury Yields (3M TBill/OIS Spread Crashes As 30Y Mortgage Rate Is -3%) Venezuela 2Y Yield At … 436.77%

Alarm!

The 10-year Treasury term premium, the amount by which the yield on a long-term bond is greater than the yield on shorter-term bonds, remains steeply negative (white line) as The Federal Reserve steps up its attack (aka, monetary tightening). Meanwhile, the 10Y-2Y curve actually rose into positive territory.

Historically, the 10-year Treasury Term Premium declines before a recession.

Meanwhile, 3 month Treasury bill to Overnight Indexed Swaps spread is crashing to the lowest level since 2017.

But with inflation raging at the fastest pace in 40 years, the REAL 10-year Treasury yield remains negative at -5.236% while the REAL 30-year mortgage rate is -3.01%. Both were in positive territory when Biden was installed as President.

Speaking of interest rates, the infamous PIGS (Portugal, Italy, Greece, Spain) are all seeing surges in their 10-year sovereign yields. Sweden, while not a PIG has the largest spike today at 13.8 BPS.

Actually, the biggest spike in sovereign yields occurred in Ukraine where their 2-year yield popped +205.8 BPS. But Lebanon has the highest 2-year yield at 162.29%. Turkey is in third place in the sovereign demolition derby at 23.52%. Sadly, Poland’s 2-year yield is up 16 bps today.

But the winner of the sovereign debt demolition derby is …. drumroll … VENEZUELA! At 436.77%.

I am really surprised that Biden hasn’t adopted Maduro’s fashion sense.

Euphoria! CoreLogic February Home Price Index UP 20% While Real Hourly Wages Decline (Wine Prices UP 25.1%, Foodstuffs UP 52.7 Under Biden)

Euphoria!

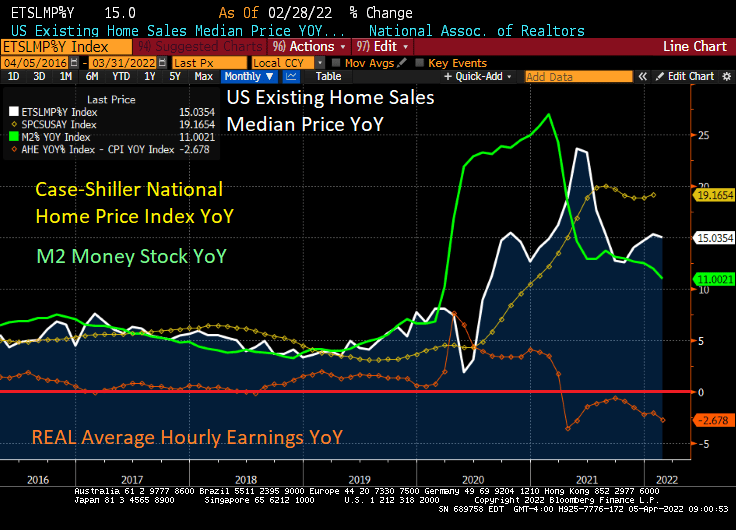
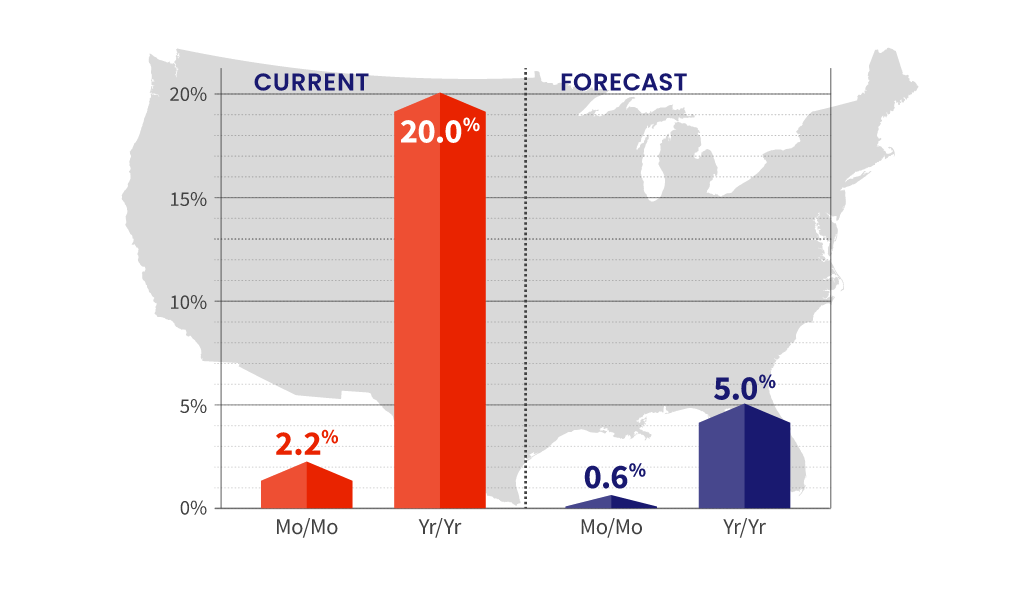
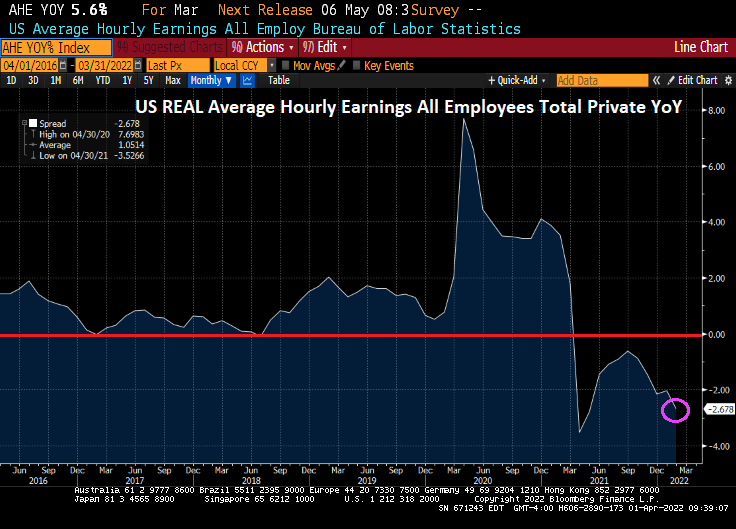
CoreLogic’s Home Price Insights revealed that home prices rose 20% YoY in February despite REAL average hourly earnings declining -2.678% YoY. THAT is euphoria! Or Stimulypto, as I like to call it.

No, The Federal Reserve still hasn’t removed its staggering monetary stimulus. Notice that M2 Money Stock is still growing at a torrid 11% pace.

20% YoY home price growth in February? CoreLogic has increased their forecast of home price growth to 5%, likely because The Federal Reserve is imitating a sloth in removing its monetary Stimulypto.

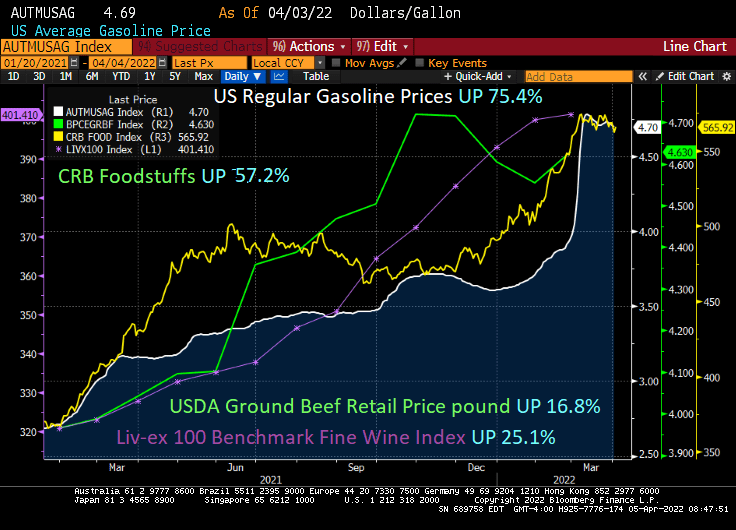
Of course, there are other assets growing at lightning speeds. US Regular gasoline prices are UP 75.4% under Biden. Foodstuffs are UP 57.2% since Biden was installed as President. At least ground beef is only up 16.8% while the fine wine index is up 25.1%.

Speaking of wine, Hitching Post II in Buellton, CA must be suffering from rising food and grape costs too (I highly recommend eating there and using their HP Magic Stuff at home). Not to mention their spectacular wines. Roast artichokes anyone??

Inversion Therapy? Yield Curve Continues Inversion As Fed Slows Down Treasury Purchases (Mortgage Rates Climb To 4.91%) Biden Orders Autos Have 49 MPG By 2026

Its official! I submitted my resignation from George Mason University effective June 1, 2022. I will miss teaching the students, past and present.

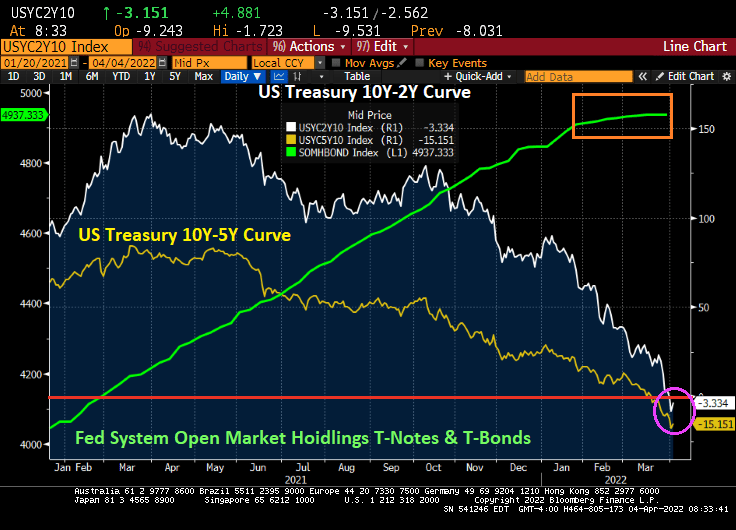
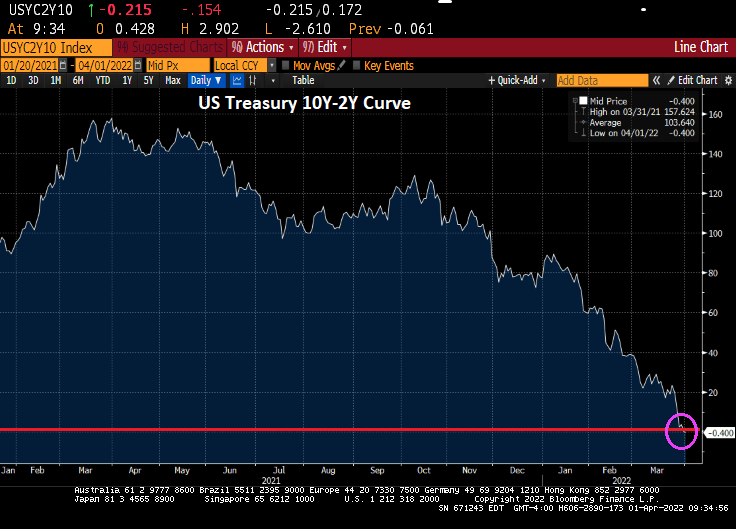
But back to the US Treasury yield curve. It remains in reversion (meaning shorter-term Treasuries have higher yields than longer-term Treasuries, usually a sign of impending recession. The Fed has actually started quantitative tightening (QT) and the growth rate of Treasury note and bond purchases has slowed to a crawl.

Meanwhile, Bankrate’s 30-year mortgage rate rose slightly to 4.91%.

Meanwhile, President Joe “The Big Guy” Biden has ordered carmakers to increase their average fuel economy to about 49 miles (78.8 kilometers) per gallon by 2026. Of course, this is intended to kill-off gasoline-powered autos and make all cars electric or hybrid like the Toyota Prius.

According to Kelley Blue Book, the average transaction price for an electric vehicle in April 2021 was $51,532. That’s more than $11,000 higher than what you’d pay at the dealership for a full-size gas-powered car, and nearly $30,000 more than the average compact car sale.

This can be the Democrat’s midterm election slogan: “Making living in the USA unaffordable!”

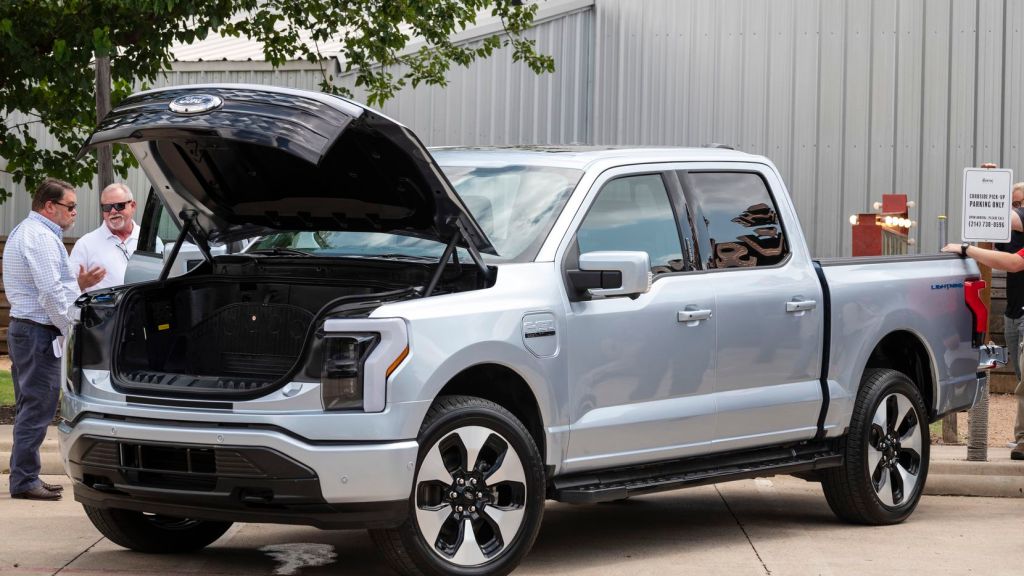
The middle-class unaffordable Ford F-150 Lightning at nearly $100,000. Thanks Joe!

Alternatively, you can buy a Buick Envision (made only in Shanghai China) with up to 24 city / 31 highway MPG. Well, kiss that baby goodbye under Biden’s new MPG mandate.

The Great Reset … In Asset Returns (Commodities Soaring, Treasuries Tanking, Home Price Growth Still 4x Soaring Mortgage Rates)

Numerous elites like Klaus Schwab of The World Economic Forum (and Davos fame) are calling for a “Great Reset” in global economies. But perhaps “The Great Reset” in taking place in asset markets … and not in a good way.
Consider what has happened since President Biden was elected. The S&P 500 total return index (green index) has risen thanks to The Federal Reserve’s balance sheet expansion (orange line) with COVID. Until 2022 when the expectation of Fed rate hikes surged from 3 in late December 2021 to 9.4 expected rate hikes over the next 12 months (yellow line).

The US Treasury total return index (white line) has gotten crushed with The Fed’s signals of rate hikes and quantitative tightening (QT). Call it “White Line Fever.” The commodity total return index (blue line) has surged as The Fed’s expected rate hikes have risen from 3 to 9.4 in 2022.

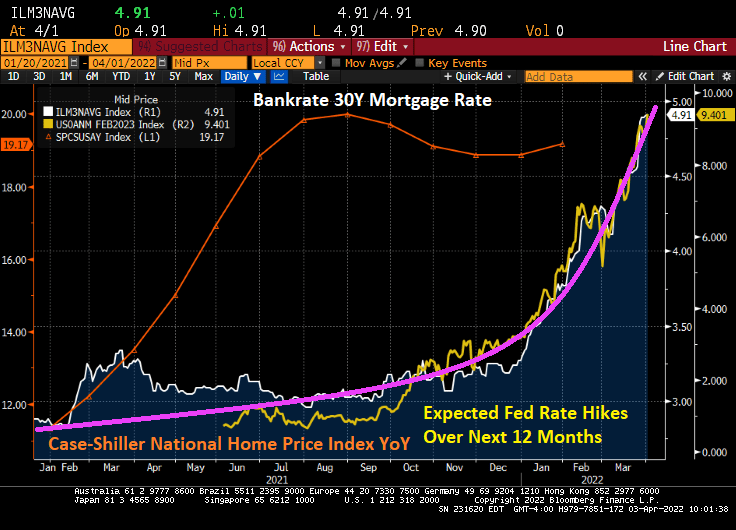
Is The Fed causing a Great Reset in housing? In 2022, we see the surge in Fed rate hike expectations leading the 30-year mortgage rate to be nearly 5%. The last Case-Shiller home price index was for January and it was still raging at 19.17% YoY growth. Let’s see if The Fed’s QT will slow down home price growth. But home prices are growing at 4x 30-year mortgage rates.

I hope that Klaus Schwab and the global elites pick us up on our way down. But probably not.

So let’s see if The Fed still is going to withdraw its “Snake Juice” from the market.

Goin’ Green! Lithium Prices UP 761% Since Biden Elected, Making Electric Cars Even MORE Unaffordable (Defense Production Act For Critical Materials)

You can always count on government to make things more expensive when they claim they want to help make things more affordable.

For example, President Biden and his green commandos are helping drive critical electric battery component LITHIUM through the roof!

Lithium hydroxide futures prices are through the roof making already expensive electric cars even MORE expensive. So much for making electric cars affordable!

Of course, The Federal government will now have to subsidize GM and Ford and increase Federal tax credits to encourage consumers to purchase outrageously expensive electric cars.

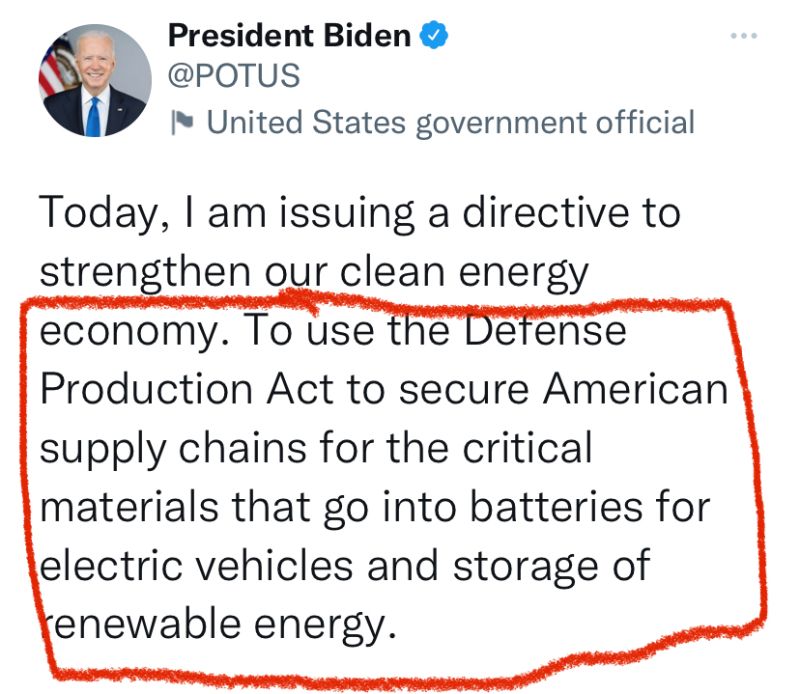
Thanks Joe for issuing your enactment of the Defense Production Act, helping to drive prices insane.

In fairness to Biden and his green commandos like AOC and Bernie Sanders (no relation to me), other nations are going electric car crazy, bidding for a scare resource like lithium. Particularly when there is an abundance of oil in the ground.

I wonder how about members of Congress and the Biden Administration bought lithium ahead of Biden declaring the Defense Production Act to encourage electric car battery production?

Wasting Away In Biden/Pelosiville! US Treasury 10Y-2Y Yield Curve INVERTS As Real Average Hourly Earnings Decline -2.678% YoY (30Y Mortgage Rate Rises To 4.90%)

Wasting away again in Biden/Pelosiville, looking for my lost inexpensive gasoline and food. Some people say that Putin is to blame, but we know its Biden/Pelosi’s fault.

The US Treasury 10Y-2Y yield curve just inverted, generally a precursor to a recession. Called it, nothing but net!

Meanwhile, today’s jobs report shows that Bidenflation is crushing America’s wage growth. While average hourly earnings grew to 5.6% YoY, we are still seeing inflation growing at 7.9% YoY meaning that inflation is reeling hurting the middle class and lower-income households.

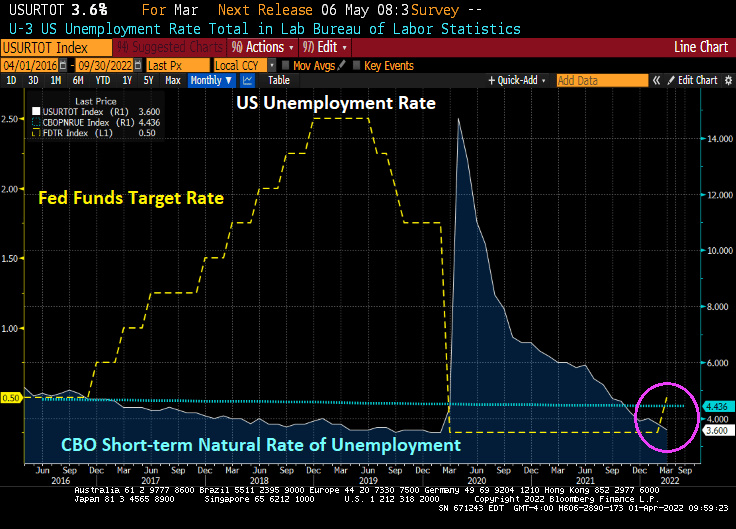
The good news is that the U-3 unemployment rate fell to 3.6%, almost back to the Trump-era unemployment rate of 3.5% prior to the Covid outbreak. And the unemployment rate remains below the CBO’s short-term natural rate of unemployment indicating that the labor market is OVERHEATED.

Today’s jobs report was pretty good, as we would expect from a recovery caused by governments shutting down economies, then reopening them. 431k jobs were added, but less than last month’s jobs added of 678k and less than the forecast 490k.

The number of people NOT in the labor force fell slightly, but it still around 100 million. The number of people holding multiple jobs to overcome Bidenflation rose to 7.5 million.

On the mortgage front, Bankrate’s 30-year mortgage rate rose to 4.90% as the 2-year Treasury rate (yellow) rises and the number of expected Fed rate hikes over the coming year is 9.26%.

Alarm! Massive Divergence Between US Treasury Yield Curve And Near-term Forward Spread (Biden Considers Releasing HUGE Oil Release To Control Inflation)

Alarm!

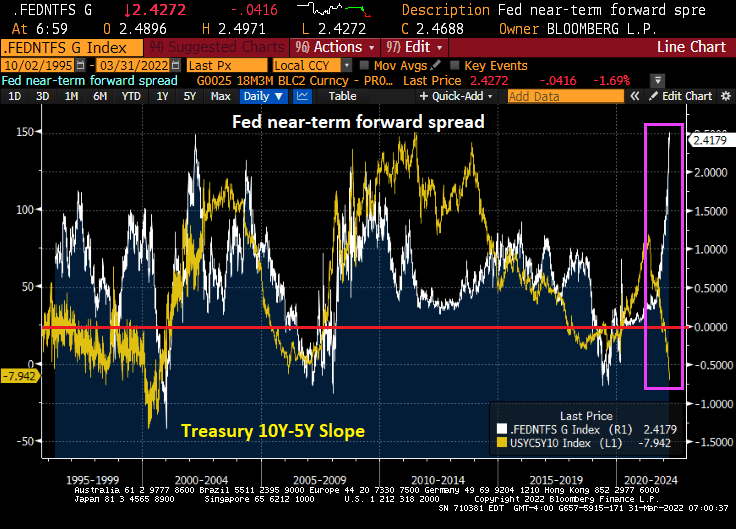
There is a massive divergence between the collapsing US Treasury 10Y-2Y yield curve and the near-term forward spread. The near-term forward spread is the difference between the implied
interest rate expected on a three-month Treasury bill six quarters ahead and the current yield on a three-month Treasury bill.

As we already know, the 10Y-5Y yield curve has inverted signaling a coming recession.

This divergence between the Treasury yield curves and the near-term forward spread is occurring as US inflation hits the highest rate in 40 years.

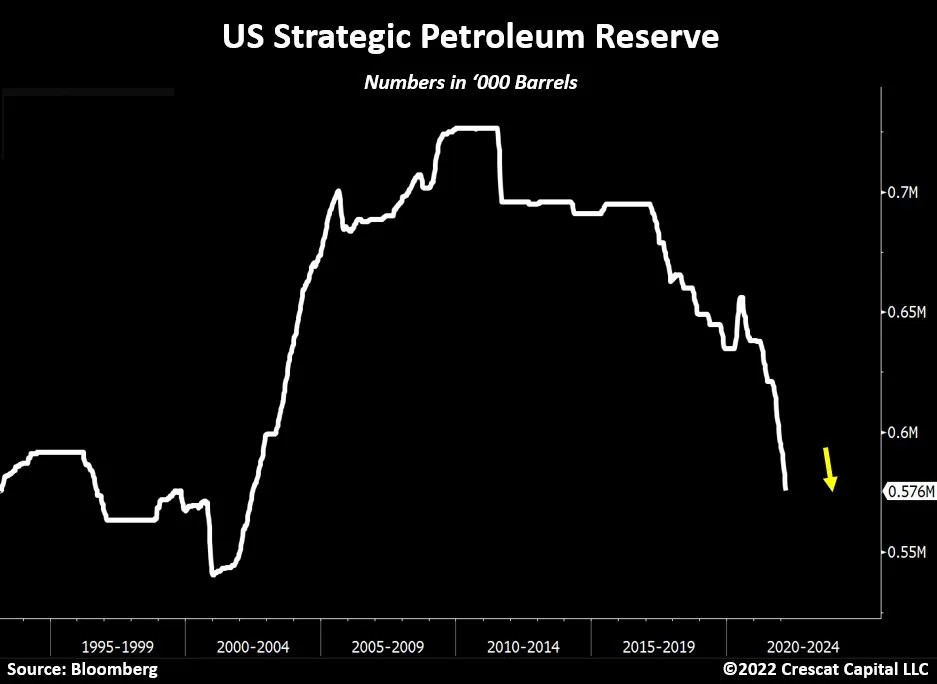
Now President Biden is considering “Releasing the Kraken!” That is, releasing a huge amount of crude oil from the nations Strategic Petroleum Reserve (SPR) in order to combat inflation. If the purpose of Biden’s executive orders were to limit fossil fuel production and consumption, why doesn’t Biden simply rescind his executive orders and allow the construction of the Keystone Pipeline?

The Powellenburg Omen! Will Powell Pop The Asset Bubble Created By The Fed’s Repeated Policy Errors? (Blackrock Rises, NVR Homes Gets Crushed)

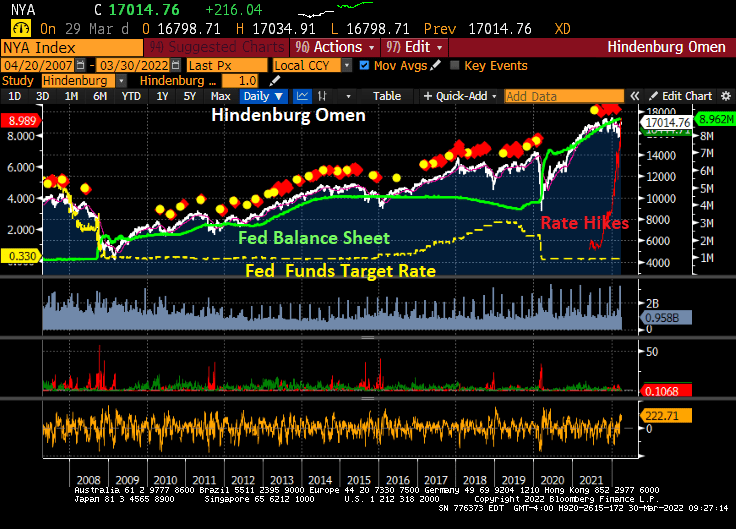
As of today, Jerome “Nero” Powell and The Gang at The Federal Reserve have not trimmed the Fed’s balance sheet and have only raised their target rate once under President Biden.

Here is the Hindenburg Omen, named for the catastrophic explosion on May 6, 1937 at Lakehurst Naval Air Station in New Jersey. The Hindenburg Omen was flashing red before the stock market correction of late 2007-2009. But, the Hindenburg Omen has flashed red repeatedly since the financial crisis, yet the S&P 500 index has kept rising. The reason? Repeated policy errors by The Fed leaving monetary stimulus in place for too long leading to a bubble forming in the stock market.

The Shiller CAPE (Cyclically-adjust price-earnings) ratio is at the second highest level since the 1800s. The highest point was the infamous Dot.com bubble and bust in 2000/2001.

Since The Fed continues to say “We have a plan!” to slow/shrink The Fed’s balance sheet and raise their target rate … it has not done anything yet (other than a 25 basis point bump at the March meeting).

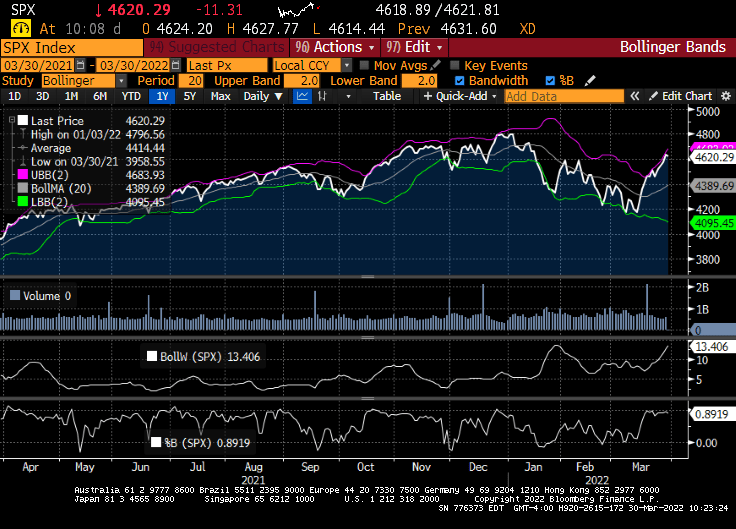
I am not advocating technical analysis for stocks, but the Bollinger Band analysis for the S&P500 index is showing the S&P 500 index near the top band indicating that a decline in likely.

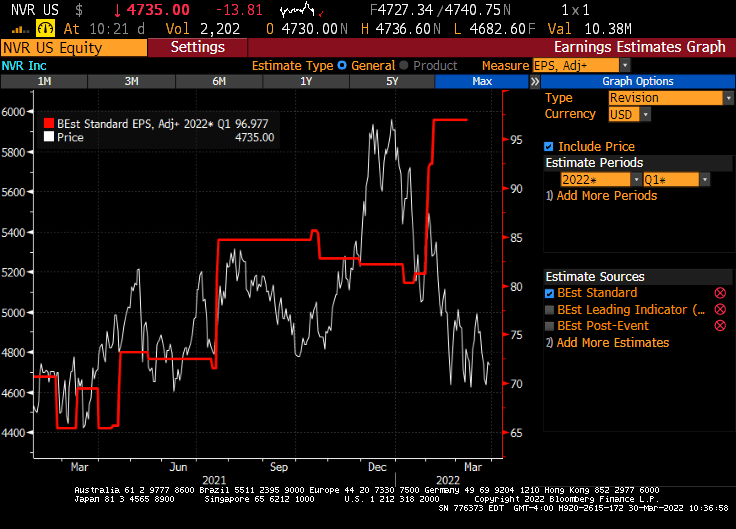
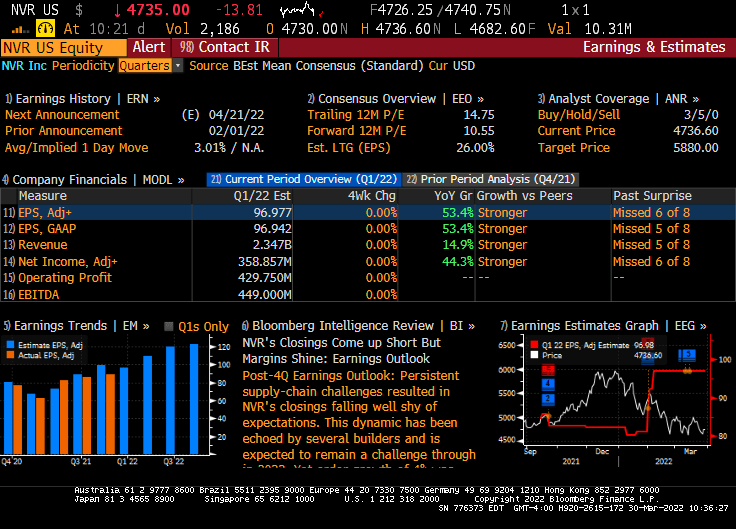
Today, the US equity market in essentially flat given the massive uncertainty about the Russia/Ukraine situation and whether the US economy is slipping into darkness. But this morning, Federal government blessed companies (healthcare, solar energy and Blackrock) are doing quite well, while homebuider NVR is taking it on the chin thanks to hints that The Fed will raising rates.

Now, NVR (Northern Virginia Homes, Ryan Homes) had explosive earnings growth in their February 1, 2022 report.

But the market is pricing in the crushing Fed rate hikes that are expected.

So, will Foul Powell pull a Volcker and raise rates and crush the economy (and stocks)? Or will Foul Powell And The Fed gang let inflation burn out of control, but preserve the massive asset bubbles?

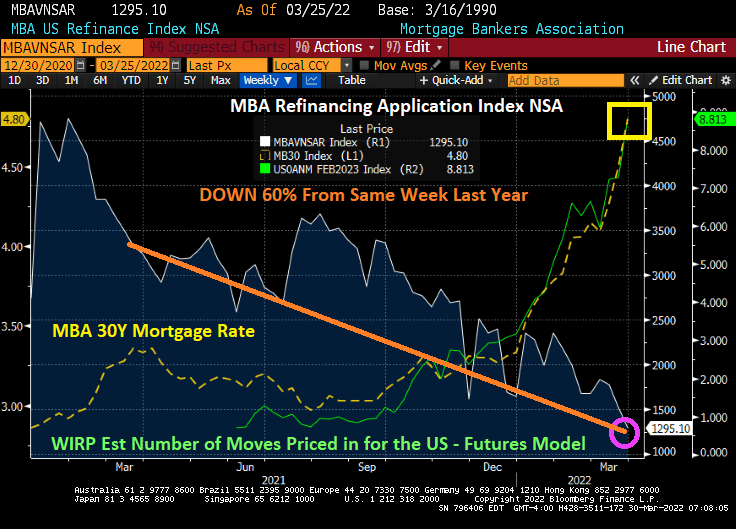
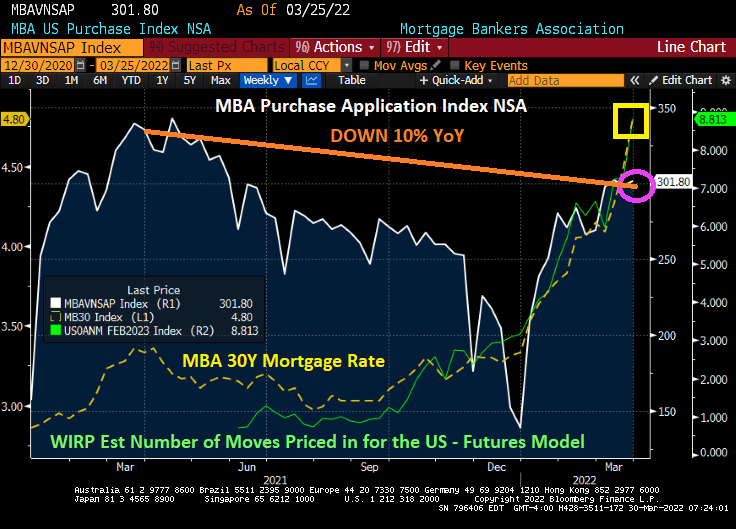
Mortgage Refi Applications Drop 15% Since Last Week As Fed Rate Hikes Cool Market (But MBA Purchase Applications Rose 1% WoW)

Anticipation about Federal Reserve rate hikes over the next 12 months are seeding mortgage rates soaring and mortgage refinancing applications plummeting.

Mortgage applications decreased 6.8 percent from one week earlier, according to data from the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey for the week ending March 25, 2022.

The Refinance Index decreased 15 percent from the previous week and was 60 percent lower than the same week one year ago. 

The seasonally adjusted Purchase Index increased 1 percent from one week earlier. The unadjusted Purchase Index increased 1 percent compared with the previous week and was 10 percent lower than the same week one year ago.

Yes, I am surprised at the rise in mortgage purchase applications with rising mortgage rates, unless, of course, people are trying to buy ahead of Fed rate increases.

While The Federal Reserve led to a scorcher in asset prices since 2008, rapid rate increases and quantitative tightening (QT) will have a chilling effect on the housing market.