The US is short on supply of housing for a myriad of reasons (high costs, Not-in-my-backyard (NIMBY) local zoning laws, etc), but The Fed’s cranking up interest rates isn’t helping.
US housing starts, a measure of supply, declined -6.3% YoY in June as The Fed cranked up rates.
1-unit (aka, single family detached) starts dropped -8.05% MoM in June while 5+ unit (aka, multifamily) starts rose 15% MoM.
1-unit permits dropped -8% MoM in June while 5+ unit starts were up 13% MoM.
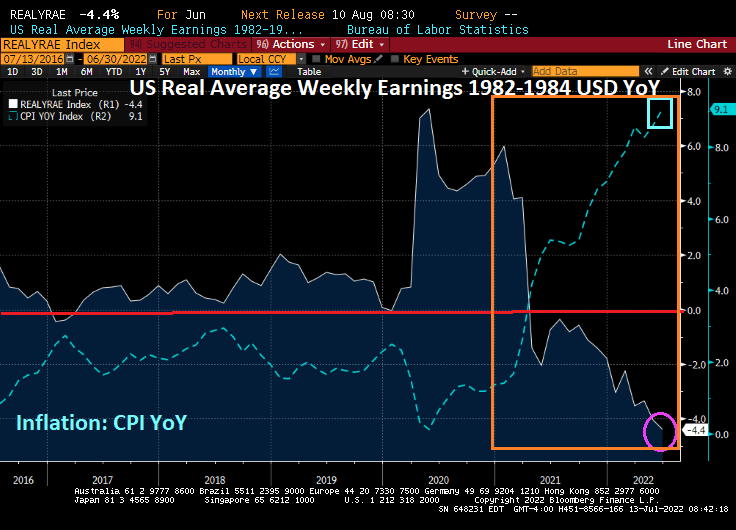
The reason? REAL weekly earnings growth declined -4.4% YoY in June thanks to Bidenflation.
As Americans are painfully aware, inflation is the highest in 40 years prompting The Federal Reserve to remove the massive punch bowl. In fact, Federal Reserve Governor Christopher “Fats” Waller backed raising rates by 75 basis points this month.
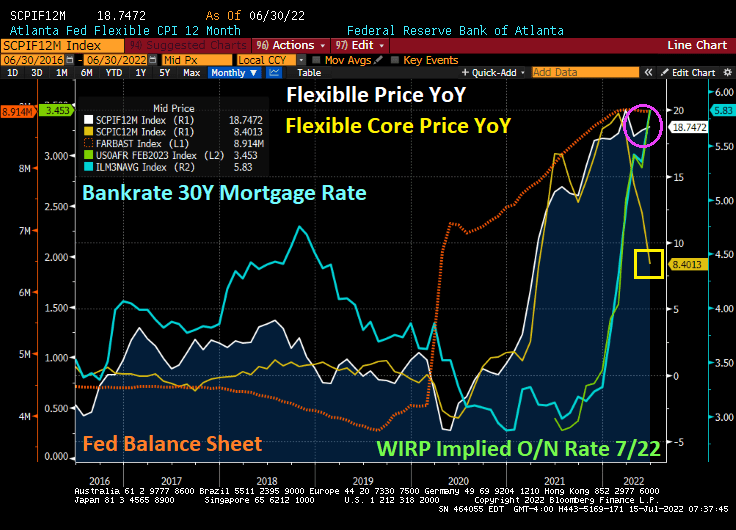
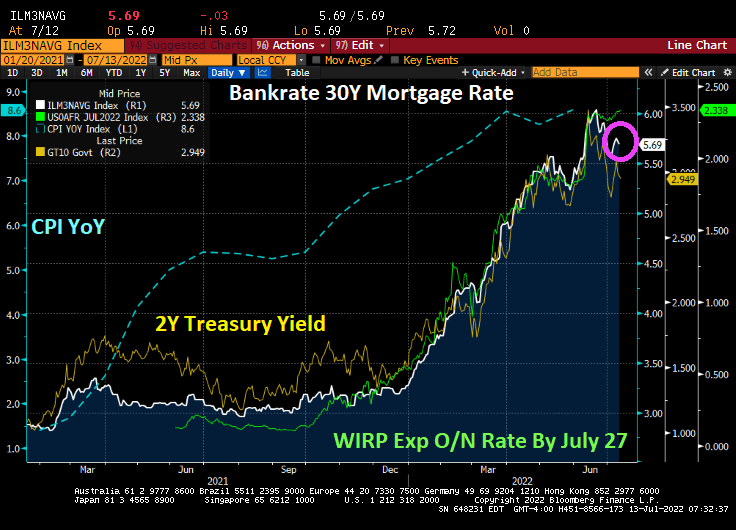
How hot was the recent inflation report? The Atlanta Fed’s flexible price index rose to 18.74% YoY. On the other hand, the CORE flexible price index (less energy and food) plunged to 8.46% YoY. The 30-year mortgage rate from Bankrate rose slightly to 5.83% as the implied overnight rate for the July FOMC meeting rose to 3.45%.
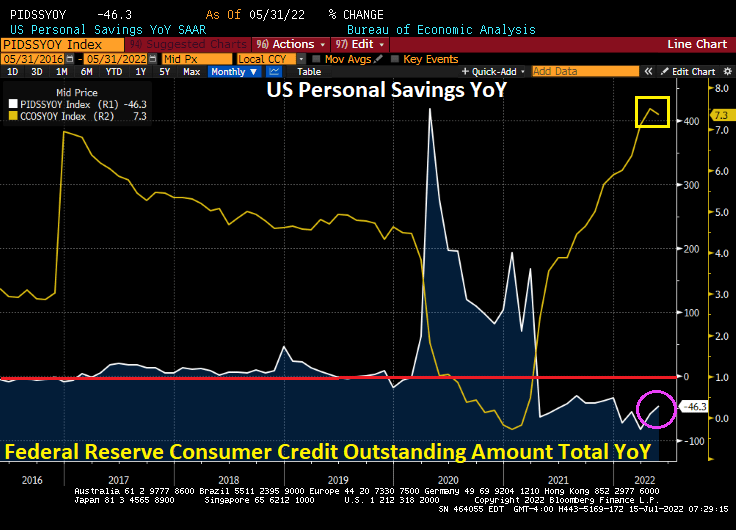
Inflation is ravaging consumers with the savings rate falling by -46.3% YoY while consumer credit rose 7.3% YoY. Yes, thanks to high inflation, consumers are saving less and borrowing more.
When even CORE flexible price inflation is 8.40% YoY, you know that The Fed and Federal government have made serious policy errors.
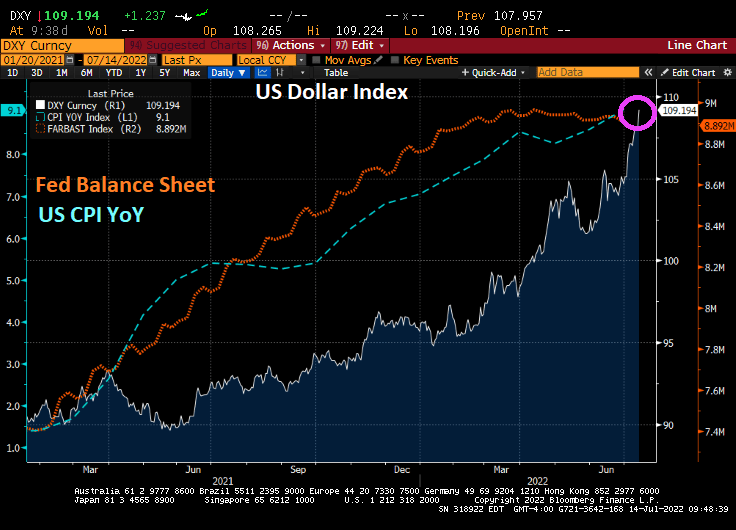
Bear in mind that a strong dollar is a two-edged sword. The US Dollar Index has risen 16% year-over-year, presenting a big hurdle for US firms with business overseas.
That strength of the greenback will rise until the Fed makes a dovish policy pivot.
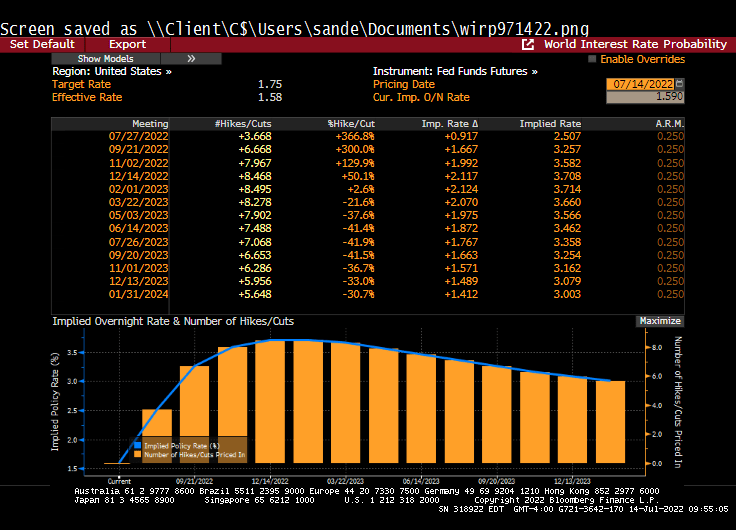
And that pivot is forecast to occur at the Feb ’23 FOMC meeting.
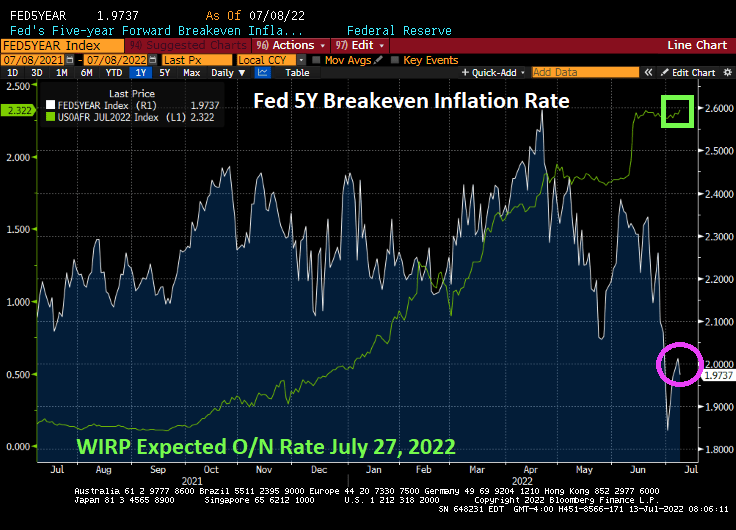
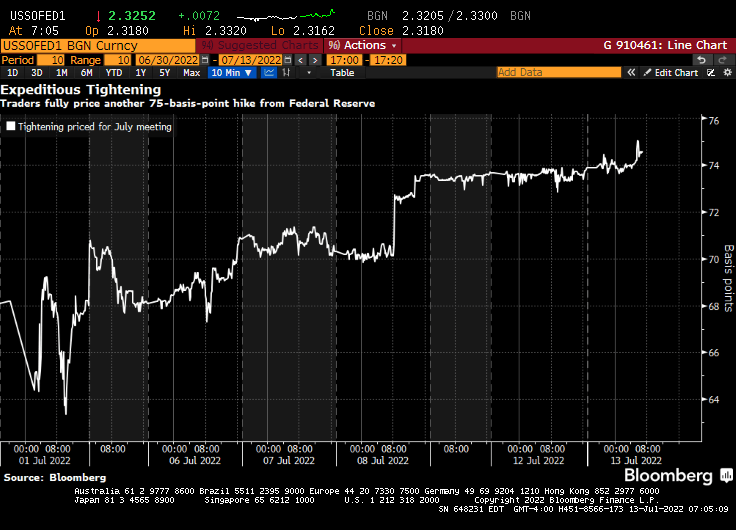
Here we go loop de loop! Traders are pricing in a 75 basis point rate increase at the July FOMC meeting despite collapsing Fed 5-year inflation breakeven rates.
Money markets are betting on a three quarter-percentage point hike by Federal Reserve officials later this month, wagering the US will need to ramp up the pace of monetary tightening to tame inflation.
The repricing comes ahead of a key inflation report due Wednesday. The headline figure for June is set to accelerate to 8.8% year over year, the highest since 1981.
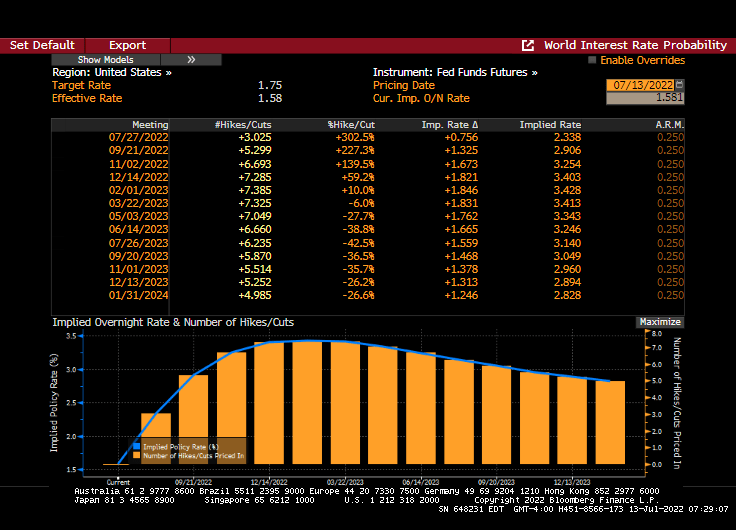
Bankrate’s 30Y mortgage rate fell slightly ahead of today’s inflation report with the expectation of The Fed hiking their target rate by 75 basis points to 2.338% at the July 27th Fed Open Market Committee meeting.
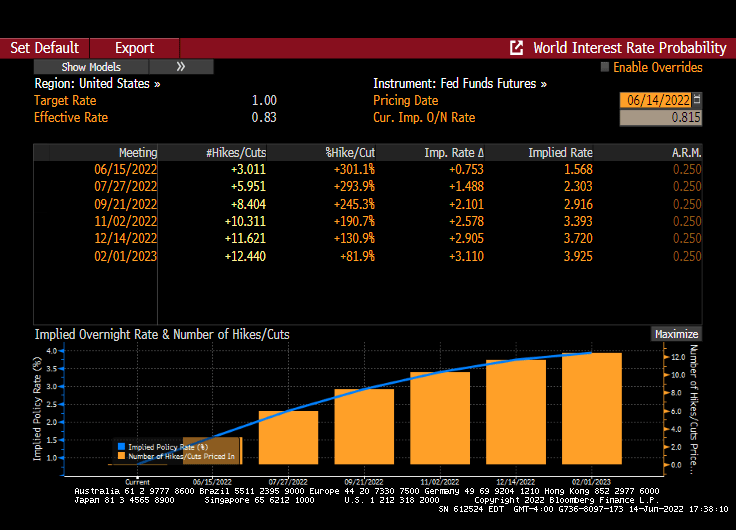
Trader expectations from Fed Funds Futures data:
Last night I watched “The Shallows” on Peacock TV. I thought from the title that it was going to be a biography of The Federal Reserve, but it was a film about a surfer being attacked by a shark.
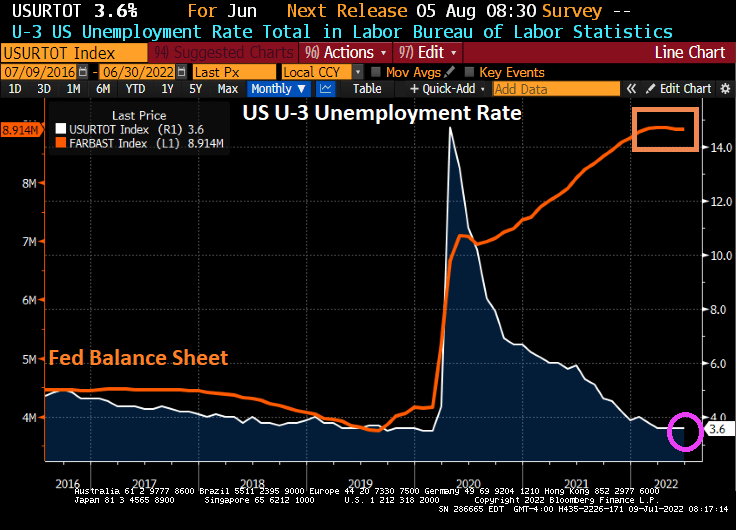
Take the US U-3 unemployment rate. The Biden Administration is proud of the unemployment rate of 3.6%. But if you look at the chart of unemployment relative to The Fed’s balance sheet expansion due to Covid lockdowns, there is still almost $9 trillion of Fed stimulus outstanding.
Of course, the lockdowns were pure economy killers, so opening the economies again led to the unemployment rate falling to 3.6% which is still higher than before the Covid outbreak. But The Federal Reserve has been painfully slow at shrinking its balance sheet, leaving almost $9 trillion in monetary stimulus outstanding.
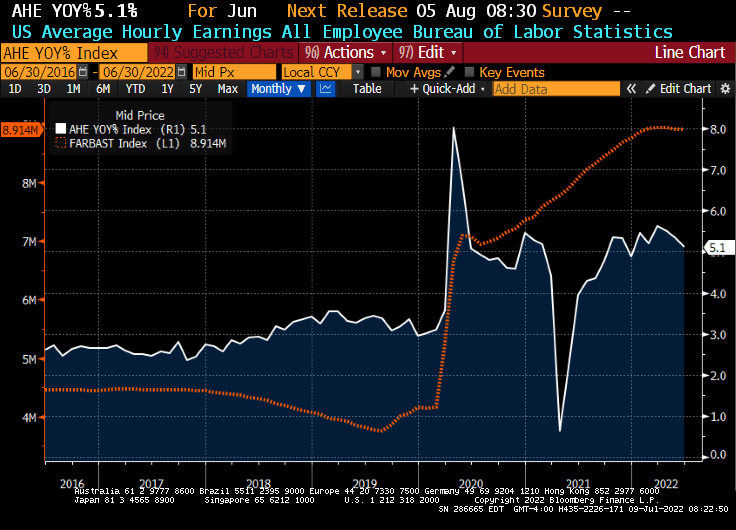
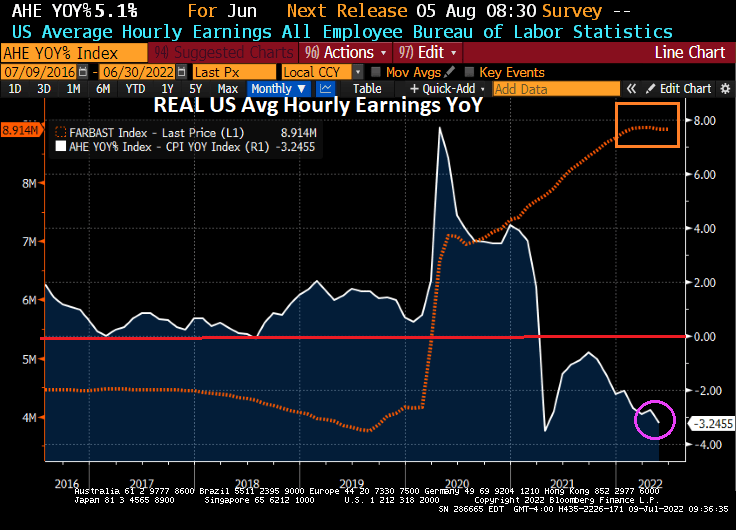
Take average hourly earnings growth. The media is all smiles as US wage growth declined to 5.1%, much higher than pre-Covid.
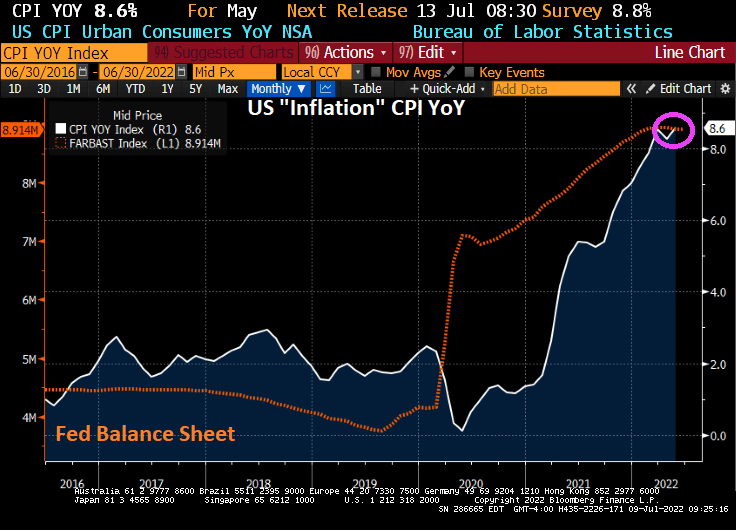
Then we have inflation, at 40-years highs thanks to massive Fed stimulus (and Federal spending).
And if we deduct inflation from average hourly wage growth, we see REAL wage growth declining at a -3.25% YoY clip.
Lastly, we have the US Dollar. Nothing has been the same since the financial crisis of 2008 and the entrance of The Federal Reserve distorting the economy and prices. Not to mention the US Dollar.
The Fed leaving its monetary stimulus out in force for so long is a major policy error. So what happens when The Fed actually gets serious about withdrawing the monetary stimulus (likely after the midterm elections)?
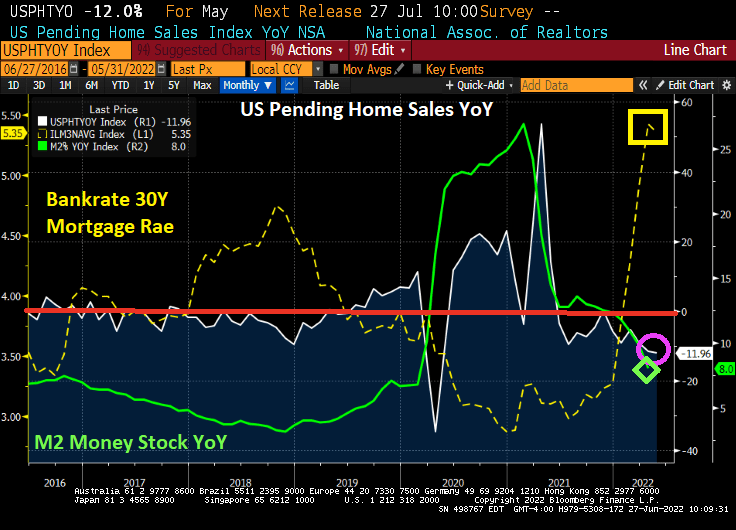
US pending home sales declined -12% YoY in May as The Fed cranked up mortgage rates. That was 11 out of the last 12 months had declining pending home sales.
Today, WTI crude oil futures broke through the $110 barrier.
The WTI Crude crack spread, the differential between the price of crude oil and petroleum products extracted from it, is up 535% under President “I HATE OIL!” Biden and diesel fuel is up 121%.
WTI crude is up 1% today.
“Crack? I thought crack was something that Hunter did!” – Joe Biden
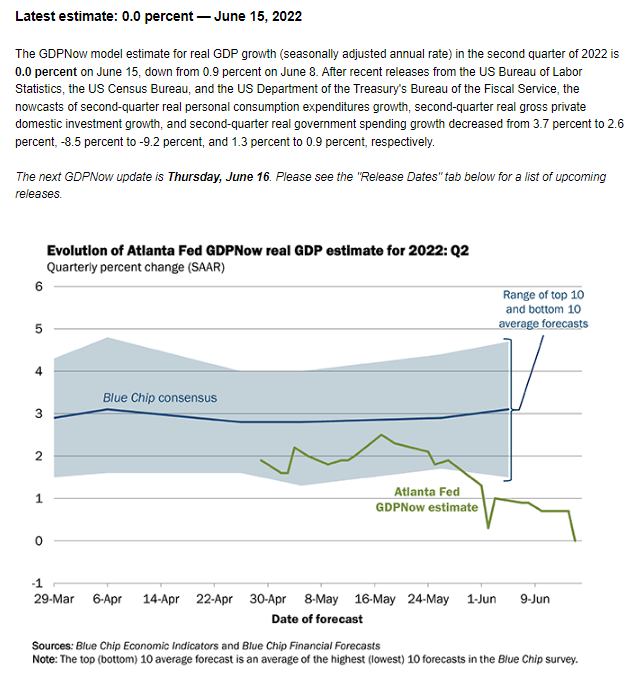
Sometimes I wonder if The Federal Reserve Board of Governors pays attention to economic news. For example, the Atlanta Fed’s GDPNow forecast for Q2 was released today at -0.002%. So what does The Fed do? They raised their target rate by 75 basis points to 1.75%.
Apparently, The Fed has chosen to fight inflation rather than help the economy.
I just read that President Biden has never been more optimistic about the US economy than he is now.
Well, today’s closing bell is not optimistic and is downright bearish.
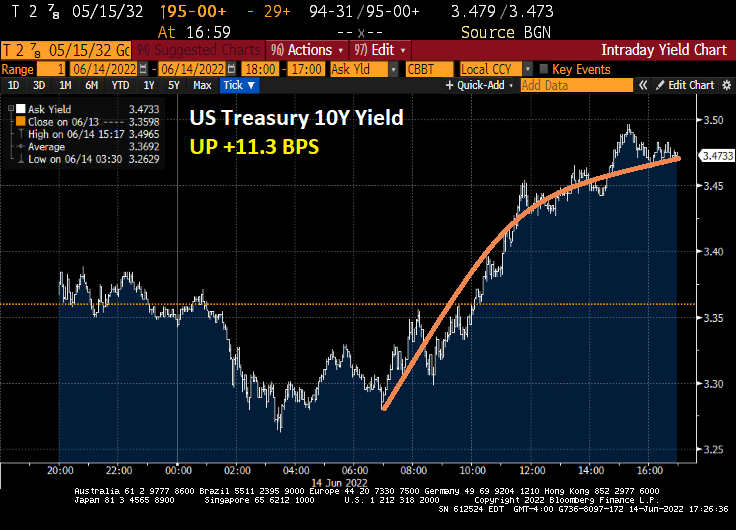
The US Treasury 10-year yield rose … ANOTHER … 11.3 basis points as rumors circulate that The Fed might actually raise their target rate by 75 basis points.
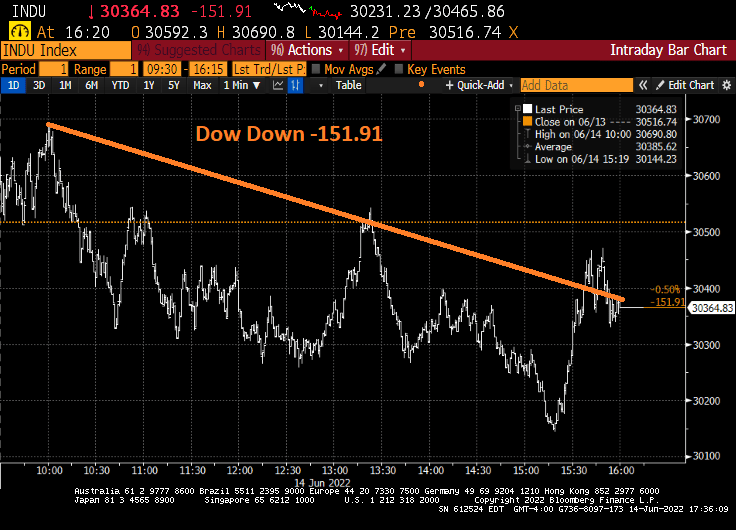
And the venerable Dow (DJIA) is down -152 points today.
Markets are anticipating an increase of The Fed Funds target rate from 1% to 1.568%, less than the rumored 75 basis point increase being bandied about.
If Biden is wildly optimistic about the economy, then he needs to get out of The White House and talk to average Americans and not people like Robert De Niro.











You must be logged in to post a comment.