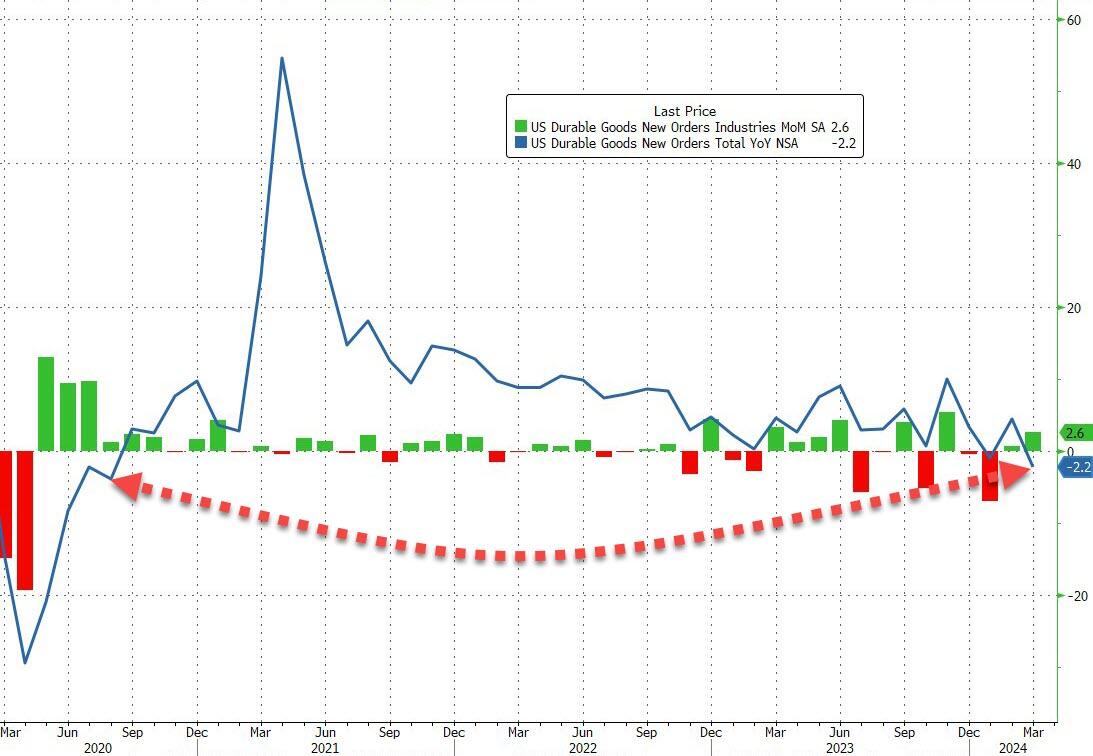
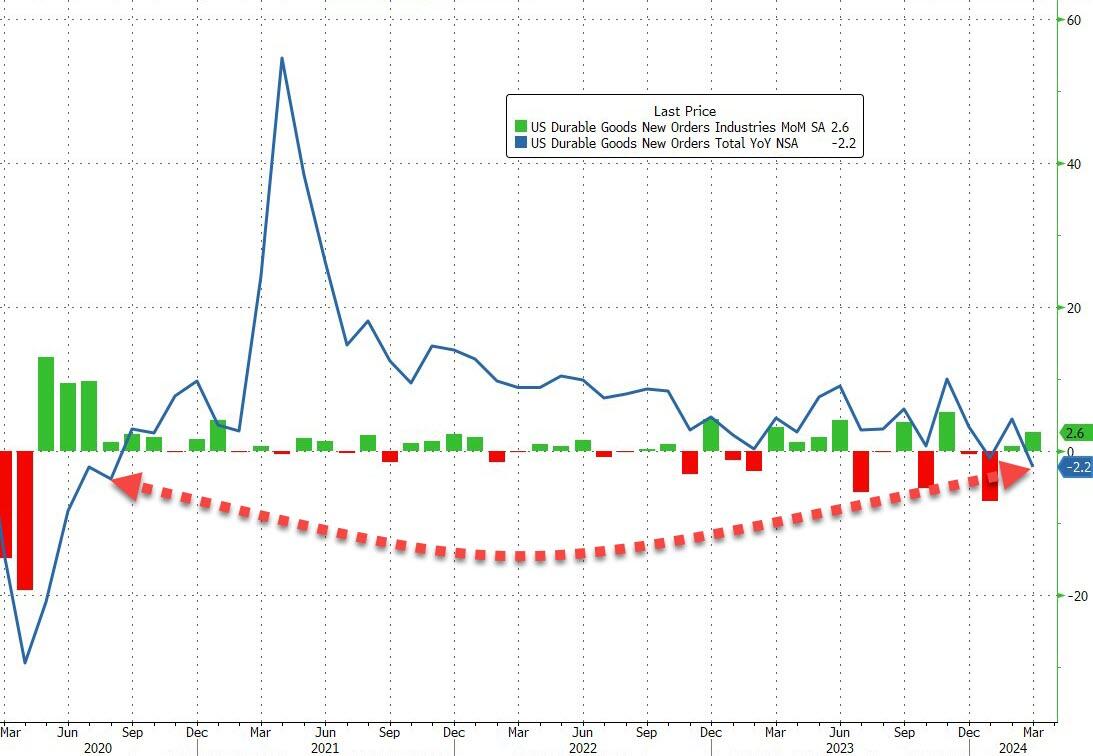
Manufacturer’s Durable Goods New Orders growth peaked in April 2021, thanks in part to M2 Money Growth peaking in February 2021. And its been all downhill since then.
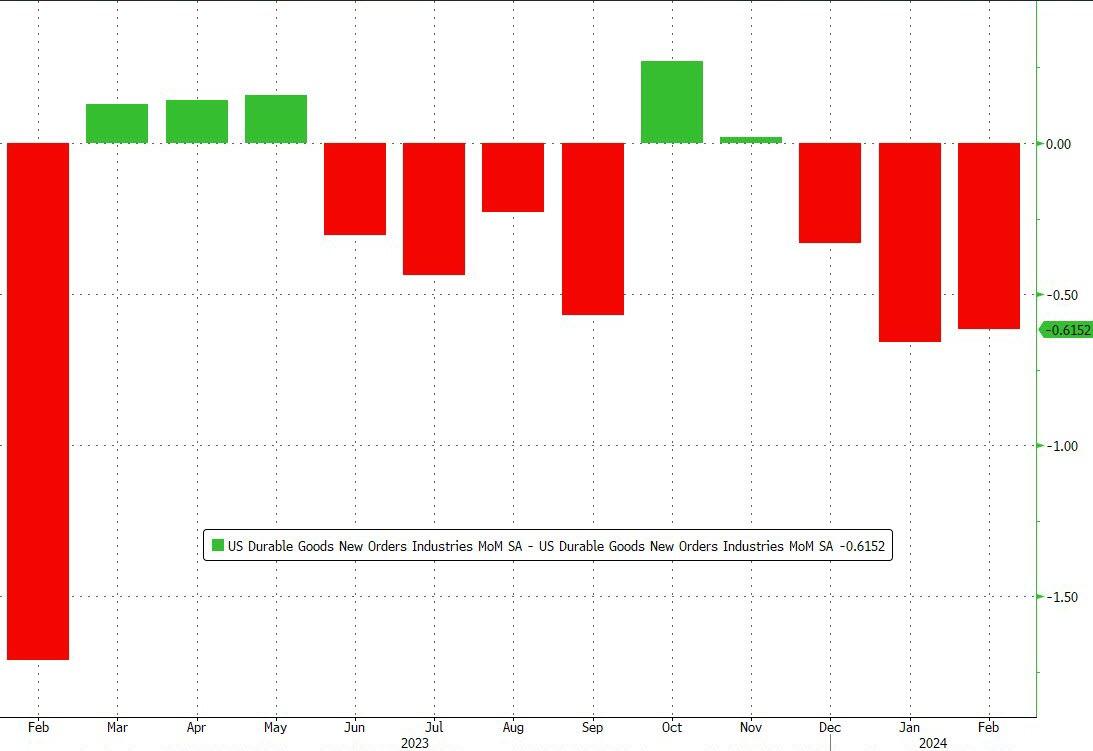
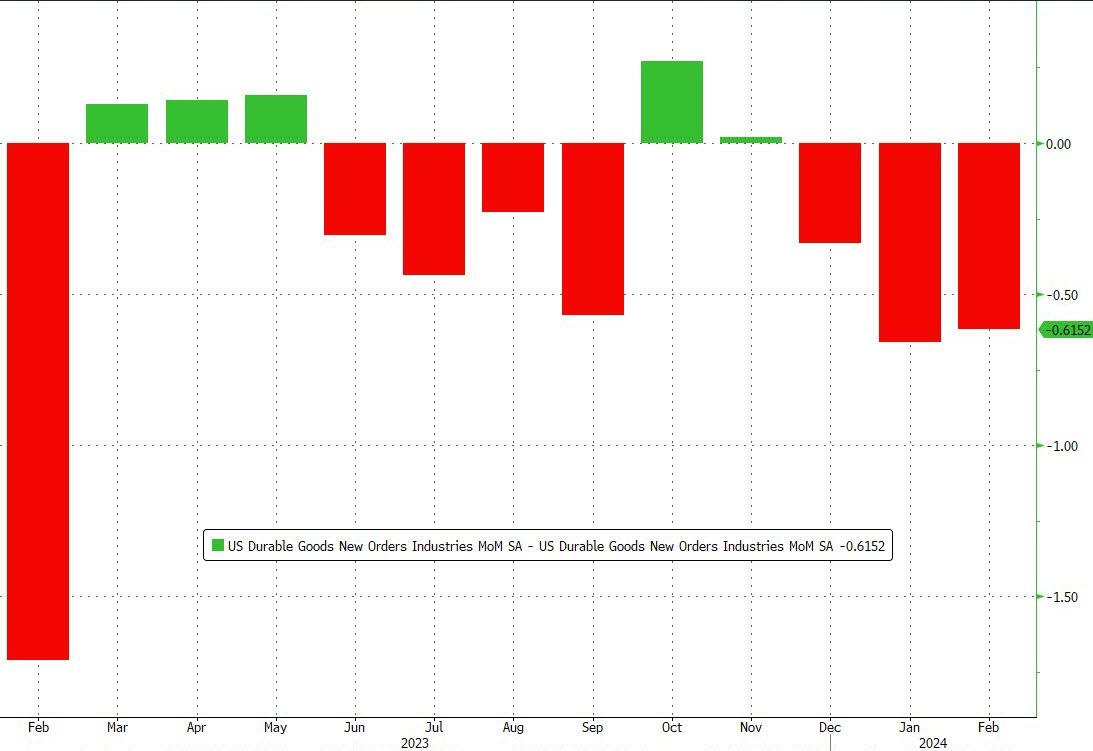
This is the 8th downward revision of durable goods orders in the last year…
Source: Bloomberg
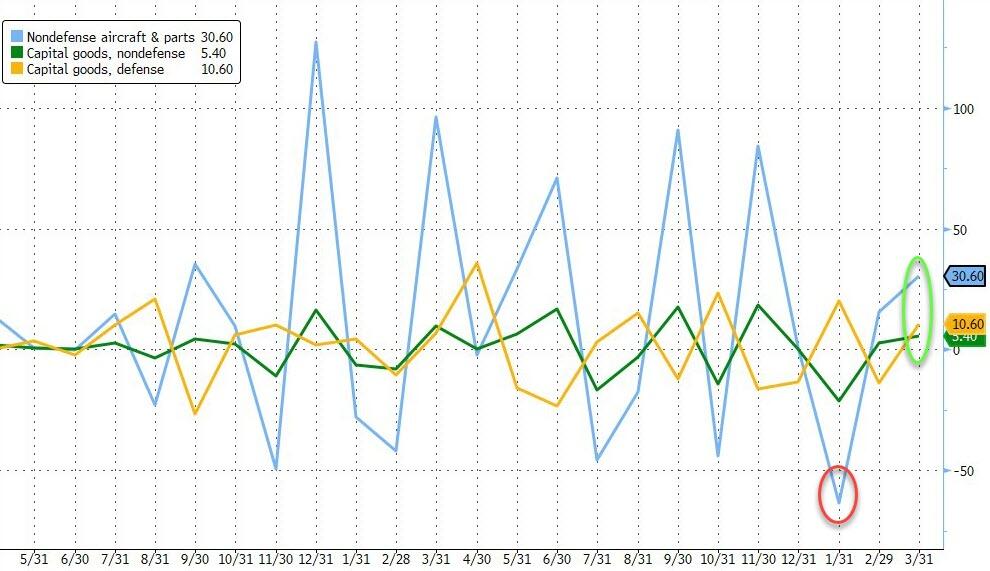
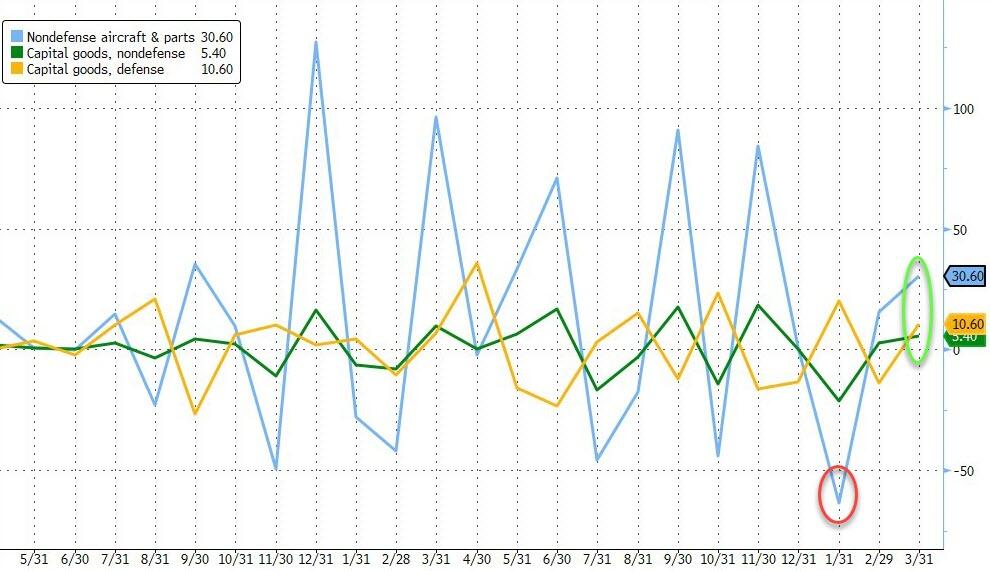
Under the hood, defense and non-defense capital goods orders rose with non-defense aircraft orders surging over 30% MoM…
Source: Bloomberg
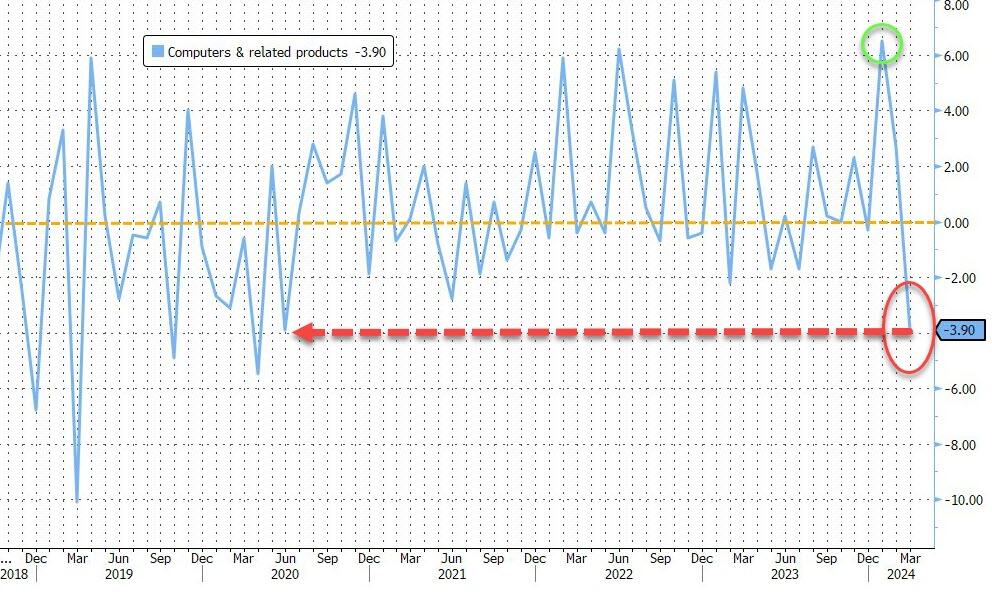
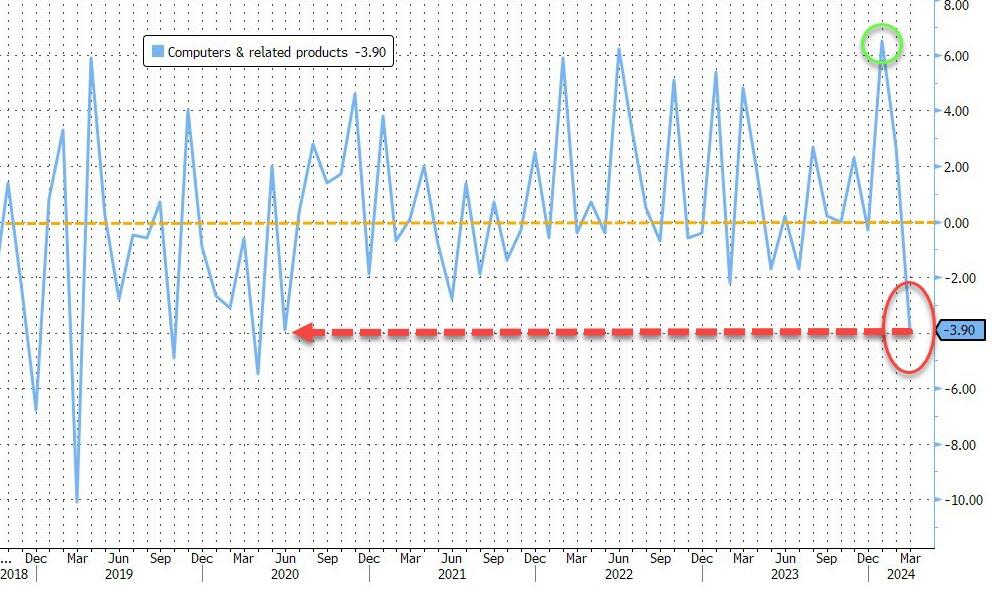
But… it looks like the AI bubble just burst as Computer & related Products orders plunged 3.9% MoM – the biggest drop since COVID lockdowns…
Source: Bloomberg
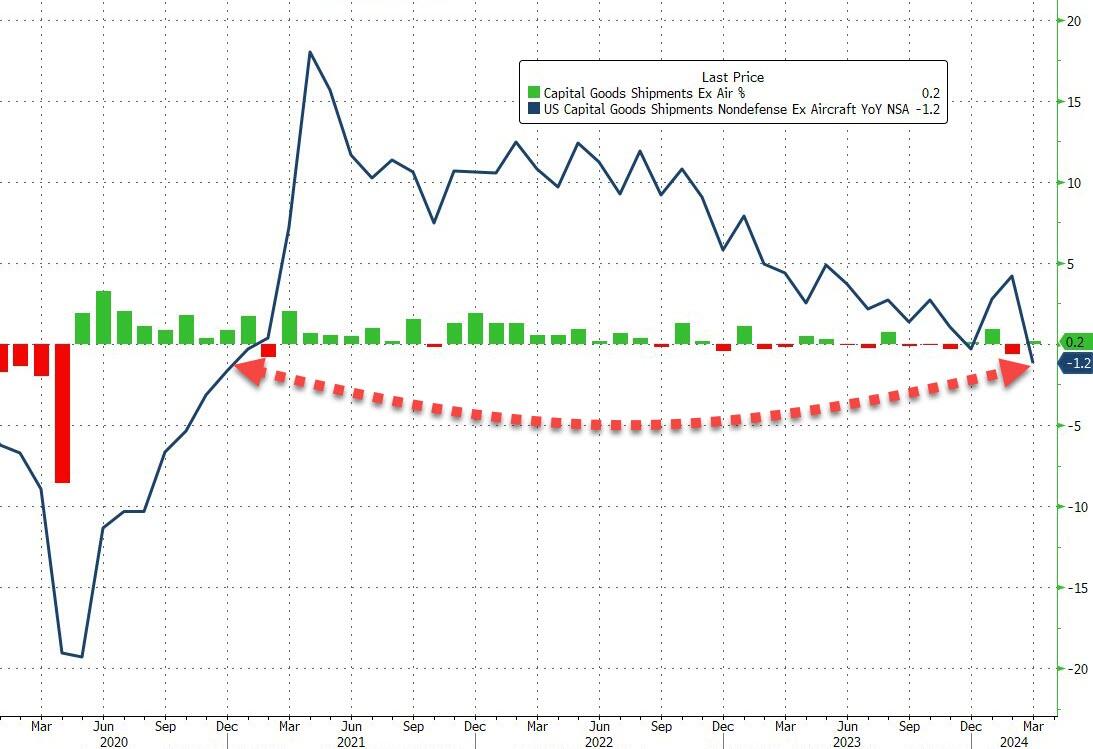
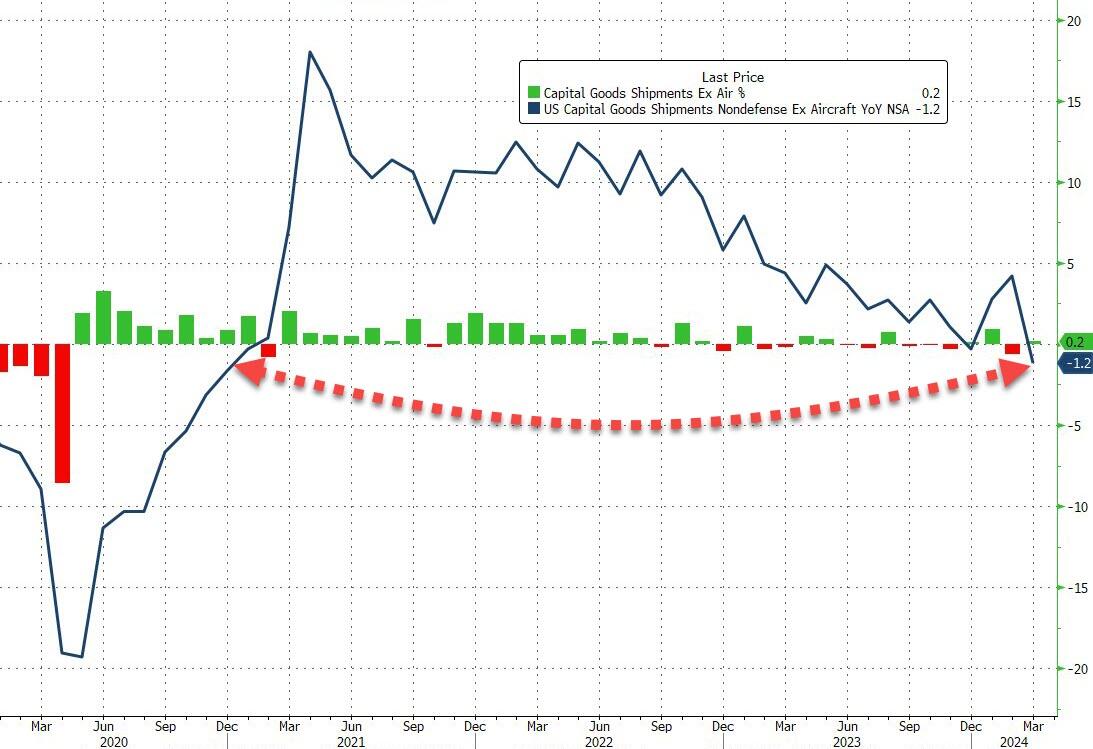
Finally, and more problematically, core capital goods shipments – a figure that is used to help calculate equipment investment in the government’s gross domestic product report – saw only a small 0.2% MoM rise, which left core shipments down 1.2% YoY – the biggest YoY drop since the COVID lockdowns…
Source: Bloomberg
Now that Biden is considering a NATIONAL CLIMATE EMERGENCY granting him 130 War-like powers, I shudder to think for much green spending he will initiate.
Biden: “How many times does Trump have to prove we can’t be trusted?”
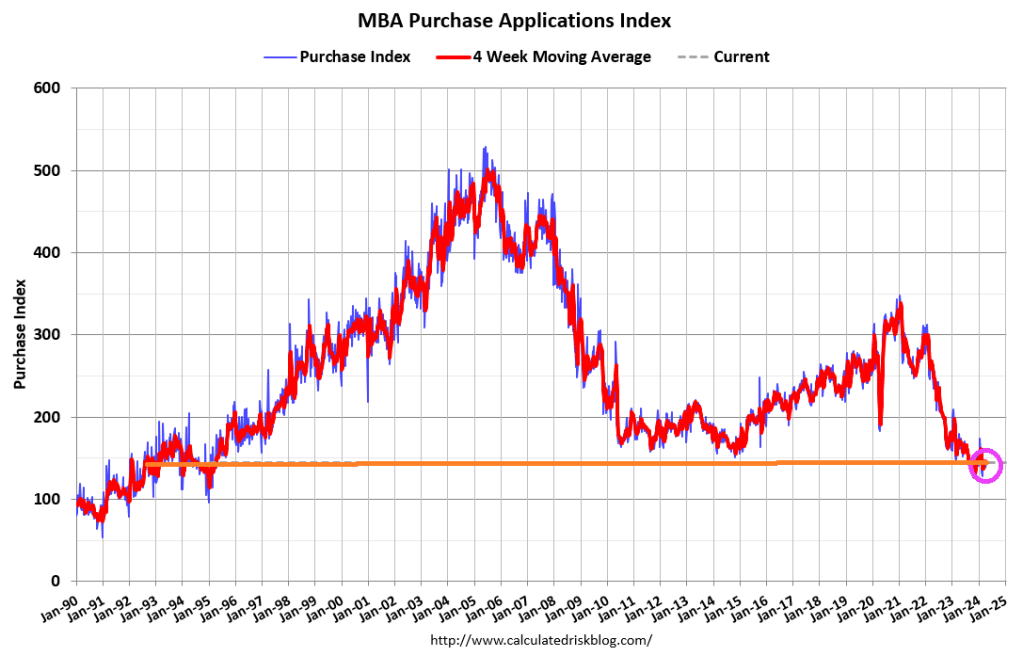
Mortgage applications decreased 2.7 percent from one week earlier, according to data from the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey for the week ending April 19, 2024.
The Market Composite Index, a measure of mortgage loan application volume, decreased 2.7 percent on a seasonally adjusted basis from one week earlier. On an unadjusted basis, the Index decreased 2 percent compared with the previous week. The seasonally adjusted Purchase Index decreased 1 percent from one week earlier. The unadjusted Purchase Index increased 0.2 percent compared with the previous week and was15 percent lower than the same week one year ago.
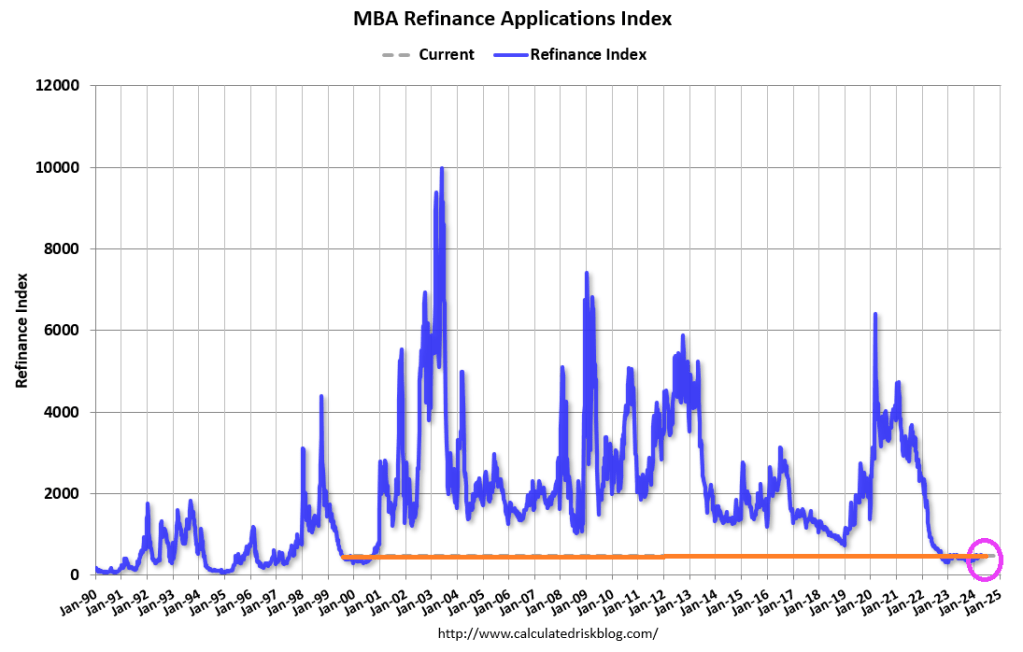
The Refinance Index decreased 6 percent from the previous week and was 3 percent higher than the same week one year ago.
The average contract interest rate for 30-year fixed-rate mortgages with conforming loan balances ($766,550 or less) increased to 7.24 percent from 7.13 percent, with points increasing to 0.66 from 0.65 (including the origination fee) for 80 percent loan-to-value ratio (LTV) loans.
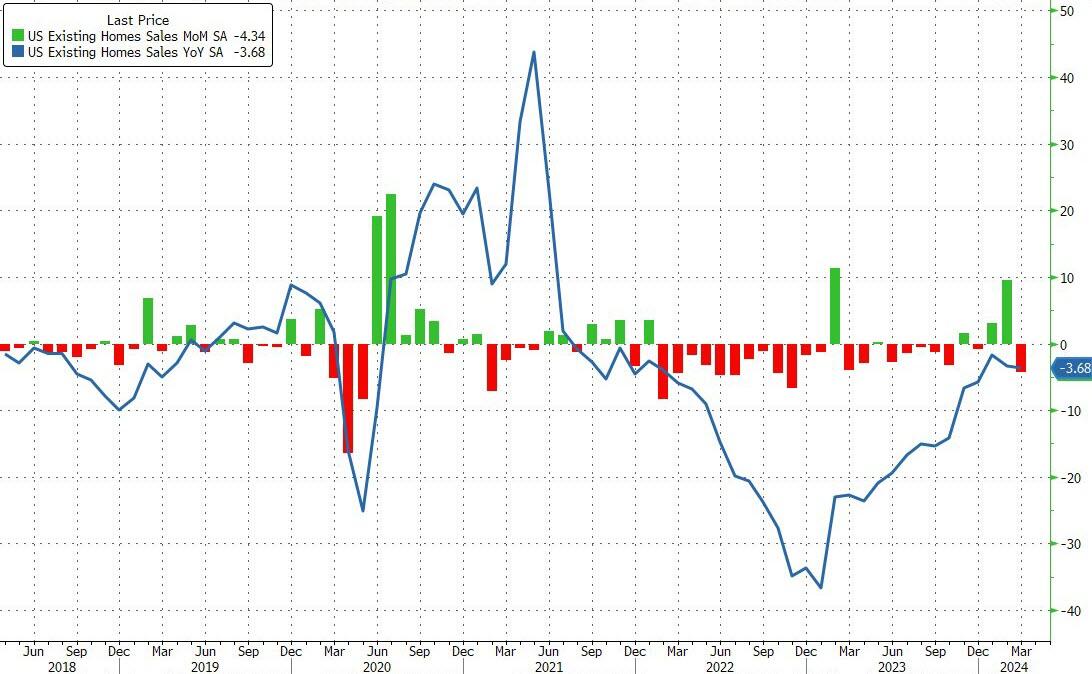
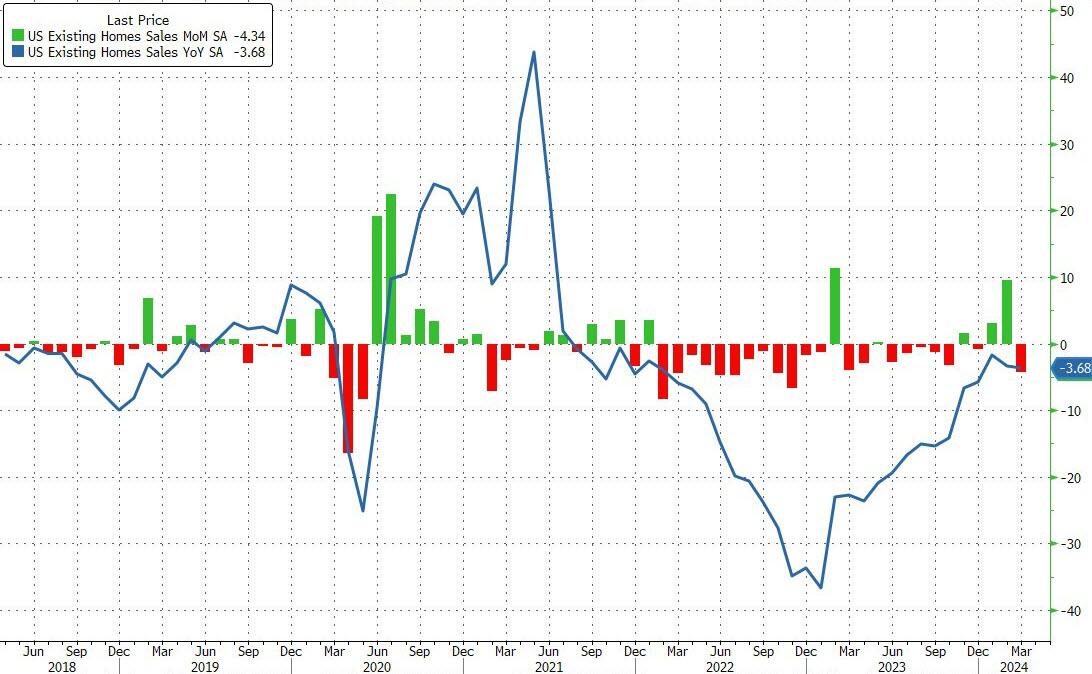
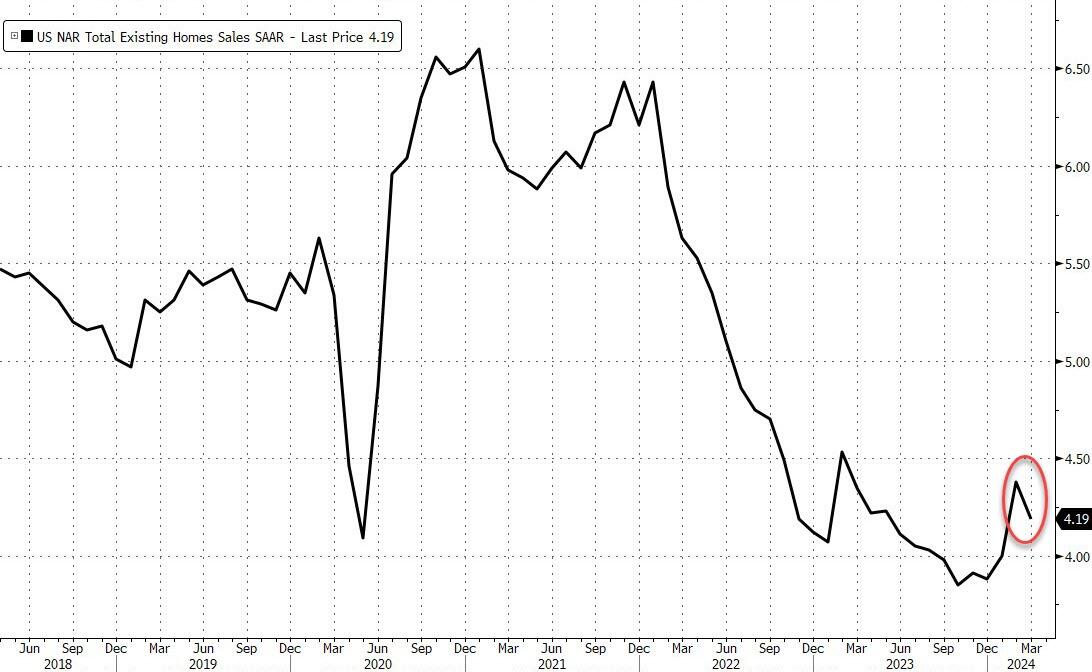
Sales were down almost 10% from a year earlier on an unadjusted basis, as sales of both single-family homes and condominiums and co-ops dropped.
Source: Bloomberg
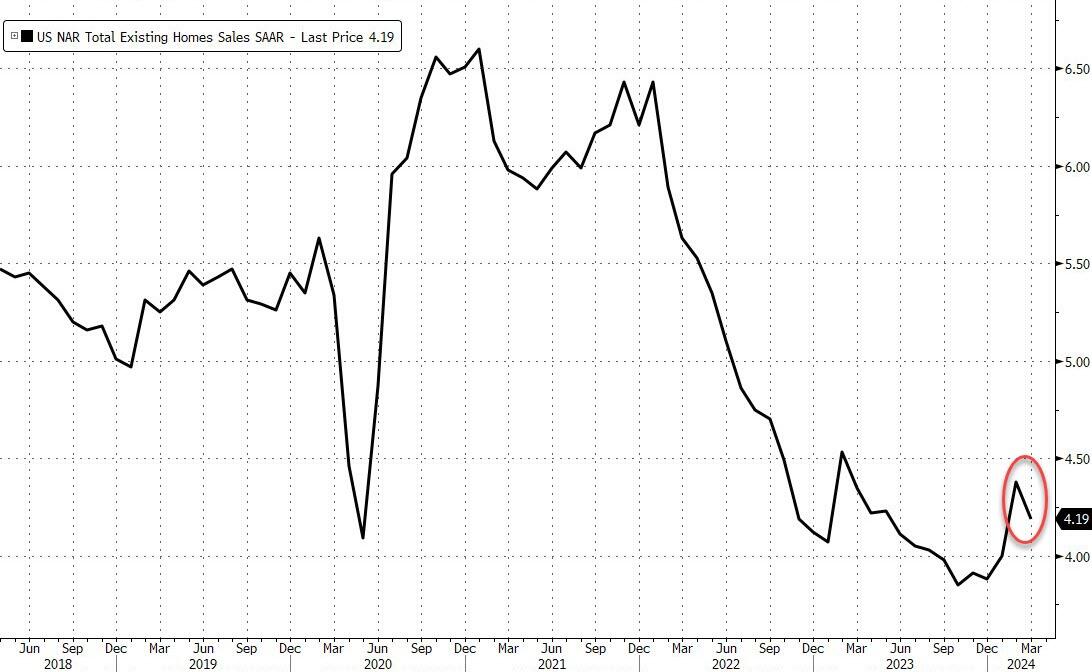
This dragged total existing home sales SAAR back down to 4.19mm…
Source: Bloomberg
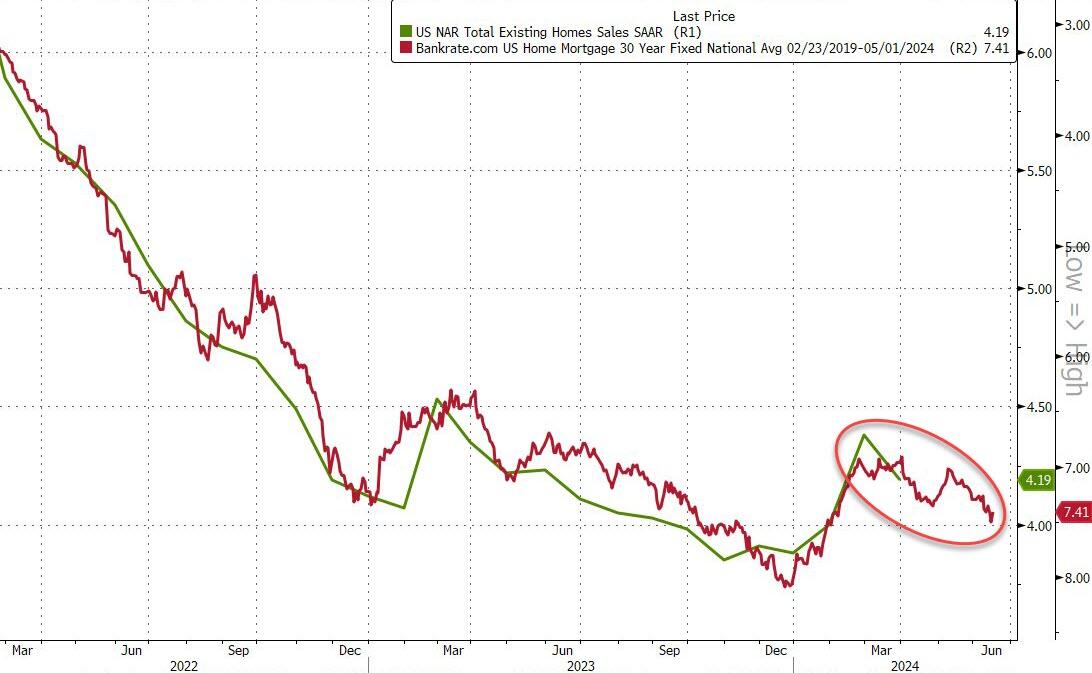
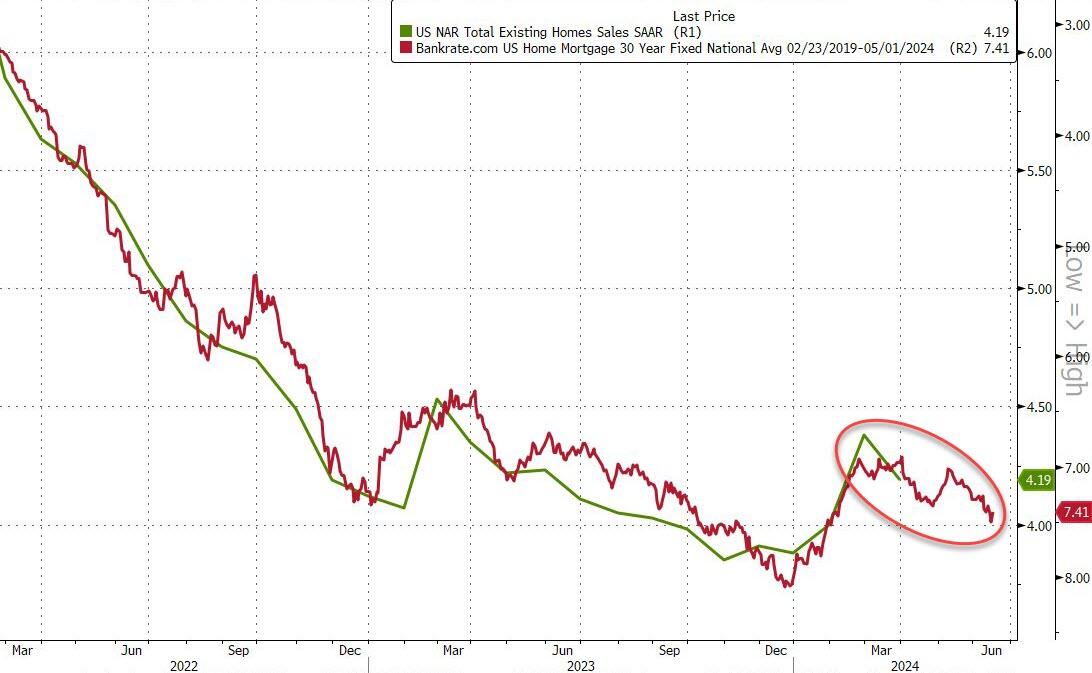
“Though rebounding from cyclical lows, home sales are stuck because interest rates have not made any major moves,” said NAR Chief Economist Lawrence Yun.
“There are nearly six million more jobs now compared to pre-COVID highs, which suggests more aspiring home buyers exist in the market.”
…and it’s about to get worse…
Source: Bloomberg
Total housing inventory registered at the end of March was 1.11 million units, up 4.7% from February and 14.4% from one year ago (970,000). Unsold inventory sits at a 3.2-month supply at the current sales pace, up from 2.9 months in February and 2.7 months in March 2023.
“More inventory is always welcomed in the current environment,” Yun said.
“It’s a great time to list with ongoing multiple offers on mid-priced properties and, overall, home prices continuing to rise.”
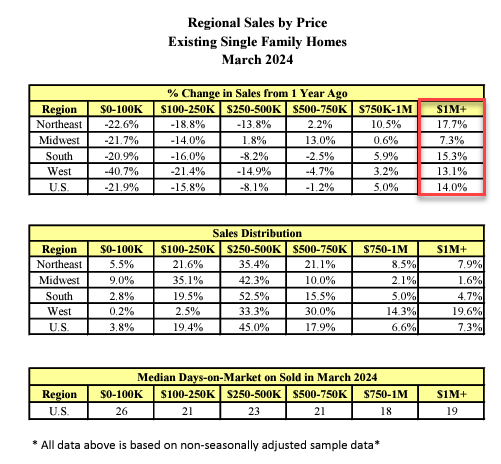
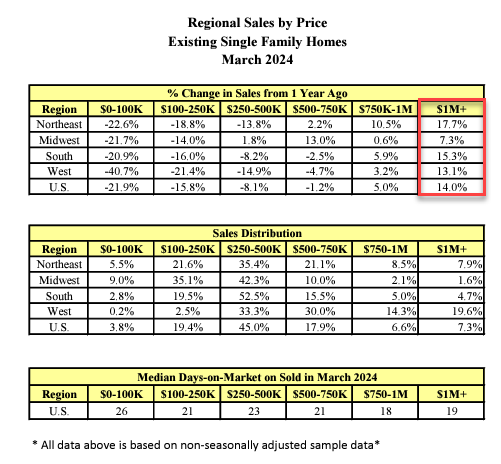
All price levels saw sales decline except $1mm+…
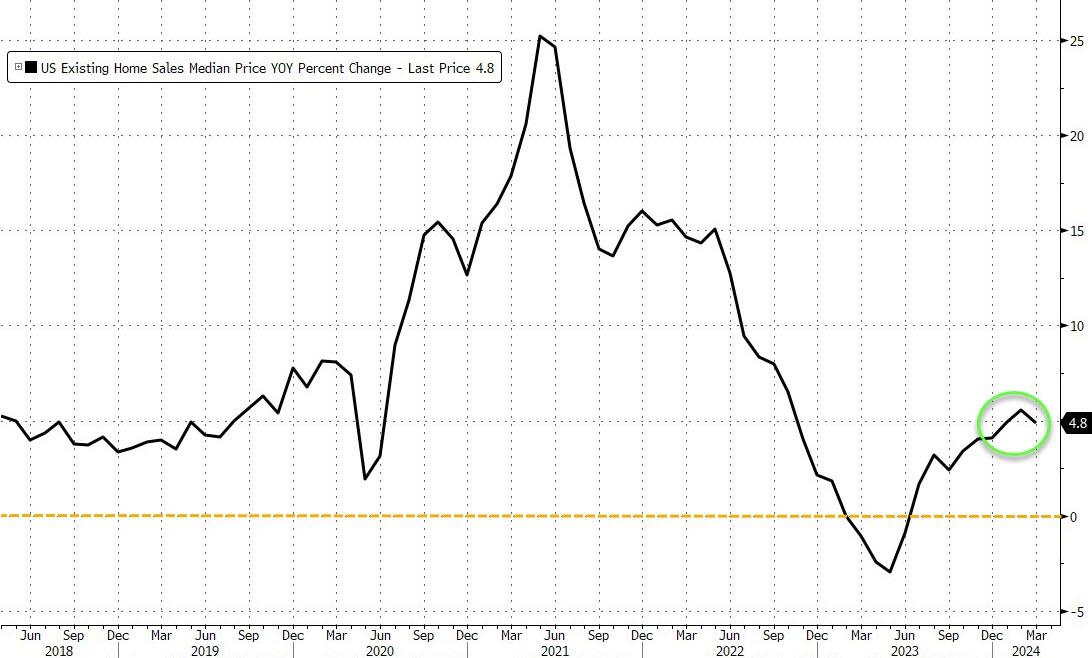
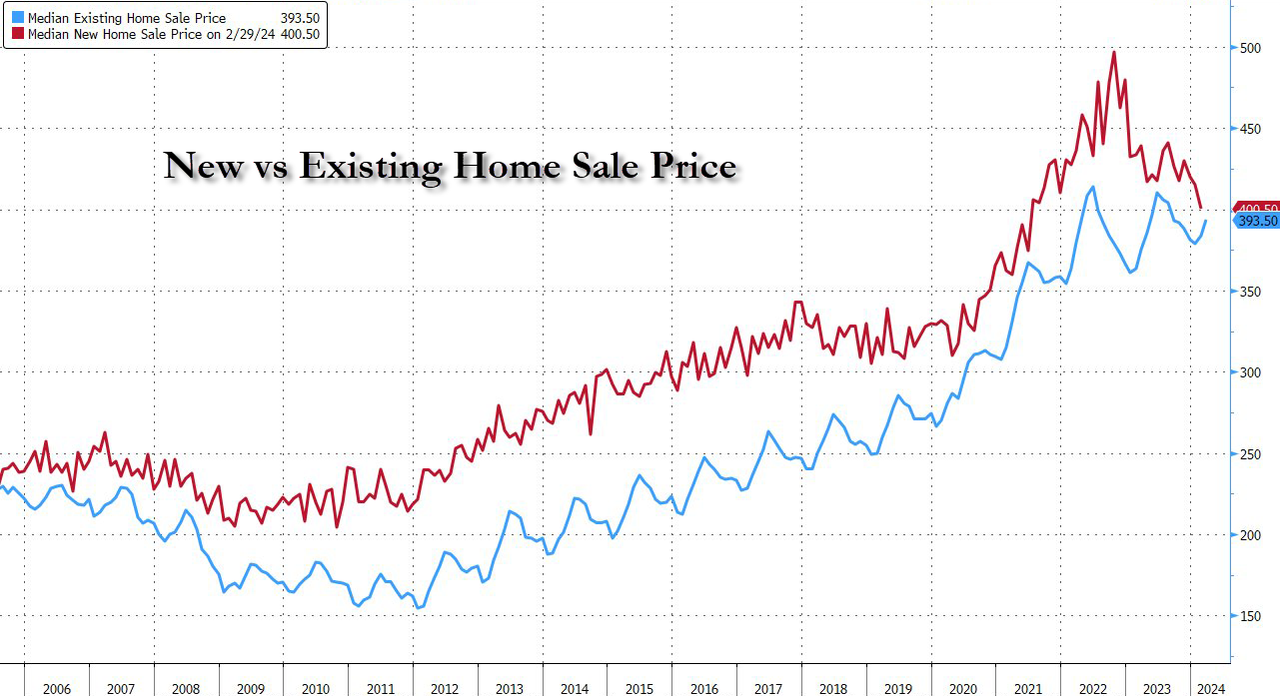
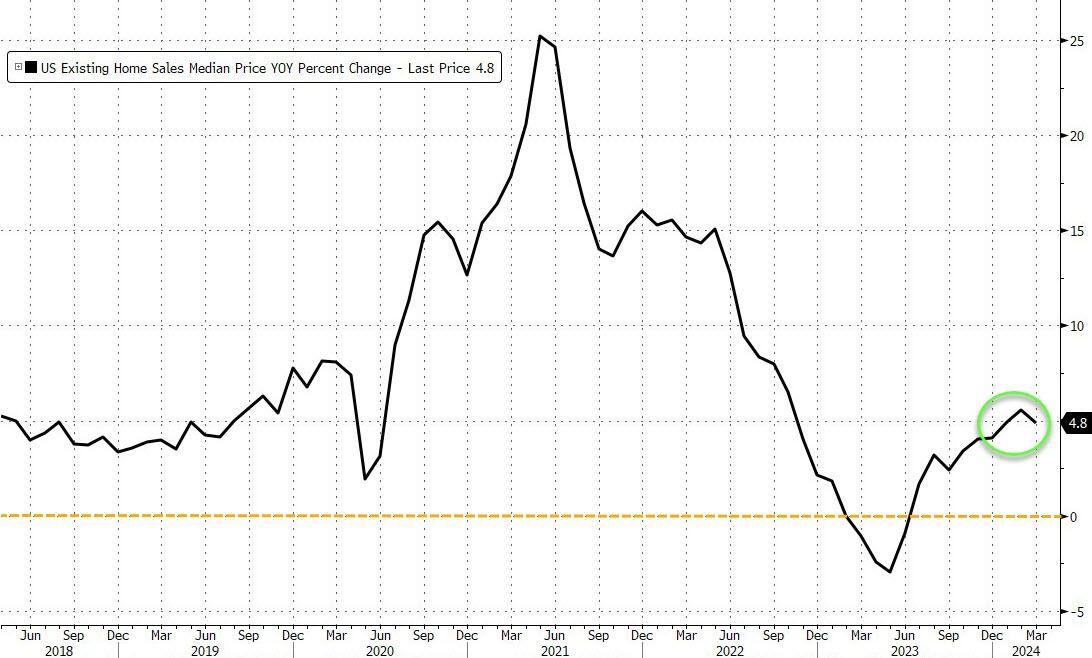
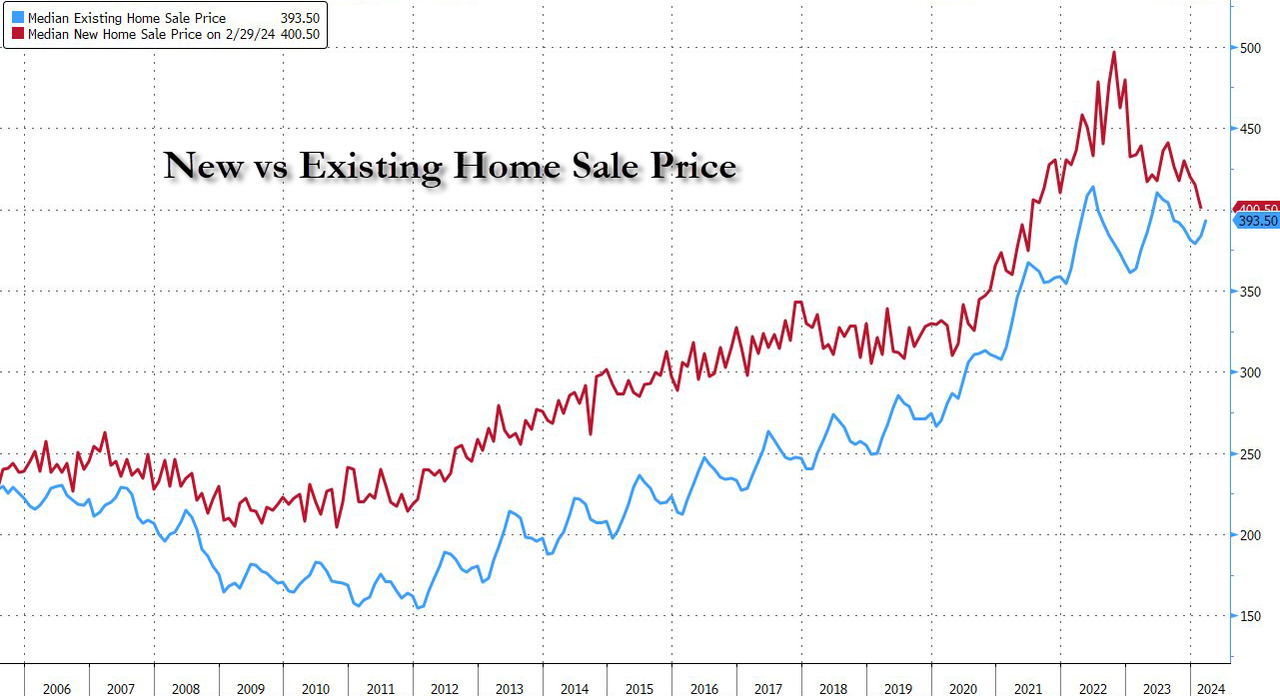
The median selling price increased 4.8% from a year ago to $393,500, the highest for any March on record.
Source: Bloomberg
…and existing home prices are about to top new home prices…
Source: Bloomberg
First-time buyers made up 32% of purchases in March, up from 26% a month earlier.
Somehow, I don’t think Biden will brag about this report.
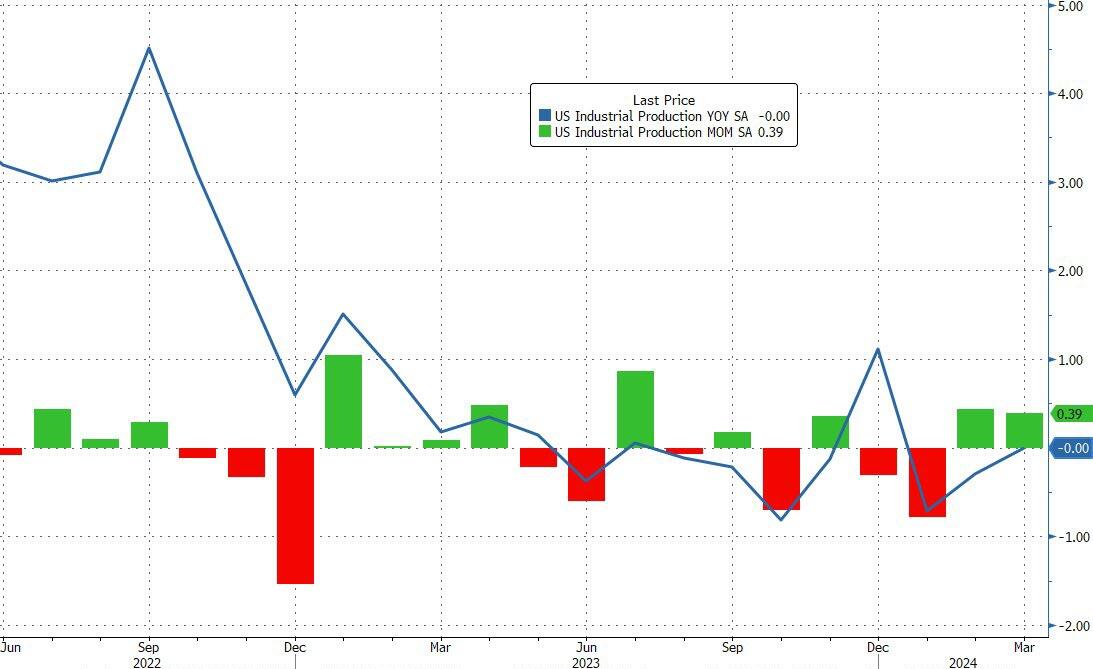
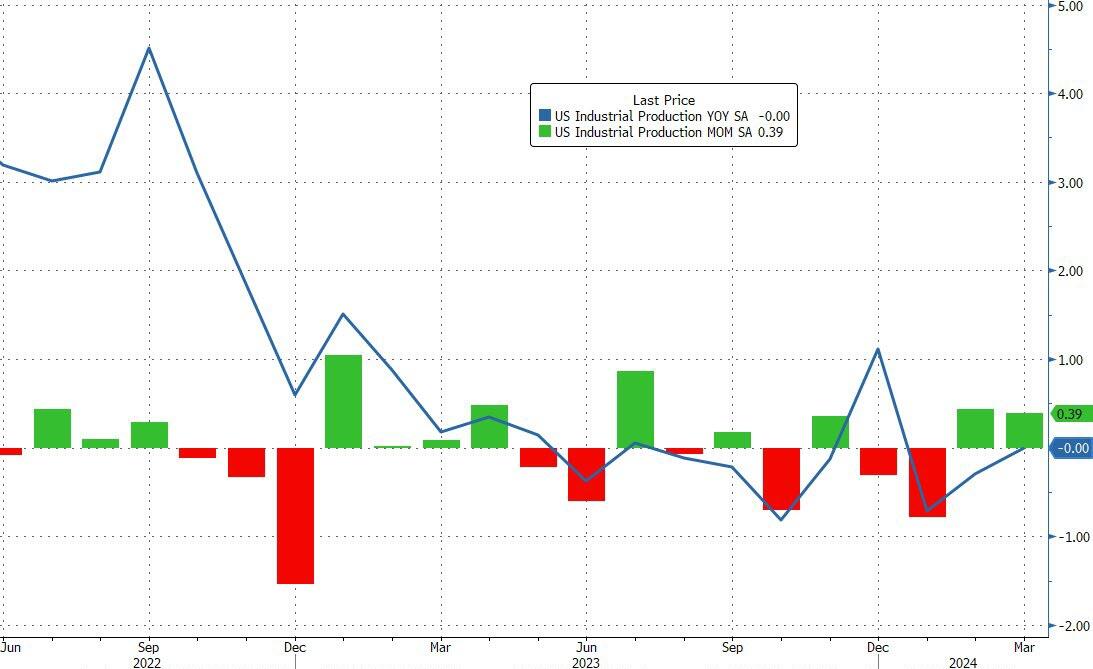
US Industrial Production rose 0.4% MoM in March – as expected – which was… wait for it… the same rise as in February after that data was revised notably higher. However, even with the revision and the subsequent rise, Industrial Production remains unchanged YoY…
Source: Bloomberg
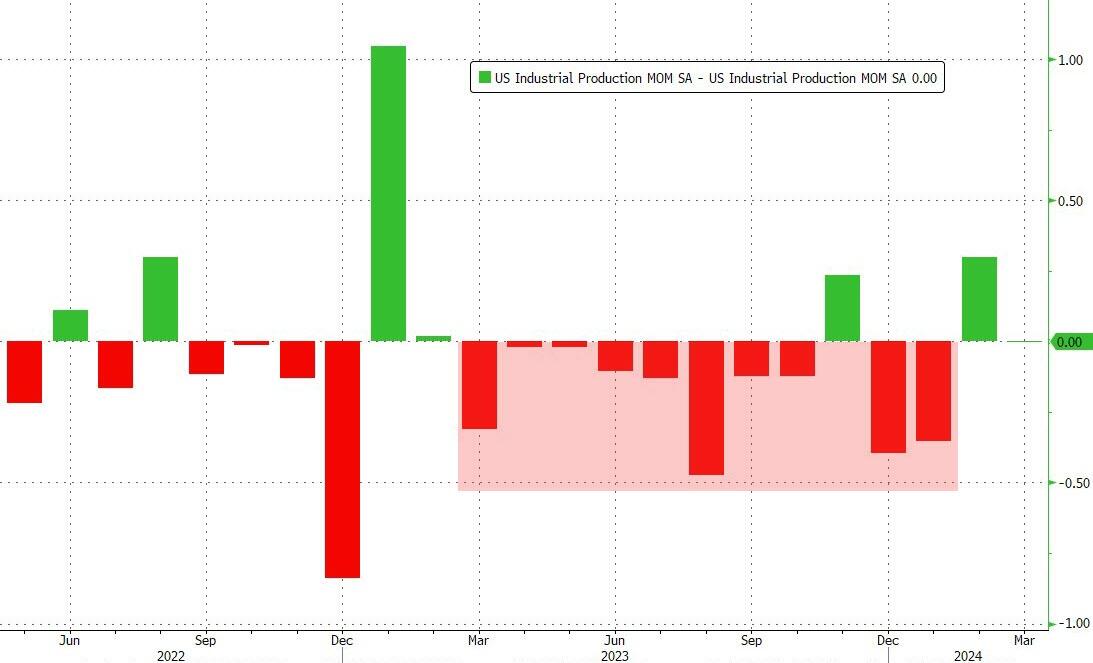
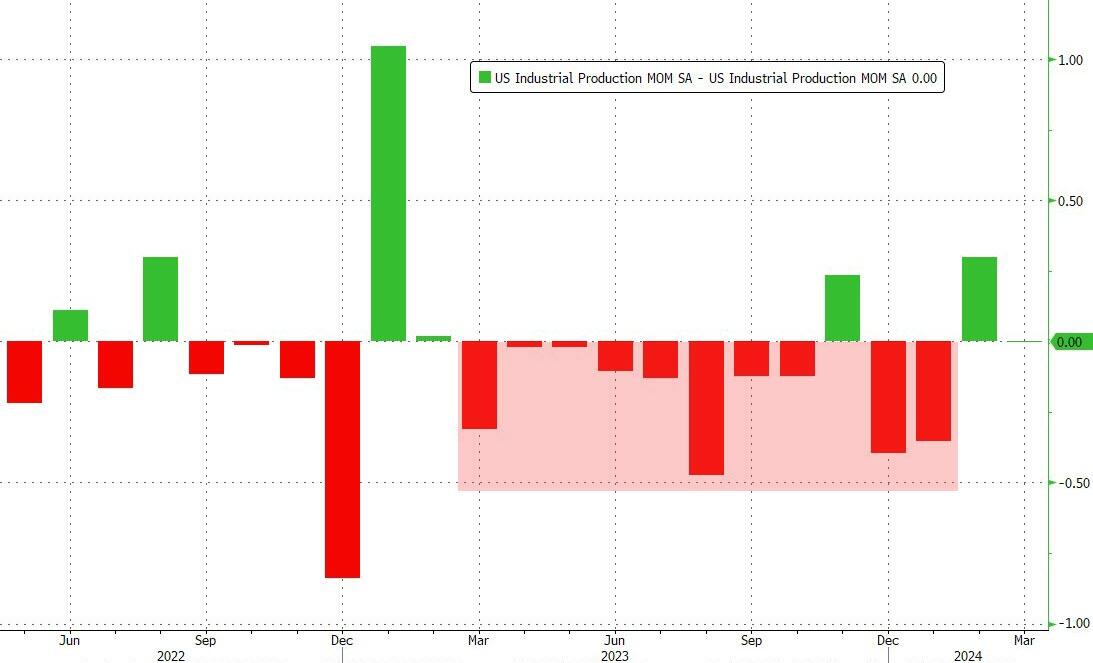
We can’t help but see the irony that after we highlighted the serial downward revisions in data last month, that all of a sudden February’s Industrial Production data is revised drastically higher…
Source: Bloomberg
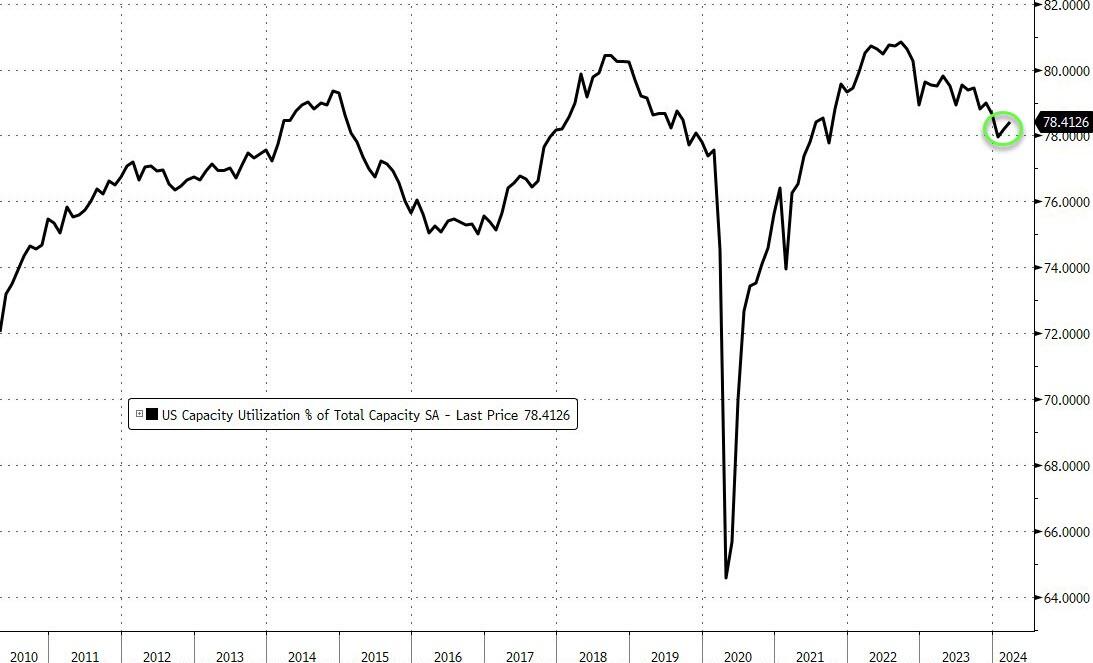
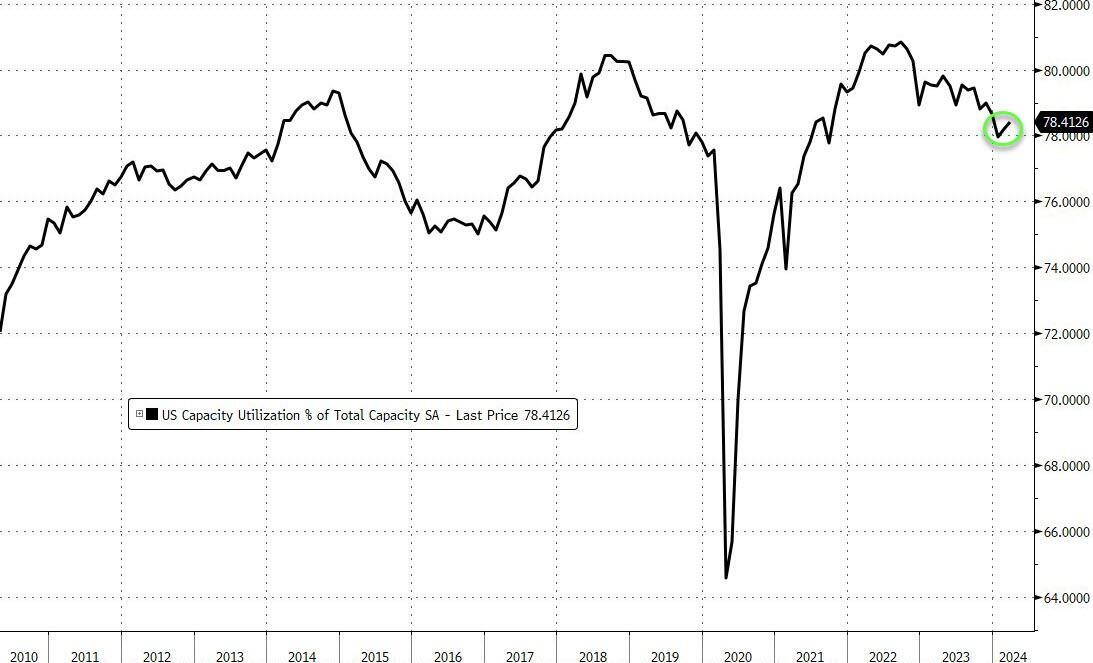
Capacity Utilization ticked modestly higher (from a downwardly revised 78.2% to 78.4% (below expectations)…
Source: Bloomberg
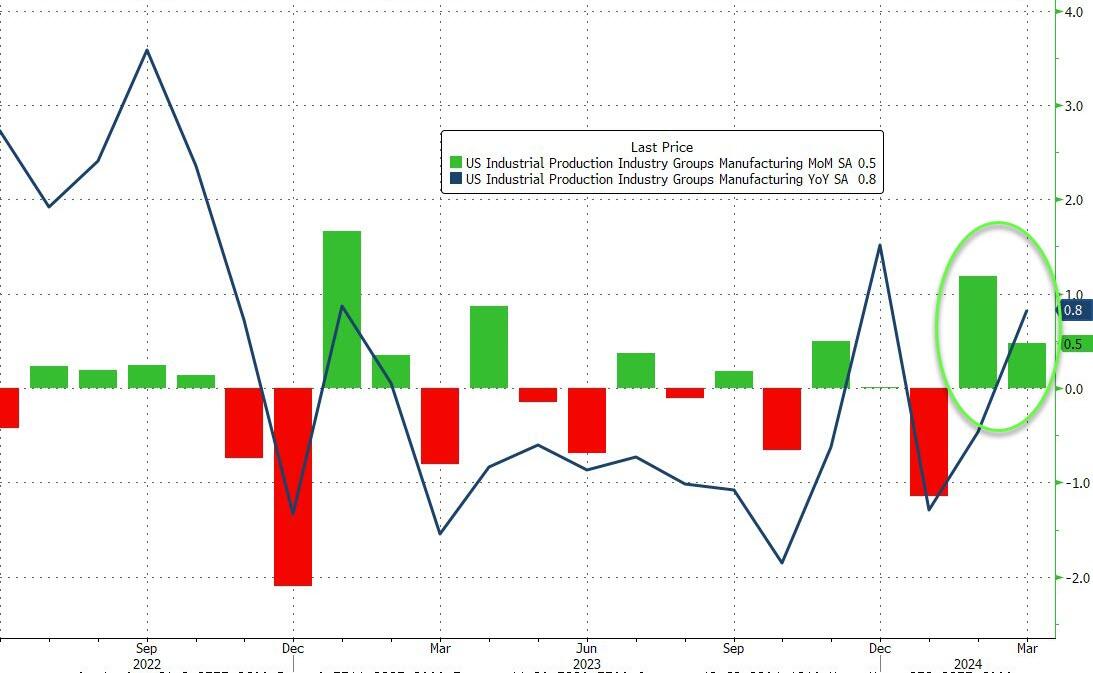
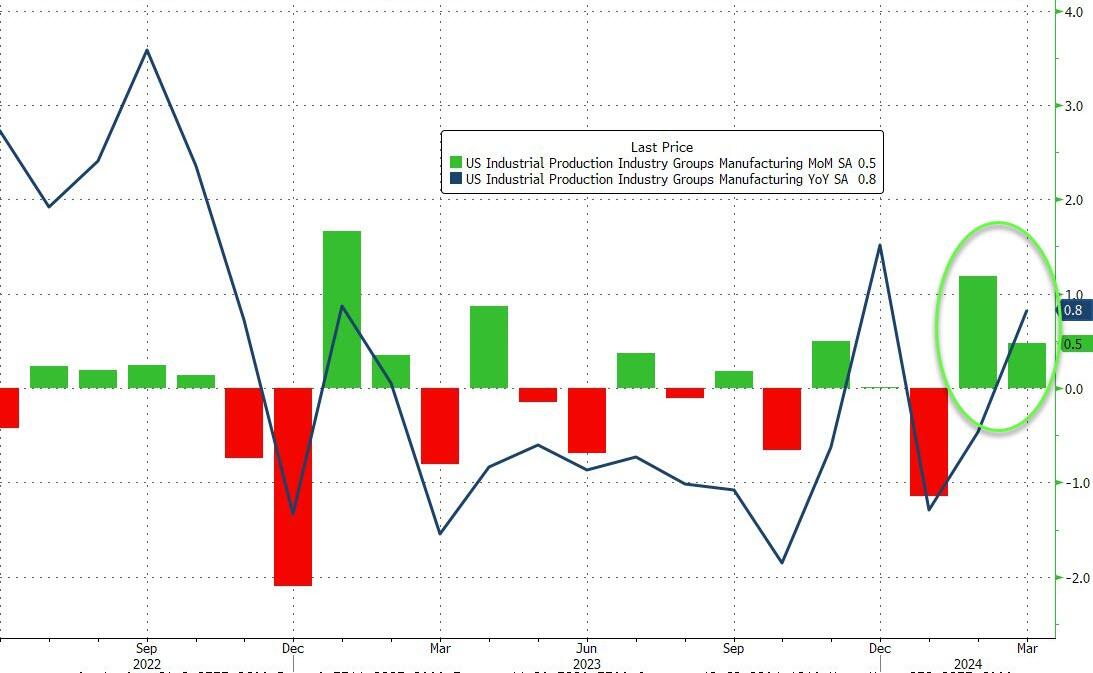
US Manufacturing also saw February’s data revised higher (from +0.8% to +1.2% MoM) and March rose 0.5% MoM (better than the 0.2% rise expected). That lifted YoY Manufacturing up by 0.8%…
Source: Bloomberg
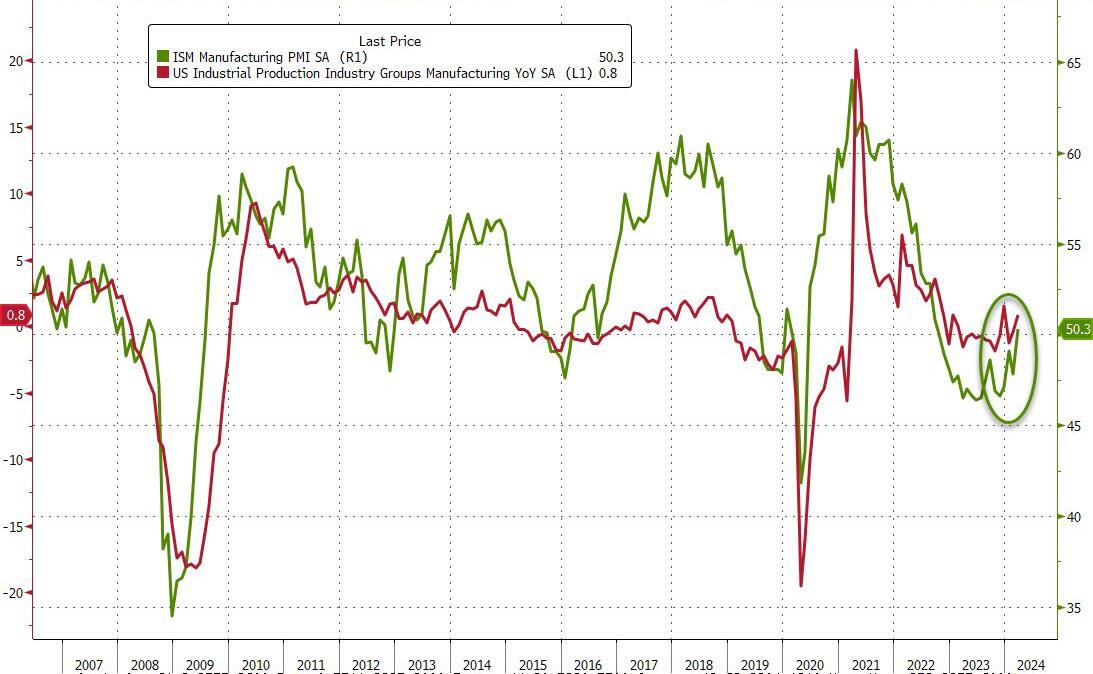
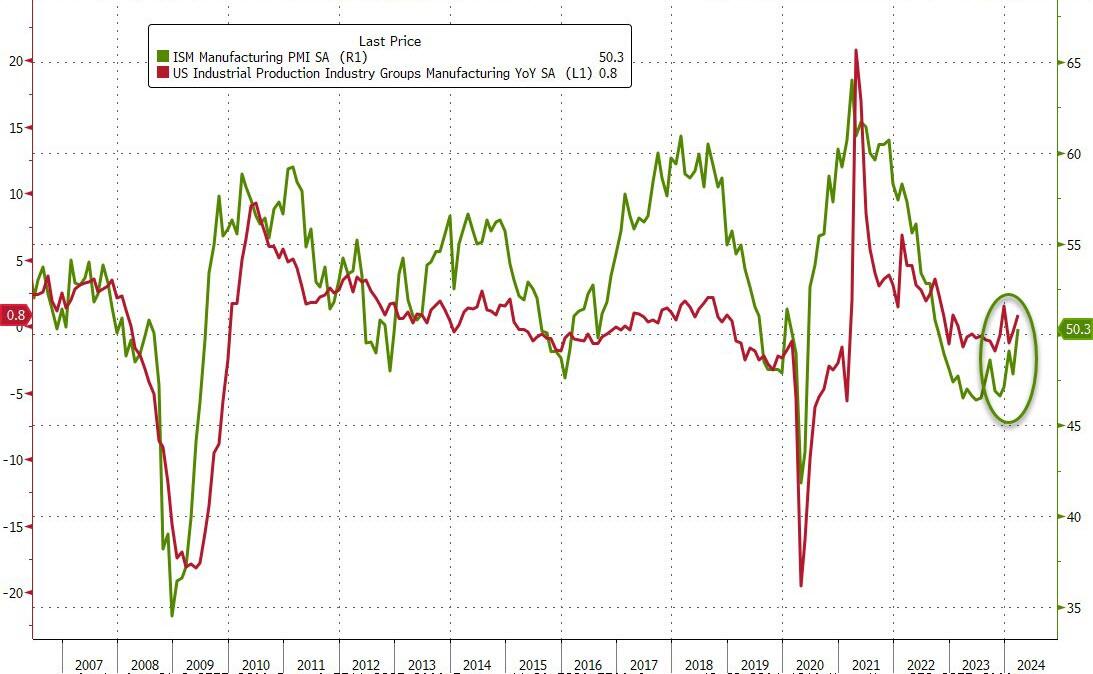
Soft and Hard manufacturing data in agreement that things are turning up…
Nothing but blue skies here for The Fed to cut rates into… not!
Joe Biden likes to sell himself as “working class Joe” or “union Joe.” The truth is anything but. He is “Washington DC insider Joe” or “big corporate Joe.”
The US mortgage 30 year rate is down slightly today to 7.30%. That is a whopping 160% increase since Biden’s Presidency began.
Mortgage rates will continue to climb as the US Treasury 10-year yield climbs.
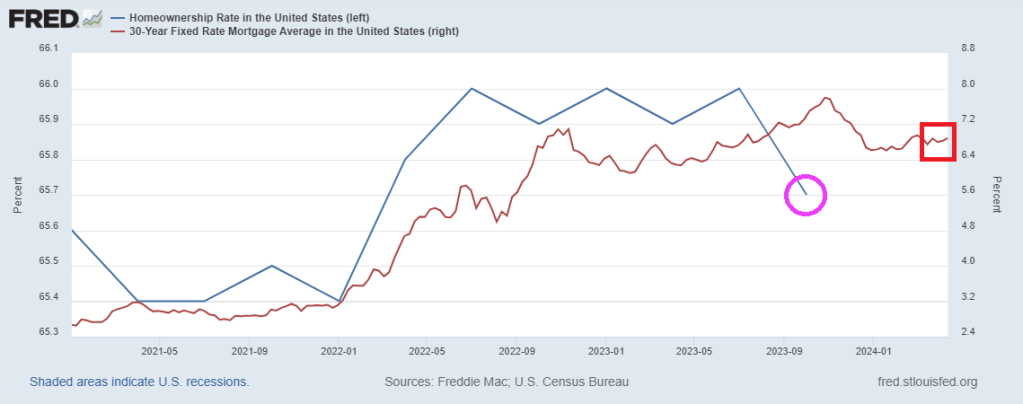
The US homeownership rate is falling as mortgage rates climb.
US CPI on trend for 4-5% at US election in November.
Source: BofA
Above 5%…?
Strong CPI raises market probability of YE25 rates above 5%.
Source: Goldman
Cyclical inflation remains too elevated
“Our measure of cyclical inflation–which should capture the impact of excess demand on prices–appears to be stuck at around 5%, which is too elevated”
Source: Safra
US alone
The US is the only economy in the G10 where the latest inflation print surprised to the upside.
Source: Goldman
200% of GDP
Under current policies, government debt outstanding will grow from 100% to 200% of GDP.
Source: Apollo
Close to $9 trillion in maturities
That’s a significant amount of government debt maturing within the next year.
Source: Apollo
Every year a deficit
OMB forecasts 5% budget deficit every year for the next 10 years.
Source: Apollo
A billion per day….is long gone
US government interest payments per day have doubled from $1bn per day before the pandemic to almost $2bn per day in 2023.
Source: Apollo
Biggest Story of 2020s…Ugly End of 40-year Bond Bull
Chart shows long-term US government bond (15+ year) rolling 10-year annualized returns, %.
Source: Flow Show
Highest yields in 15 years
The intermediate part of the yield curve still offers the highest yields in over fifteen years.
Source: Piper Sandler
Finally, electricity costs keeps rising, ESPECIALLY with the misnamed Inflation Reduction Act (IRA). The real name of the IRA should have been the Large Green Donor Increase Act (LGDIA).
Joe Biden, his Administration, and The Federal Reserve are really “The Alligator People.” Despite what they tell you, they have small brains (particularly Biden) and are hyperfocused on spending.
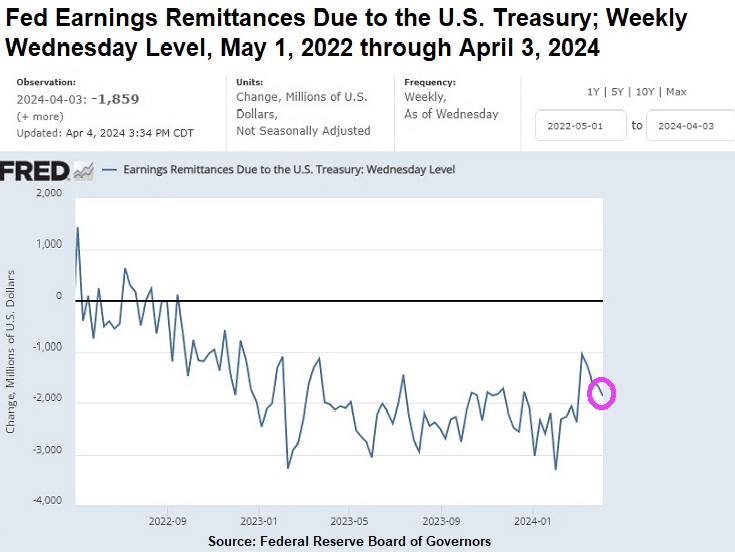
A good example comes from “Wall Street On Parade” where they show that The Federal Reserve is still paying BILLIONS to US Treasury in the form of remittances (losses). While at the same time, paying the mega banks on Wall Street high interest loans.
As of April 3 of this year, the Federal Reserve (Fed) has racked up $161 billion in accumulated losses. We’re not talking about unrealized losses on the underwater debt securities the Fed holds on its balance sheet, which it does not mark to market. We’re talking about real cash losses it is experiencing from earning approximately 2 percent interest on the $6.97 trillion of debt securities it holds on its balance sheet from its Quantitative Easing (QE) operations while it continues to pay out 5.4 percent interest to the mega banks on Wall Street (and other Fed member banks) for the reserves they hold with the Fed; 5.3 percent interest it pays on reverse repo operations with the Fed; and a whopping 6 percent dividend to member shareholder banks with assets of $10 billion or less and the lesser of 6 percent or the yield on the 10-year Treasury note at the most recent auction prior to the dividend payment to banks with assets larger than $10 billion. (This morning the 10-year Treasury is yielding 4.41 percent.)
Operating losses of this magnitude are unprecedented at the of Fed, which was created in 1913. In a press release dated March 26, the Fed stated this: “The Reserve Banks’ 2023 sum total of expenses exceeded earnings by $114.3 billion.”
As the chart above indicates, the Fed’s ongoing weekly losses have ranged from a high of $3.3 billion for the week ending Wednesday, January 31, 2024, to $1.86 billion for the most recent week ending Wednesday, April 3, 2024.
American taxpayers have good reason to sit up and pay attention to the Fed’s giant and ongoing losses. That’s because when the Fed is operating in the green, as it was on an annual basis for 106 years from 1916 through 2022, the Fed, by law, turns over excess earnings to the U.S. Treasury – thus reducing the amount the U.S. government has to borrow by issuing Treasury debt securities. According to Fed data, between 2011 and 2021, the Fed’s excess earnings paid to the U.S. Treasury totaled more than $920 billion.
WHO pays for the student loan forgiveness? It just doesn’t vanish, it is transferred to taxpayers. Alligators like Alexandria Ocasio Cortez going on talk shows to argue the benefits of being free from financial obligations that student voluntarily agreed to. Say, can AOC get my mortgage forgiven?? Just kidding. Now those same students can borrow additional money to get MBA degrees with the expectation that the student loan is “free money.”
Yes, Biden is acting recklessly (no surprise). Here is a picture of King Gator, Joe Biden.
The Biden Administration and The Federal Reserve ARE the alligator people. Except these gators are hungry for your money and votes constantly.
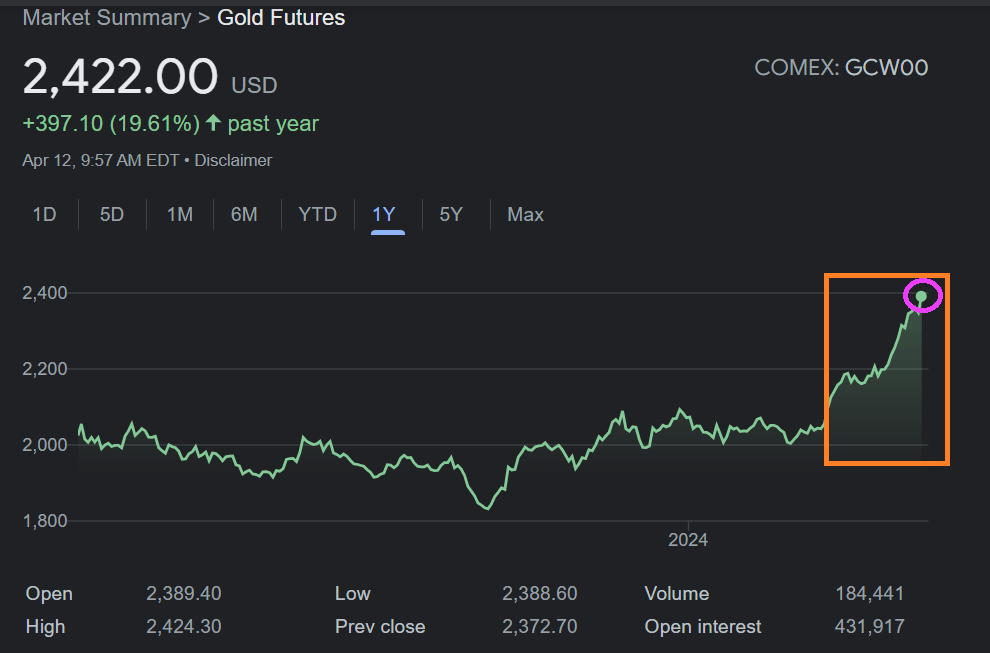
Gold futures prices are soaring and are at $2,422.00. Gold futures prices are up 19.61% over the past year.
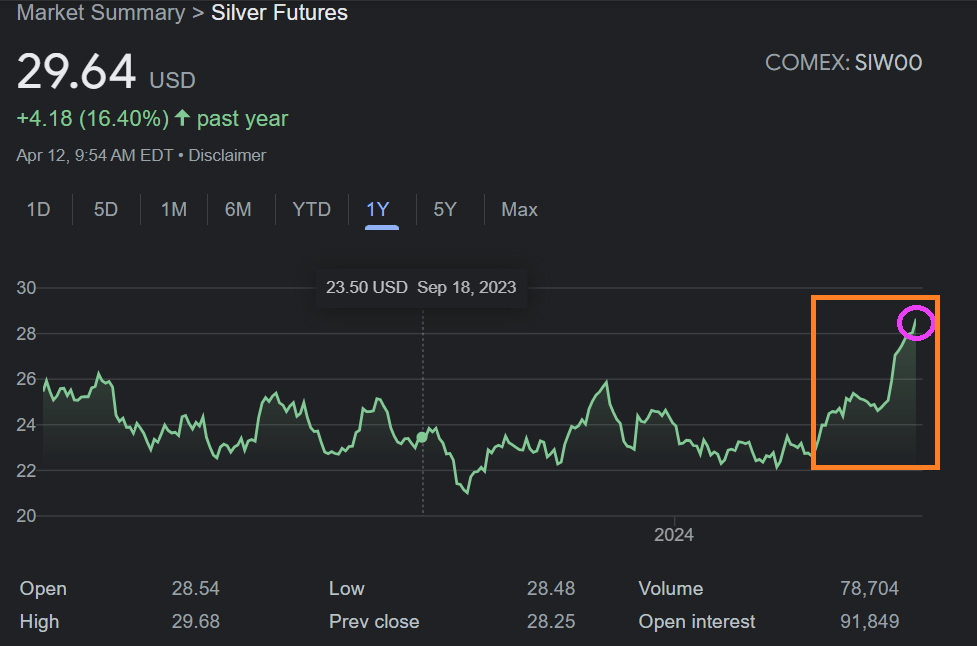
Silver futures prices are also soaring and are at $29.64. Silver futures prices are up 16.40% over the past year.
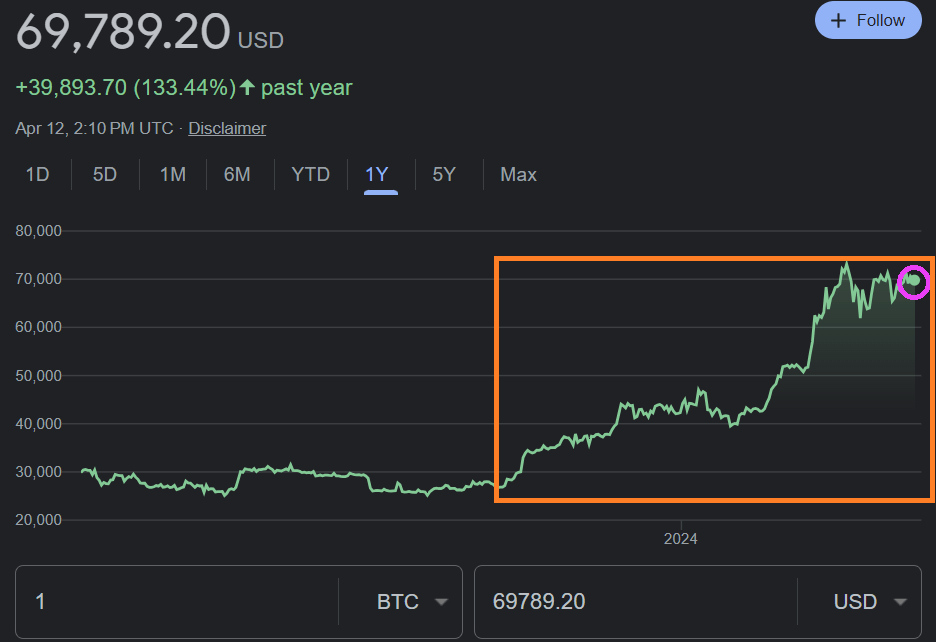
Bitcoin is almost at $70,000 and is up 133.44% over the past year.
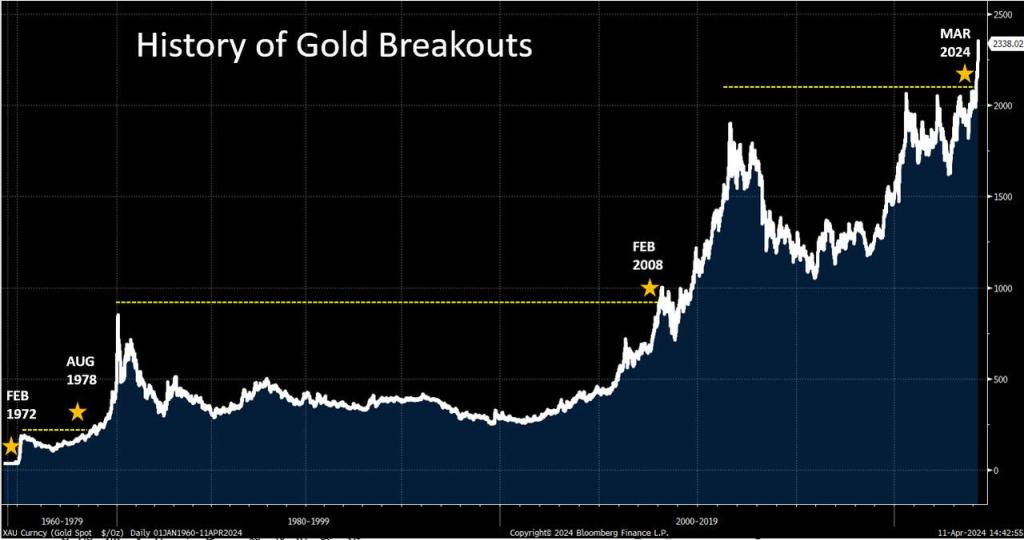
Returning to gold, we are seeing another gold breakout, like the breakout in 2008.
Even central banks are loading up on gold, silver, and cryptos. Why? Primarily fear of US reckless budgets and exploding debts/deficits (don’t listen to Biden talk about how “he” reduced deficits and debt (both have risen to dangerous levels under he inattentive eyes).
However, calming the jangled nerves of pension funds is that the S&P 500 stock market index is up 26.04% over the past year.
Overall prices are up by 19.4% since Biden took office.
Of course, the S&P 500 is not sustainable given that it has been driven by excessive spending by the Biden Adminstration coupled with still massive monetary stimulus from The Federal Reserve.
In summary, gold, silver and cryptos are rising on FEAR! Of Biden, Congress and The Fed.
We are living in the USA where corruption, favoritism, open borders and an out-of-control Federal budget and debt are destroying this once great nation.
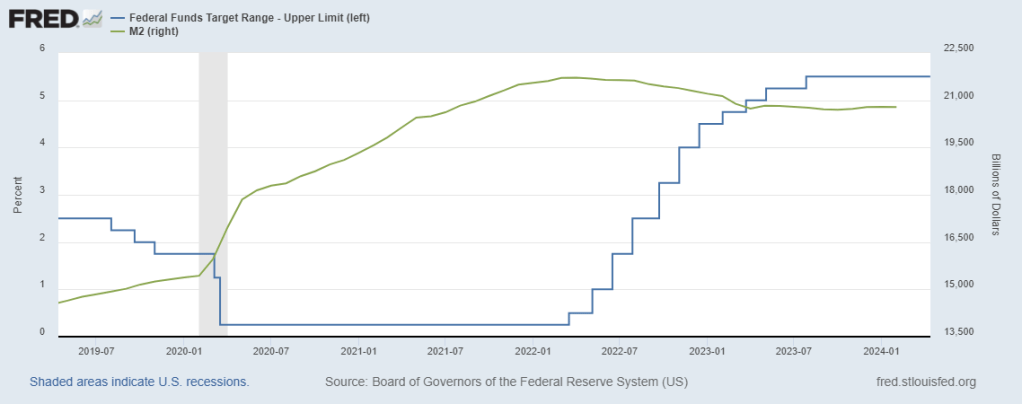
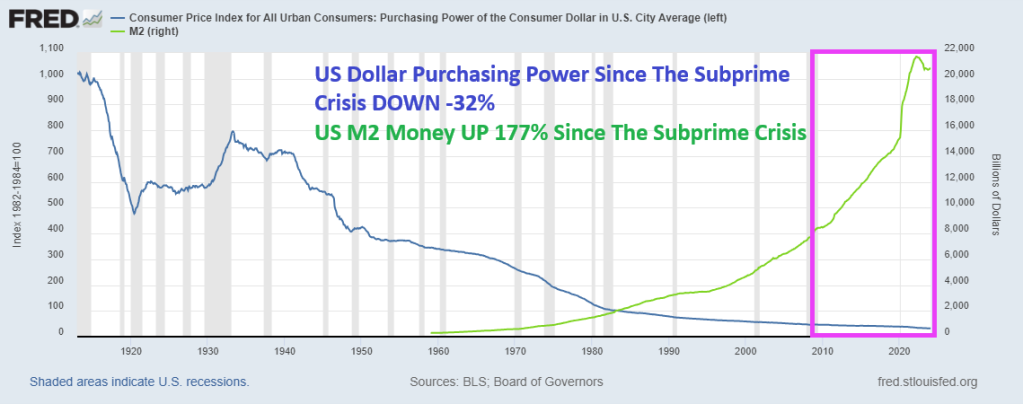
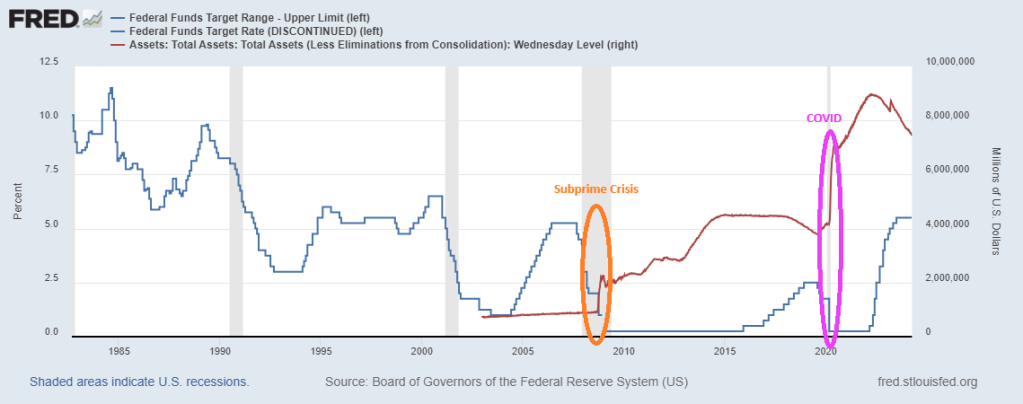
Former Kansas City Fed President Thomas M. Hoenig was absolutely right when he said recently that The Federal Reserve panders to Wall Street, Congress and special interest groups, prioritizing immediate relief over financial stability. Bernanke’s zero-interest rate policies (ZIRP) and Quantitative Easing (QE) were short-term fixes that never went away. Indeed, since the subprime mortgage crisis of 2008-2009, US Dollar purchasing power is DOWN -32% and M2 Money is up a staggering 177%. While Yellen stuck with zero-interest policies until Trump was elected, then raised The Fed Funds Target Rate 8 times. Yellen only raised the target rate once under Obama. Clearly playing political favoritism.
The Federal Reserve’s lack of transparency comes amidst reports that countries are removing their gold and other assets from the U.S. in the wake of the unprecedented Western sanctions imposed on Russia over its invasion of Ukraine. According to a 2023 Invesco survey, a “substantial percentage” of central banks expressed concern about how the U.S. and its allies froze nearly half of Russia’s $650 billion gold and forex reserves.Headline USA filed a FOIA request with the Fed for records reflecting how much gold the Federal Reserve Bank of New York currently holds in its vault, as well as records reflecting the ownership stake that each of FRBNY’s central bank/government clients have in that gold. The FOIA request also sought records about the Fed’s gold holdings prior to Russia’s February 2022 invasion of Ukraine. However, the Federal Reserve denied the FOIA request on Wednesday.
It influences the price of nearly everything, as well as the availability of jobs, the stability of our banking system, and the purchasing power of our money.
When the Fed Chair speaks, the entire world stops to listen.
But the average person has a poor understanding of how this colossally important entity operates. Or even why it exists.
And after a series of asset price bubbles — which some argue we’re in another one now — a chorus skeptical of the Fed’s actions has emerged.
So today we’re doing our best to shine as bright a light as possible on the Fed: how & why it operates, the good & as well as the shortcomings of its actions to date, what direction its policies are likely to take from here, and how all of this impacts the households of regular people like you and me.
Here are my top takeaways from from a speech by former KC Fed President Thomas Hoenig:
Dr Hoenig admits the Federal Reserve has experienced substantial “mission creep” since its creation as a lender of last resort. Its track record is very much “mixed” in terms of delivering on the intent of its policies. In Dr. Hoenig’s opinion, its efforts to add stability sometimes instead only create more instability.
While very critical of the Fed’s QE and ZIRP policies in the wake of the GFC, and more recently in the $trillions in monetary & fiscal stimulus unleashed post-COVID, Dr Hoenig thinks current Fed policy is “about right”. Though he expects the Fed to come under serious pressure soon as ebbing liquidity allows recessionary forces to build. He thinks the Fed will need to make an important decision within the coming year: return to QE and re-flame inflation, or allow a recession to occur.
Dr Hoenig criticizes the Federal Reserve for pandering to various interests, noting that short-term thinking and pressures from Wall Street, Congress, and interest groups often lead to decisions that prioritize immediate relief over long-term stability — a sort of “We’ll act now for optics sake and hopefully figure things out later”
In Dr Hoenig’s opinion, our fiscal policy is a runaway disaster. He criticizes both political parties of Congress for their roles in the cycle of ever-increasing deficits. Democrats advocate increased spending and tax hikes, while Republicans aim to keep taxes low but fail to curb spending. He warns of dire long-term consequences for future generations due to this impasse.
Dr Hoenig is very worried about the current stability of the banking system (and this from a former Direct of the FDIC!). He advocates for essential reforms to address government spending, prioritize essential areas without relying on future borrowed funds or inflationary measures, and communicate transparently with the public. He stresses the importance of reducing debt growth substantially below national income growth to avoid a full-blown crisis scenario in the future.
Dr Hoenig predicts the purchasing power of the US dollar (and other world fiat currencies) will continue to decline due to current policies and the lack of a “discipline” to money creation. Until such a discipline is restored (perhaps a return to some sort of hard backing of the currency), the dollar’s fall in purchasing power won’t abate.
Dr Hoenig suggests investing time in reading history and biographies as a valuable way to learn about leadership and gain insights into what strategies works and which don’t.
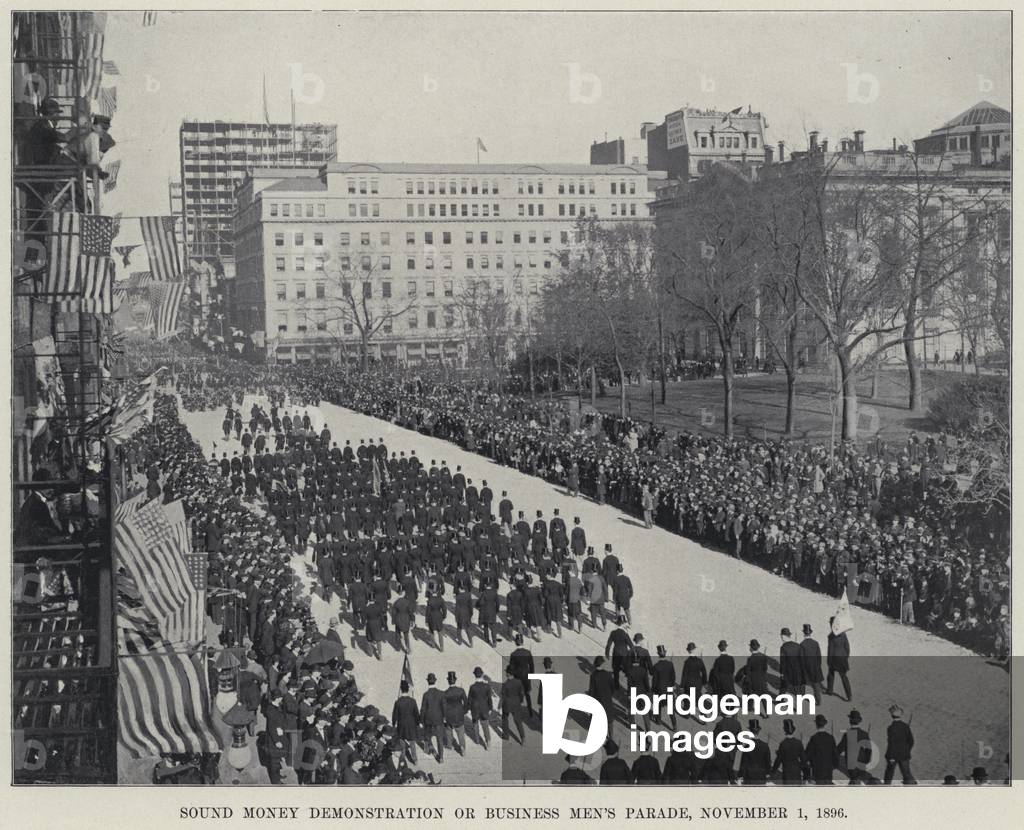
Here is the “Sound Money Parade” in 1896. By the aftermath of the subprime crisis, Janet Yellen (1993-2020) adopted the UNSOUND Money Fest, an orgy of printing and charging near zero interest rates. Powell in 2021 is ever-so-slowly unwinding The Fed’s balance sheet, but Powell has raised The Target Rate to its highest level since 1998 to fight inflation caused by Biden’s policies.
Combine The Fed not telling us how much gold they hold and their overprinting problems since 2008, and you can see why investors are turning to gold and silver and crypto currencies. The adoption of Central Bank Digital Currency (CBDC) is a step towards financial collapse.
Here is a parade you will NEVER see in Washington DC. A Sound Money Parade!
Powell is beginning to act like a sound money fan, but he still is taking his sweet time shriking the balance sheet.
I am thinking of fleeing to Lilliehammer Normay like Frank Tagliano.
Like last month, today’s jobs report for March is better than Februrary’s miracle report, but has some glaring bad news that the Administration and slobbering media will ignore. Now you know why I no longer appear on CNBC, CNN or Fox Business anymore.
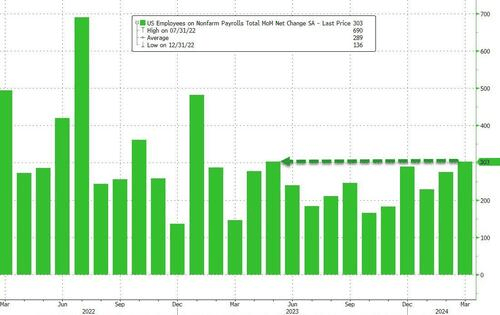
Let’s start with the good news! The BLS reported that in March, the US added a whopping 303K jobs, tied for the highest since Jan 2023!
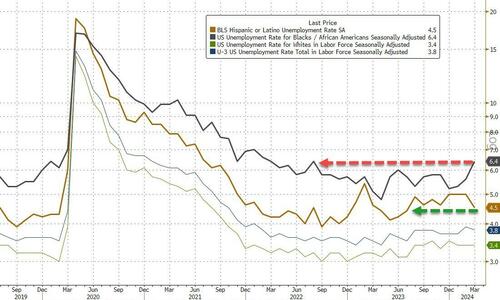
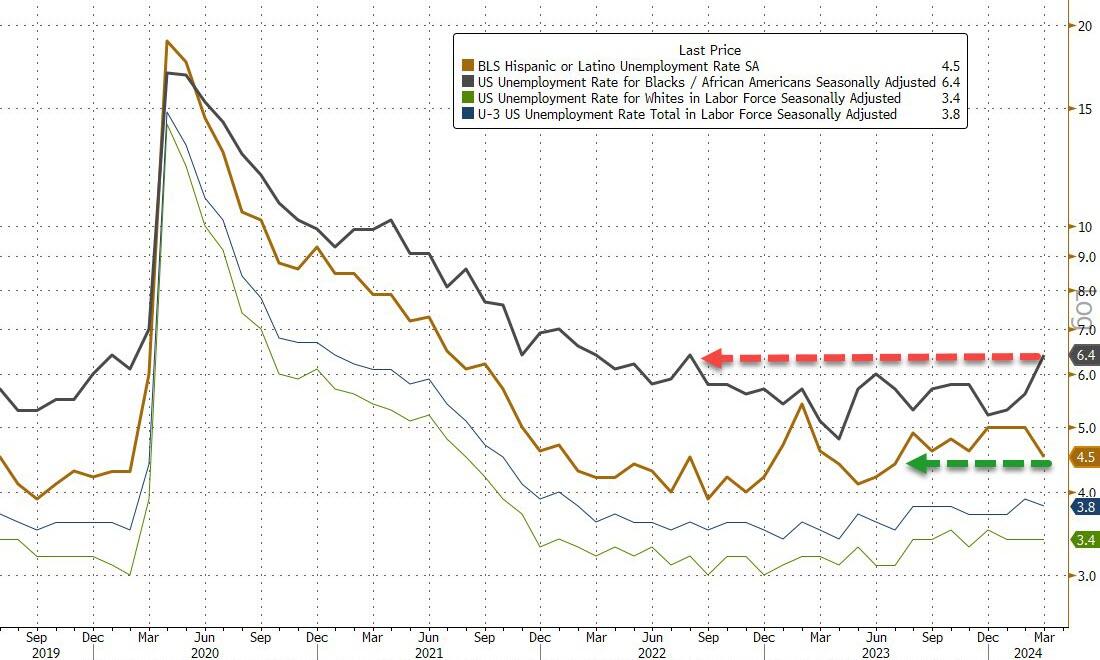
Turning our attention to the unemployment rate, it unexpectedly dipped again, dropping to 3.8%, from 3.9%, in line with estimates, as the number of unemployed workers dipped modestly from 6.458 million to 6.429 million while the number of employed workers rose by almost half a million workers; the unemployment rate for Blacks (6.4 percent) increased in March to the highest level in almost two years, while the rates for Asians (2.5 percent) and Hispanics (4.5 percent) decreased. The jobless rates for adult men (3.3 percent), adult women (3.6 percent), teenagers (12.6 percent), and Whites (3.4 percent) showed little or no change over the month.
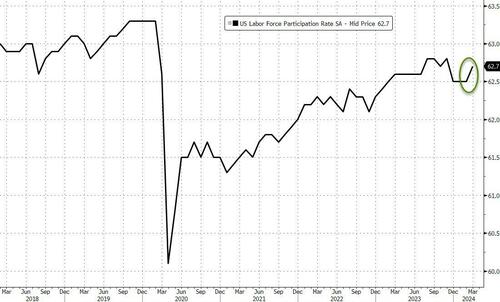
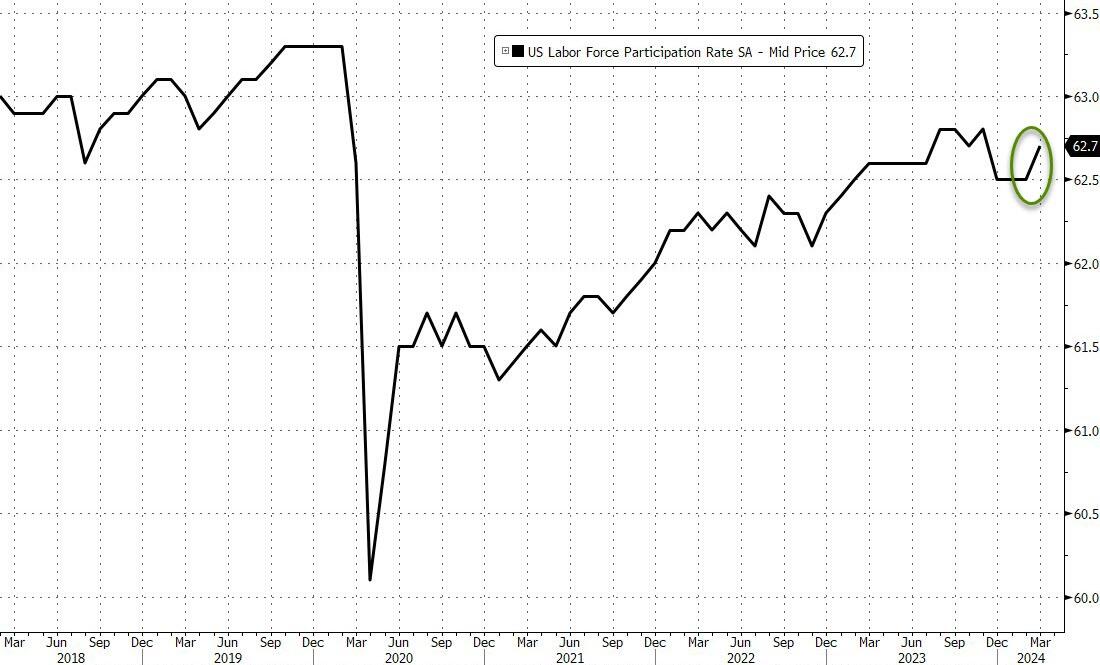
In contrast, the participation rate rose from 62.5% to 62.7%, above the 62.6% expected, as the overall civilian labor force increased slightly less than the number of employed people.
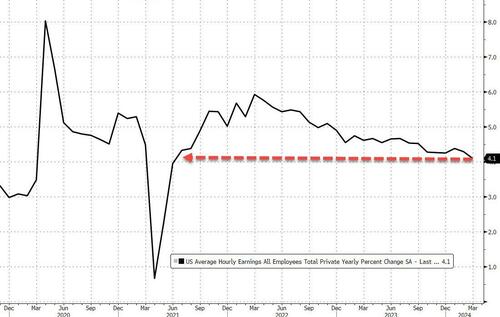
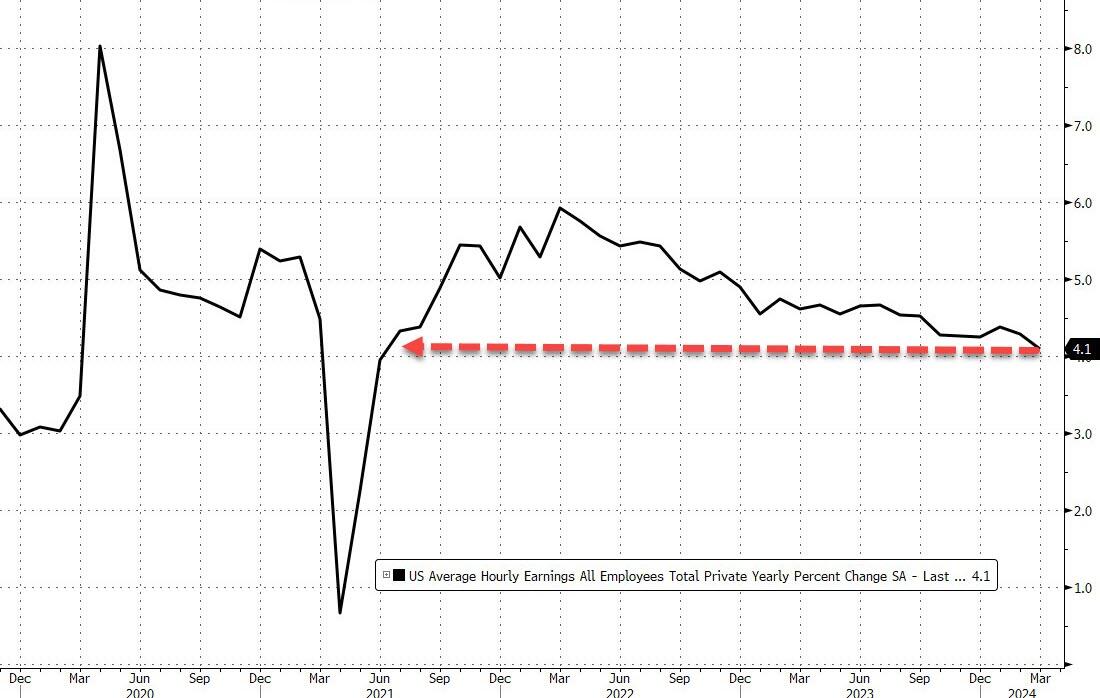
Now for the not-so-good news. The average hourly earnings came in as expected, rising 0.3% MoM, up from last month’s upward revised 0.2% sequential increase (revised from 0.1%), On an annual basis, the hourly earnings rose 4.1%, as expected, and down from 4.3%. This was the lowest print in almost three years: the last time wages rose by this much was the summer of 2021.
Now for the bad news.
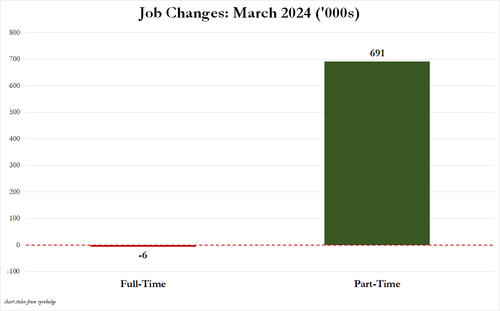
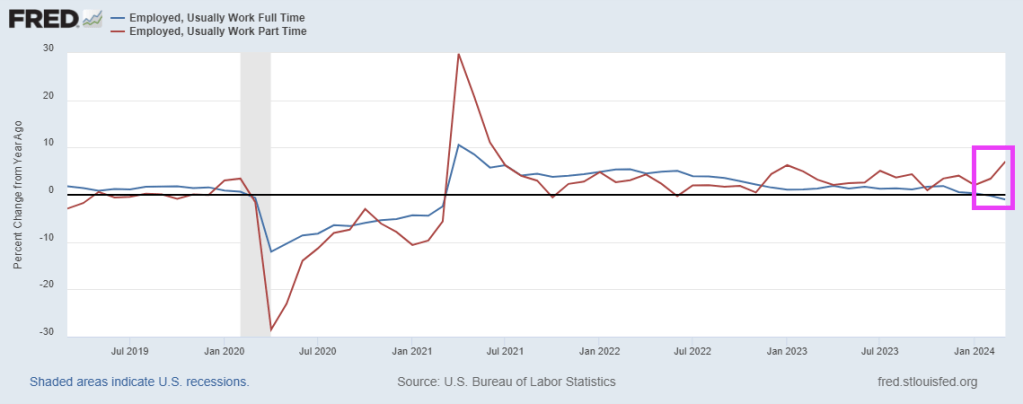
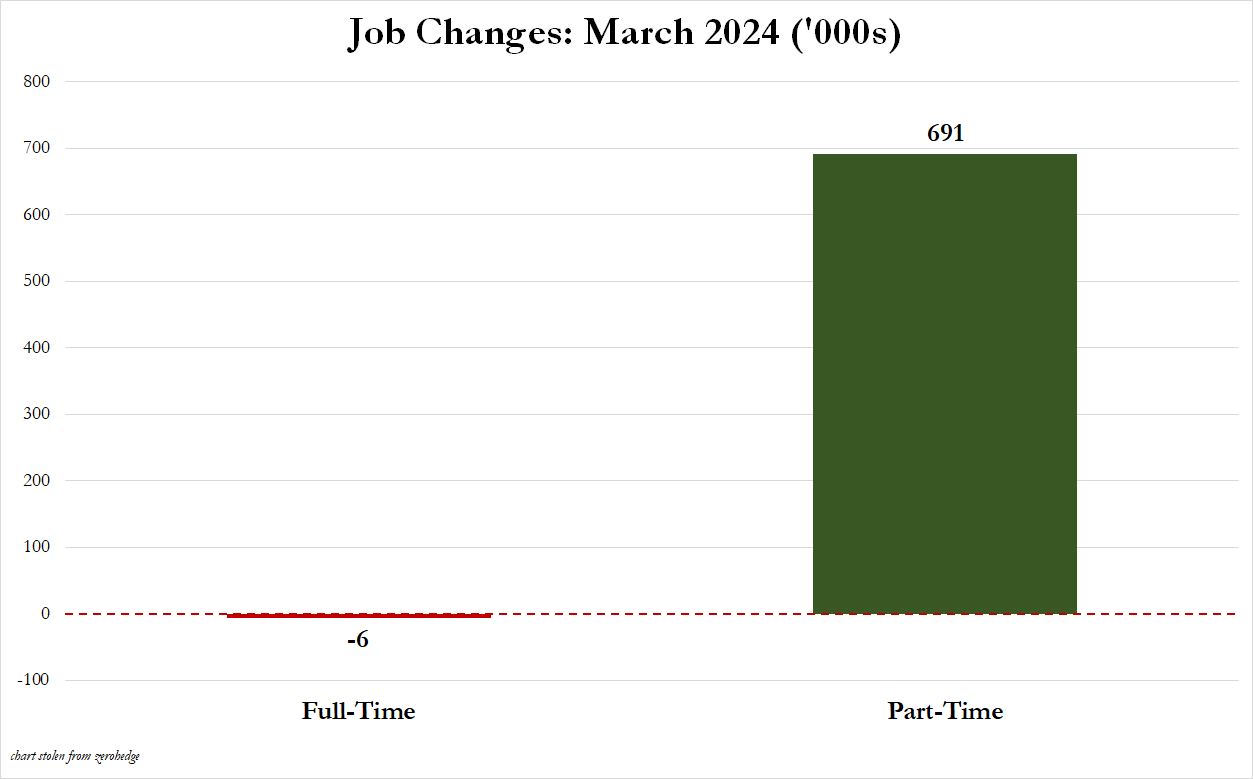
For those wondering if the jobs were all part-time, the answer is a resounding yes: in March, full-time jobs dropped by 6,000 as Part-time jobs soared by 691,000.
On a year-over-year (YoY) basis, full-time jobs were down -1.0% while part-time jobs were up 7.1%
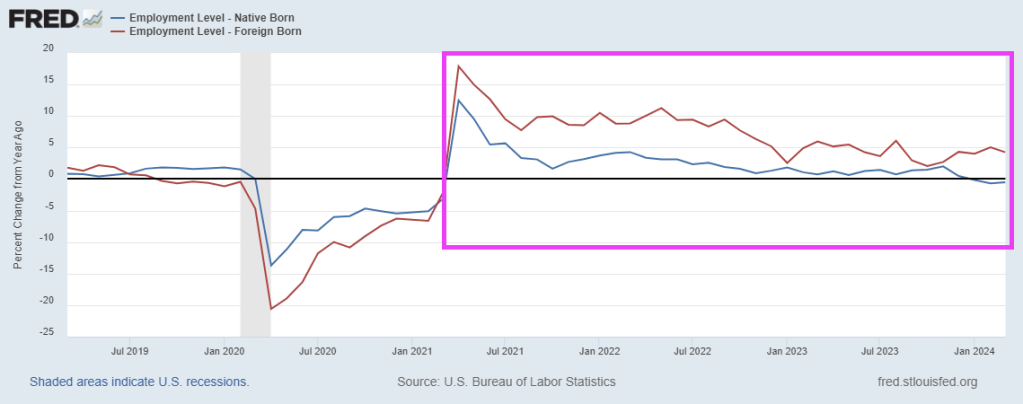
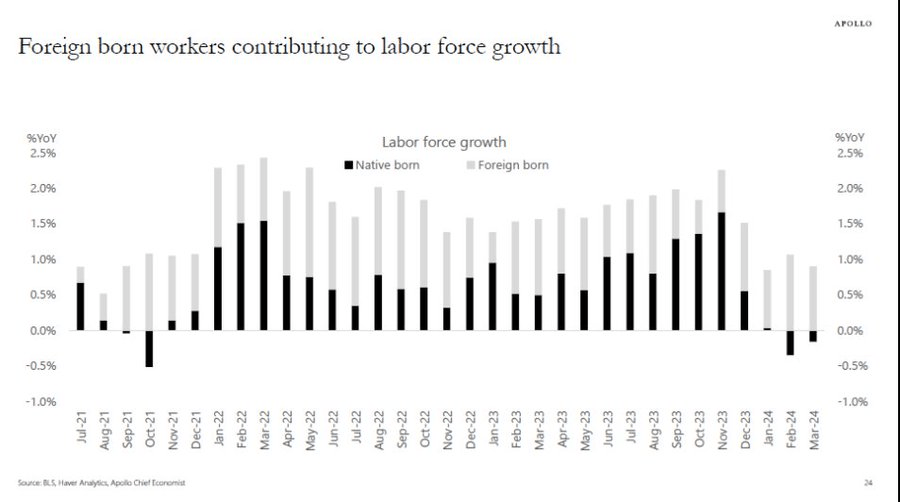
Native-born versus foreign born? On a YoY basis, native-born employment was down -0.5% while foreign-born employment increased by 4.2%.
Not only is Biden importing Democrat voters (since 70% of Americans HATE Biden’s policies), they are also displacing native-born Americans in the labor force.
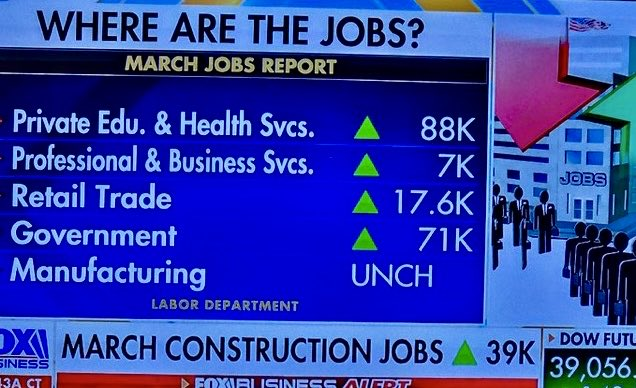
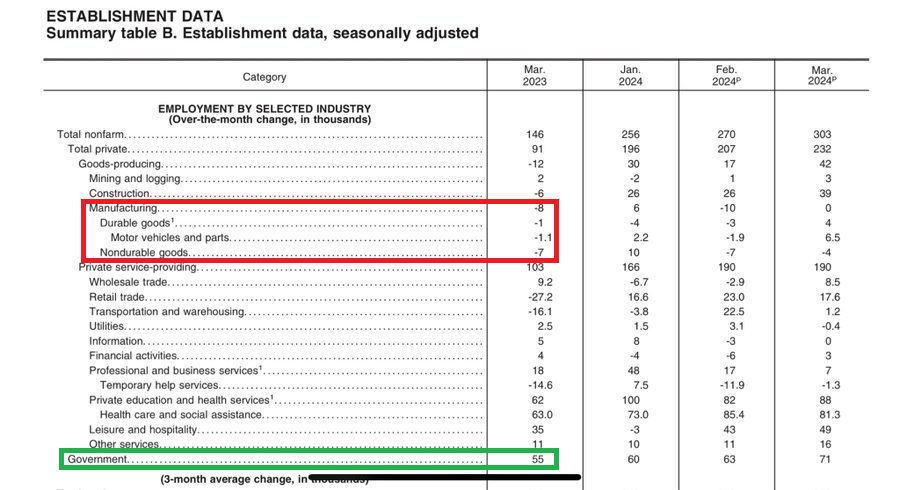
Manufacturing jobs added were ZERO. So, much for all of Biden’s claims. But NON-PRODUCTIVE government jobs were up 71,000. So our manufacturing jobs are dead while non-productive government jobs are growing like crazy.
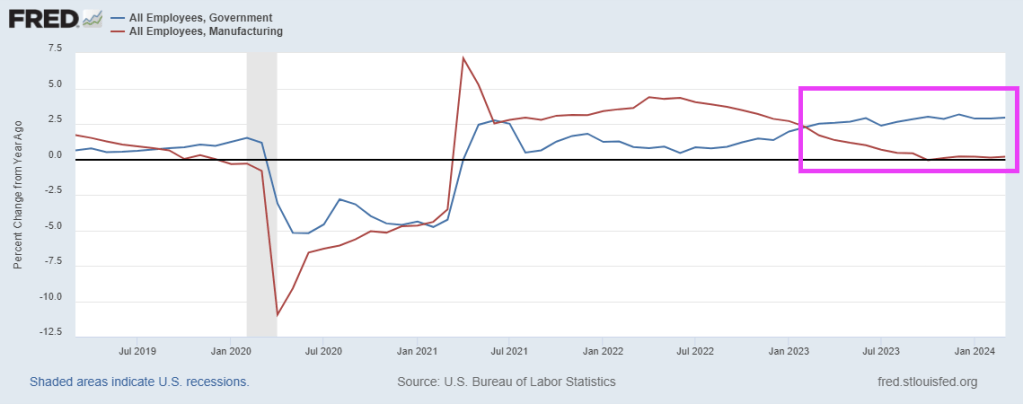
Under Biden, the Administrative state is growing faster than manufacturing since Feb 2023. The Biden Administration implements new rules to prevent Trump’s ability to purge deep state employees if re-elected in 2024.
How will The Fed respond? Likely will lead to limited rate cuts.











You must be logged in to post a comment.