US Real GDP Annualized QoQ printed at -1.5%. And GDP prices QoQ printed at 8.1%, also higher than expected.
At least Personal Consumption printed higher than expected at 3.1%.
Import prices (goods) led the way at 20.9%. Part of Biden’s brilliant strategy of reducing domestic oil production and import expensive energy from overseas?
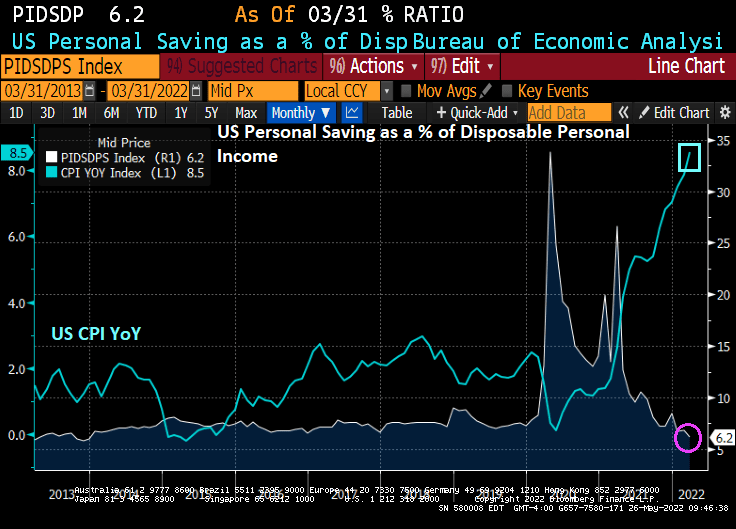
Consumers are spending more, but the personal savings rate is down to the lowest level since 2013 at 6.2% as consumers try to cope with inflation.
The US Q1 GDP report is due out tomorrow morning. The forecast is for -1.3% decline in GDP.
The Atlanta Fed GDPNow real-time GDP tracker is for 1.806% for Q2. If this holds, then recession fears will diminish.
Even though the US may avoid consecutive negative GDP quarters, M2 Money Velocity (GDP/M2 Money) got crushed by The Fed’s reaction to Covid back in 2020.
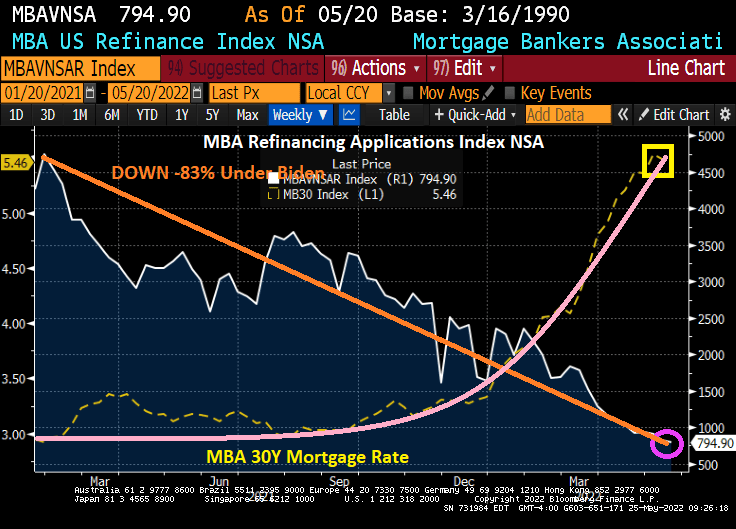
Mortgage applications decreased 1.2 percent from one week earlier, according to data from the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey for the week ending May 20, 2022.
The Refinance Index decreased 4 percent from the previous week and was 75 percent lower than the same week one year ago. And under Biden, the refinance index is down -83.2%.
The good news? The seasonally adjusted Purchase Index increased 0.2 percent from one week earlier. The unadjusted Purchase Index decreased 1 percent compared with the previous week and was 16 percent lower than the same week one year ago. And the mortgage purchase applications index is down -12% under Biden.
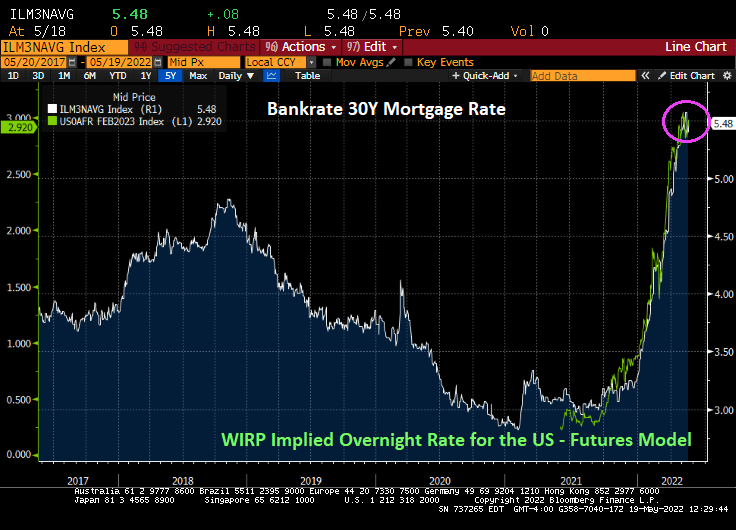
While mortgage interest rates are up 71.7% than one year ago and mortgage rates are up 87% under Biden. As The Federal Reserve signals (but not yet accomplished) monetary tightening.
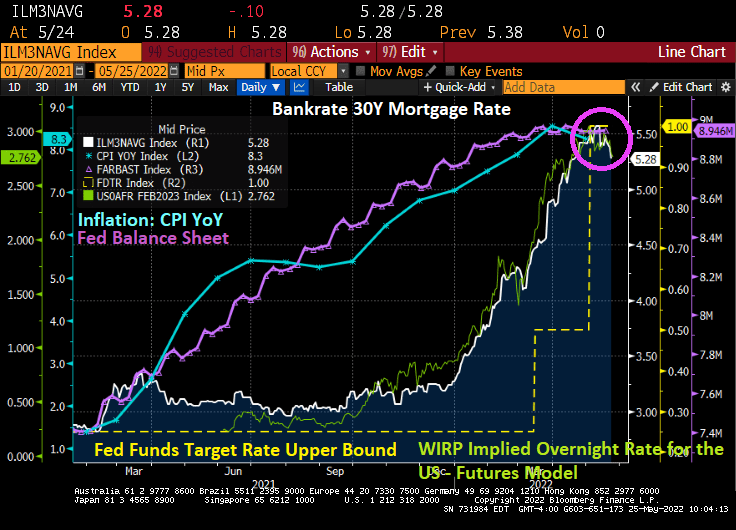
Once again, The Fed is dead set on cooling inflation caused by 1) Biden’s anti-drilling policies and 2) the remnants of the Federal government spending splurge to combat Covid. The Fed has been increasing their asset purchases (purple line) as inflation increase (blue line). Now they are signaling a decline in the balance sheet (green line) in the hope that it will cool inflation. Fat chance.
Let’s see how DEAD SET The Fed is about tightening monetary policy in the face of rising energy and food prices while a war rages in Ukraine and China in a Covid lockdown.
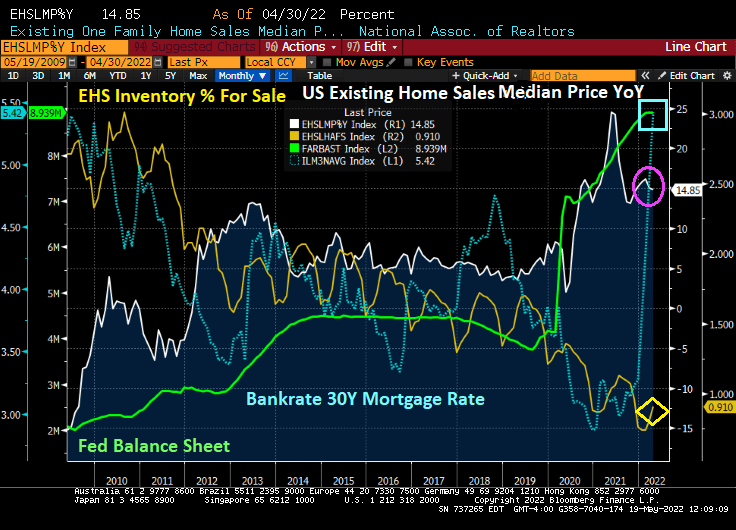
US Existing Home Sales were 5.61M SAAR in April, down -2.4% from March’s -3.0% MoM reading. But median prices YoY for existing home sales printed at 14.85%, still hot, hot, hot.
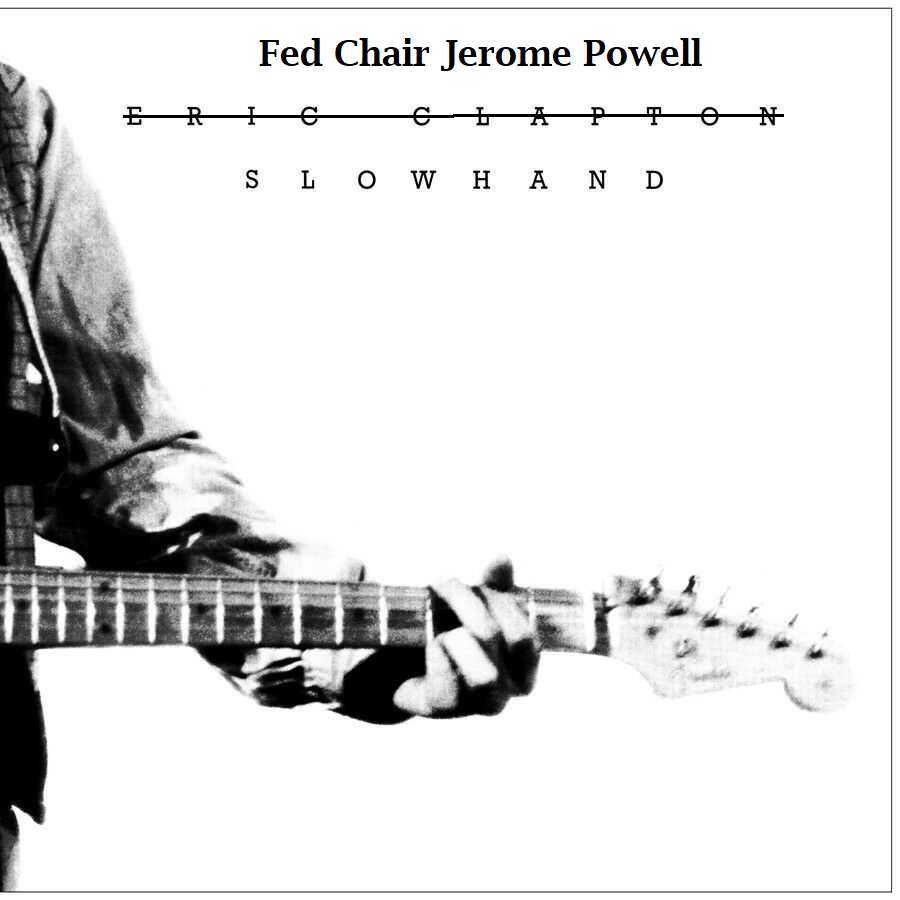
With 3 consecutive declines in MoM existing home sales, how can prices still be raging at 14.85%? First, inventory for sale in April remains low compared to 2010 (yellow line). Second, The Federal Reserve’s Stimulypto (excessive monetary easing) is still out there in force despite Jerome “Slowhand” Powell signaling rate increases (green line). 30Y mortgage rates are still rising.
Where do we go from here? 30 year mortgage rates have been climbing as The Fed signals its intents to tighten monetary policy. But with global economic slowing, Treasury yields have been coming down (like today’s -5.2 BPS drop (Germany’s 10Y Bund Yield dropped -8 BPS on slowing global economic growth).
But remember, the Existing Home Sales numbers are for April.
Goldman Sachs Senior Chairman Lloyd Blankfein urged companies and consumers to gird for a US recession, saying it’s a “very, very high risk.”
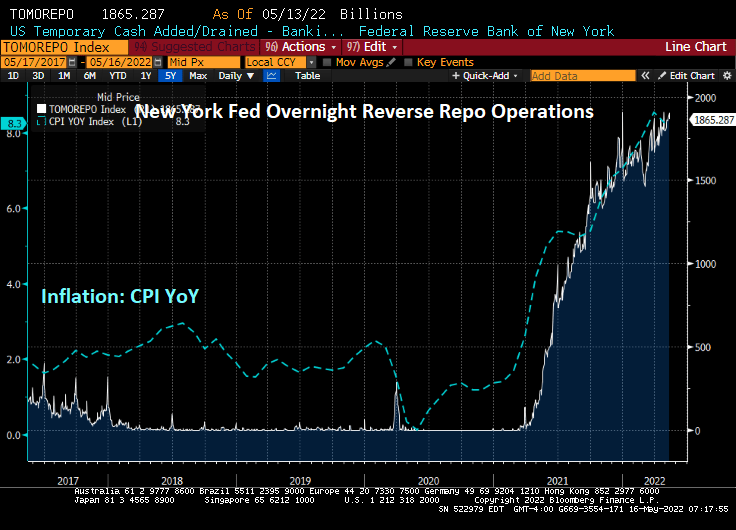
I am not surprised. Take a look at The Fed’s Overnight Reverse Repo operations. As inflation surged in 2021 and 2022, banks are parking more funds at The Fed. Fear?
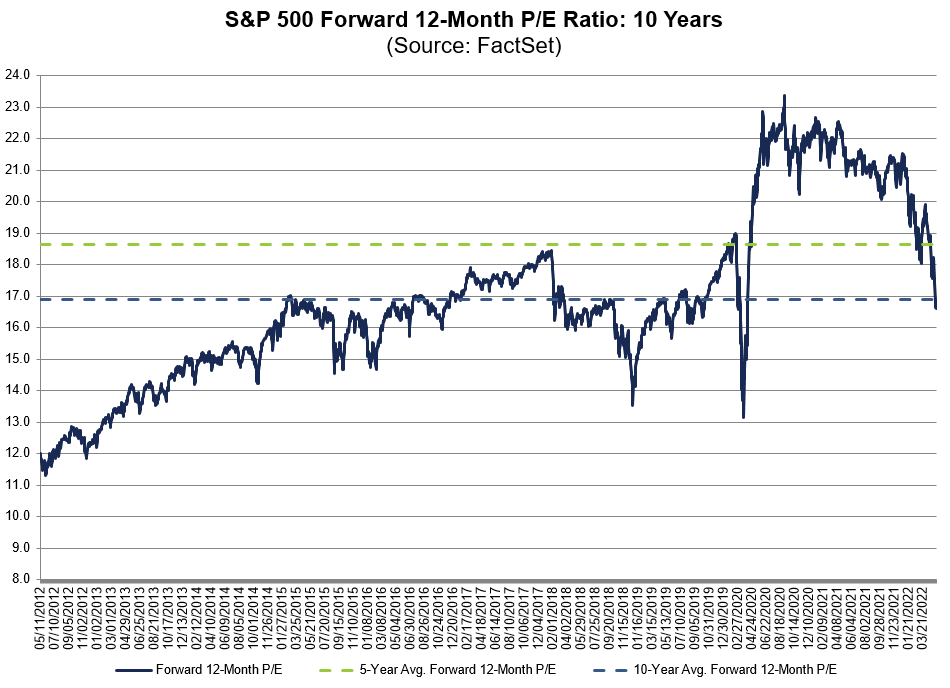
We are seeing the S&P 500 futures down today after a nice rally on Friday. The &P 500 forward 12-month P/E ratio is back to pre-Covid, pre Federal spending surge, pre Fed monetary Stimulypto of 2016.
Goldman Sachs see the 10-year Treasury yield rising to 3.3%. That bodes ill for 30-year mortgage rates, perhaps push mortgage rates up another 40 basis points to 5.80%.
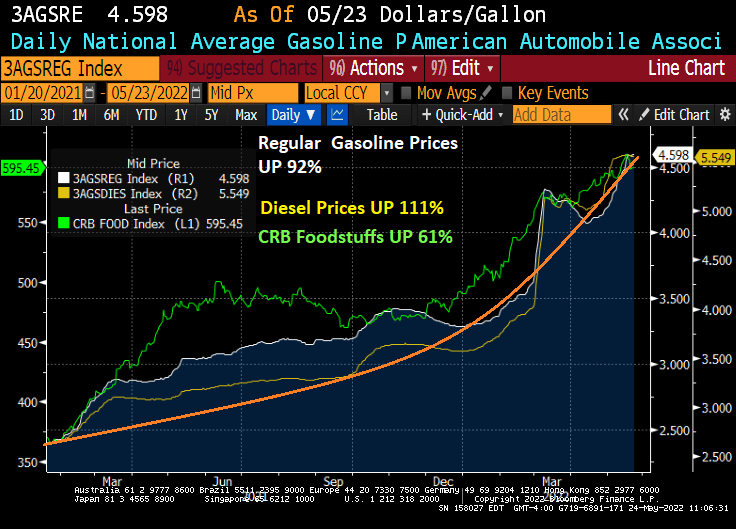
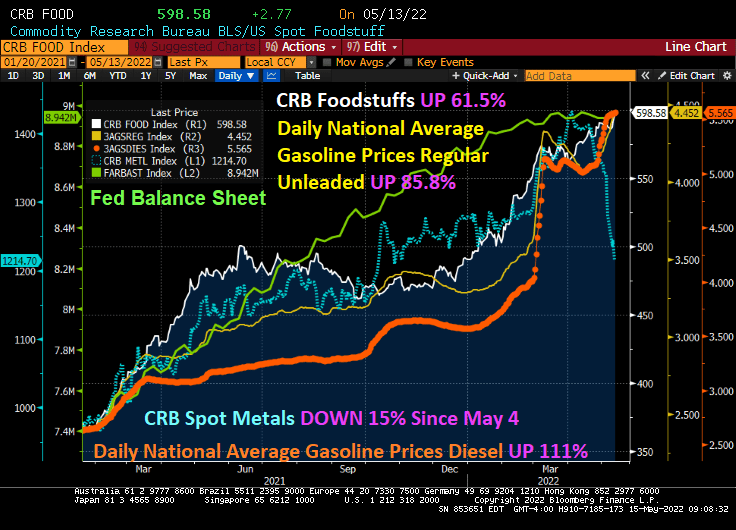
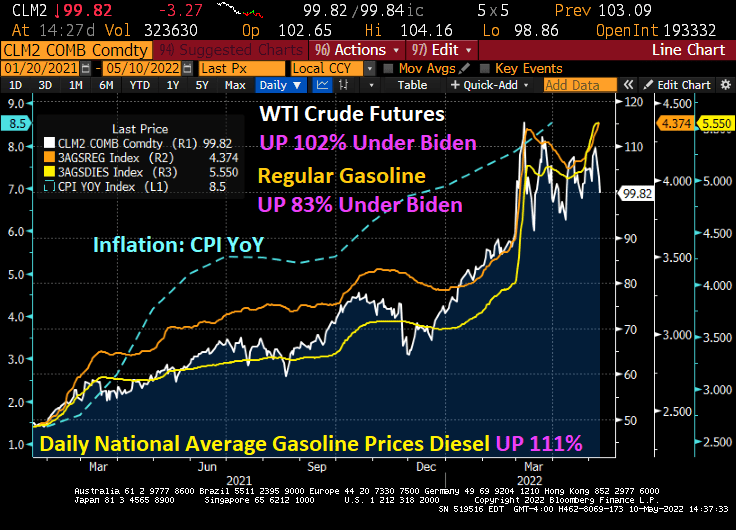
Foodstuff are up 61.5% under Biden’s Reign of Error. Gasoline prices are up 85.8%, diesel prices are up 111%. Yet the government inflation index (aka, CPI) is up only 8.3% in April.
But while energy and food prices are soaring, the CRB Spot Metals Index has plummeted -15% since May 4 as Covid is ravaging the Chinese economy. Recession alter anyone?
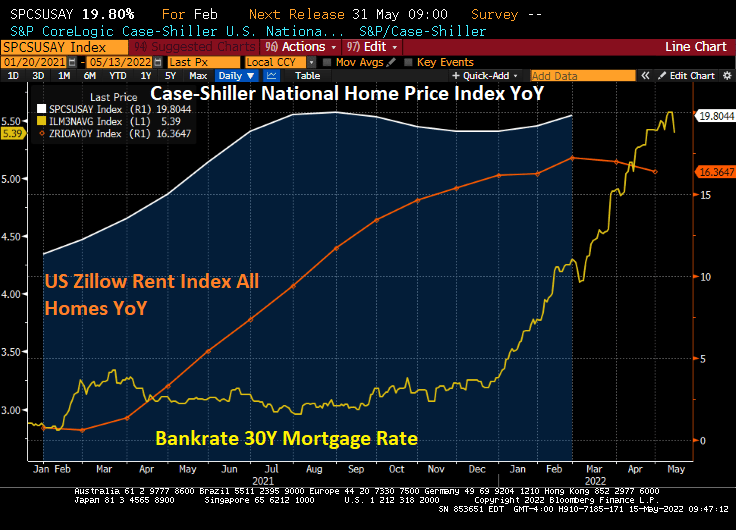
And then we have soaring home prices and rents. But notice that Zillow’s Rent index is slowing down as mortgage rates soar.
We have a stalling Chinese market, down 28% since October. Is Biden President of China??
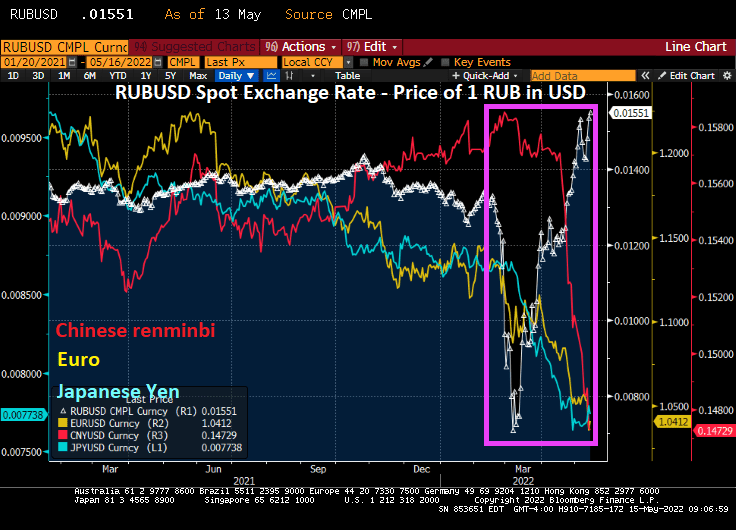
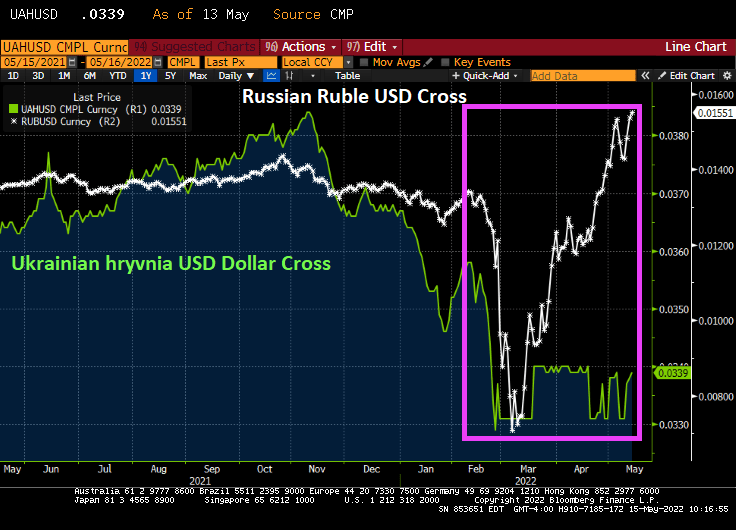
On the currency front, the Russian Ruble is soaring relative to the US Dollar while the Chinese Renminbi, the Japanese Yen and the Euro (or in this case, the Gyro) are sinking like a rock.
If I compare the Russian Ruble and Ukrainian Hryvnia, you can see Ukraine is losing the currency war with Russia.
Inflation Inferno thanks to Biden’s misguided energy executive orders and cancellation of Alaskan and Gulf of Mexico drilling leases.
Biden’s economic mismanagement team: American Gothics Treasury Secretary Janet Yellen and Fed Chair Jay Powell.
Nothing has been the same since Covid and The Federal Reserve’s massive overreaction to the government shutdowns of the economy.
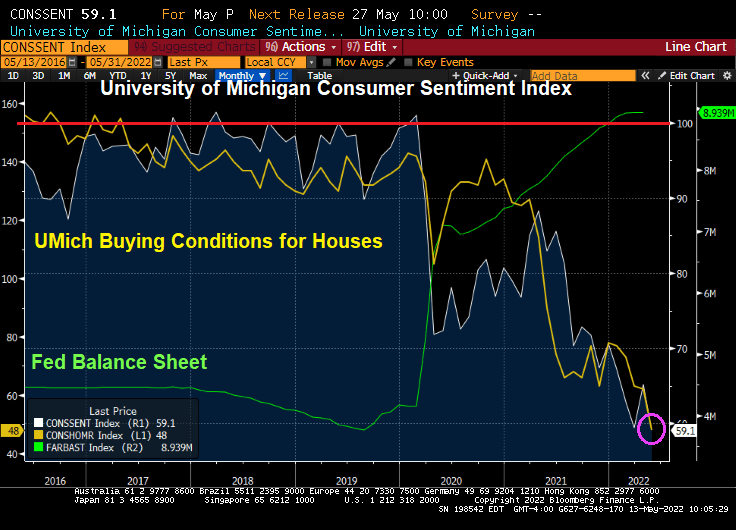
Notice how the University of Michigan Consumer Sentiment Index (white line) has plunged since Covid and the ensuing rise in inflation. University of Michigan’s Buying Conditions for Houses has also plunged to new depths.
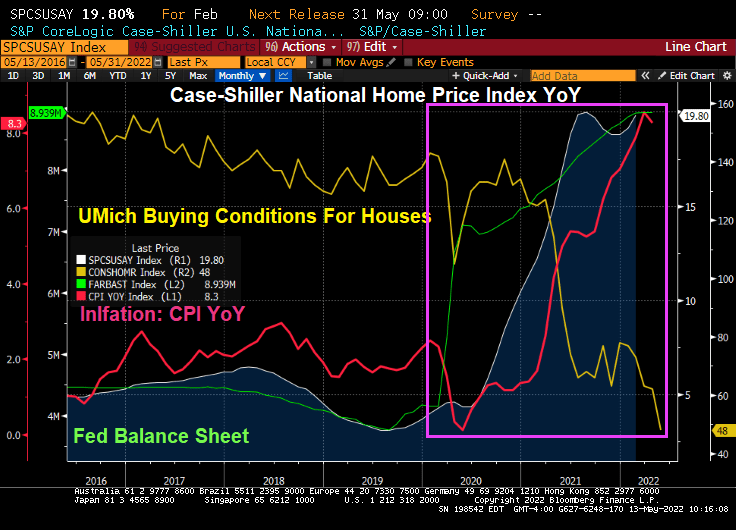
Rising inflation (highest in 40 years) and hottest home price bubble (even hotter than the infamous housing bubble of 2005-2007) AND rising mortgage rates have placed a damper on home buying sentiment.
The US Senate yesterday confirmed the reappointment of Jerome “Slowhand” Powell as Federal Reserve Chairman.
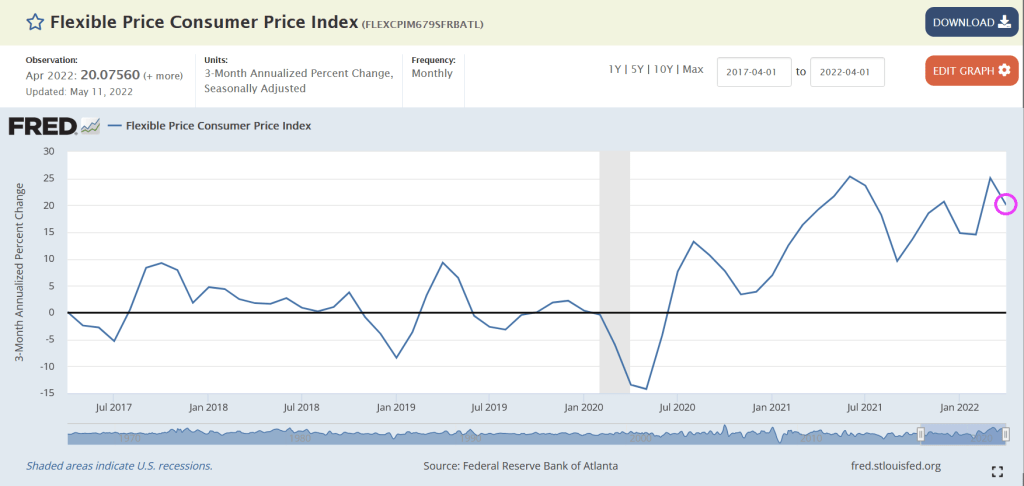
The good news? Atlanta Fed’s Flexible CPI YoY cooled to 20% in April. The bad news? Flexible prices are still growing at 20% while wages are growing at 5.5% YoY.
On the export front, export prices are cooling and were at 18% YoY in April, down slightly from March. Import prices cooled to 12% YoY as The Federal Reserve has slowed asset purchases.
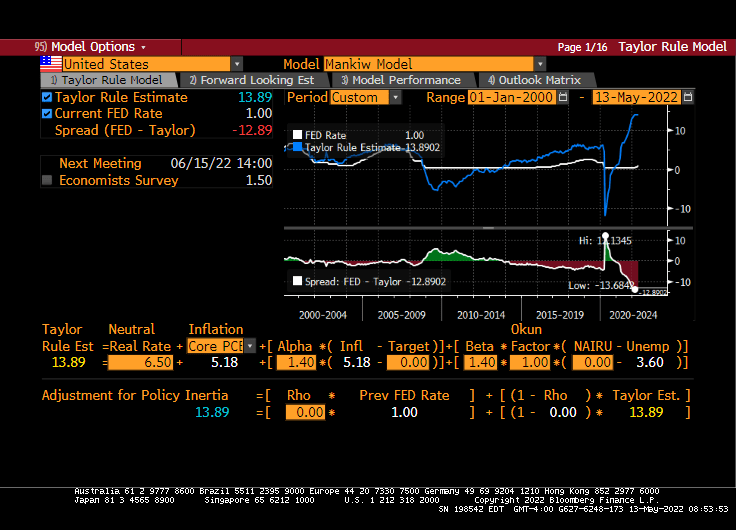
I would have preferred President Biden appoint a serious Federal Reserve Chairman liked Stanford University’s John Taylor (of Taylor Rule fame). In his honor, here is the Mankin version of the Taylor Rule which calls for a Fed Funds Target Rate of 13.89% while the current Fed Funds Target Rate under Powell and the Gang is … 1%.
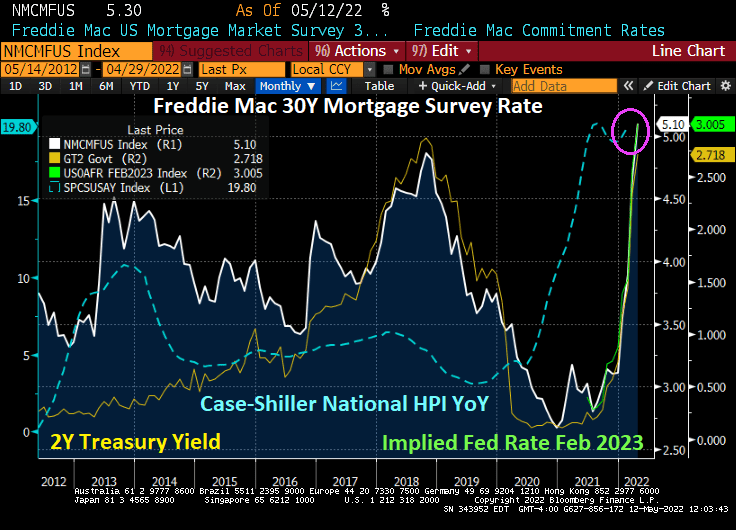
The Freddie Mac 30-year mortgage rate is rising faster than a SpaceX moonshot!
I’m telling your now that The Fed is killing the dreams of millions of Americans by pricing them out of the housing market. Home price growth is lethal as is the increase in mortgage rates.
Joe Biden likes to sell himself as “Middle Class” Joe. But Middle Class Joe declared war on the middle class with executive orders on fossil fuel drilling and killing the Keystone pipeline. Hence, his press conference on reducing inflation left off one thing: he could rescind the aforementioned executive orders. But he didn’t. So its Band-Aids on Band-Aids.
Since Biden was elected President, WTI Crude Oil futures are up 102%. Regular gasoline is up 83% and the lifeline of the shipping industry, diesel, is up 111%. Of course, inflation measures don’t measure the harm to the middle class at 8.5% YoY.
Here is Biden’s speech, blaming everyone but himself for inflation. And then walks away (as usual) when asked a tough question. But he lied. He COULD cancel his executive orders on oil and natural gas exploration, but didn’t. Instead, he blamed Trump and MAGA voters.











 Confounded Interest - Anthony B. Sanders

You must be logged in to post a comment.