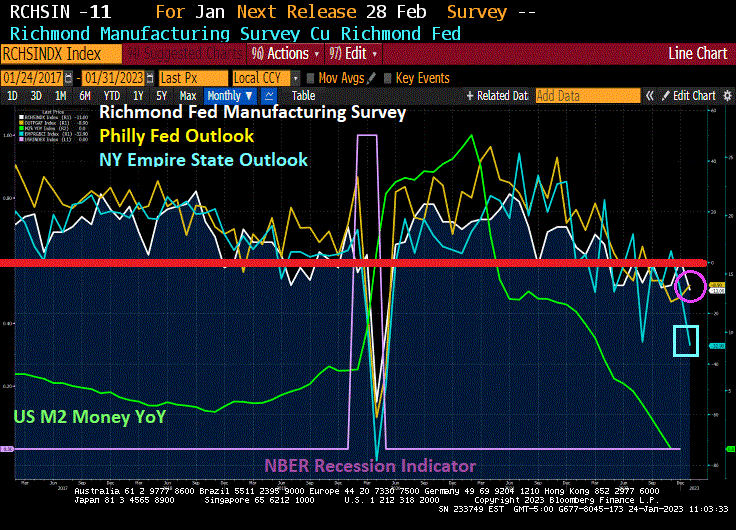
Three regional Fed reports I like to watch are New York’s Empire State Outlook, Philly Fed’s Outlook and Richmond Fed’s outlook. Today, The Richmond Fed released their manufacturing outlook and … it declined to -11.
So the big three are all down (Philly down to -8.9 while NY’s Empire State outlook is down to -32.9.
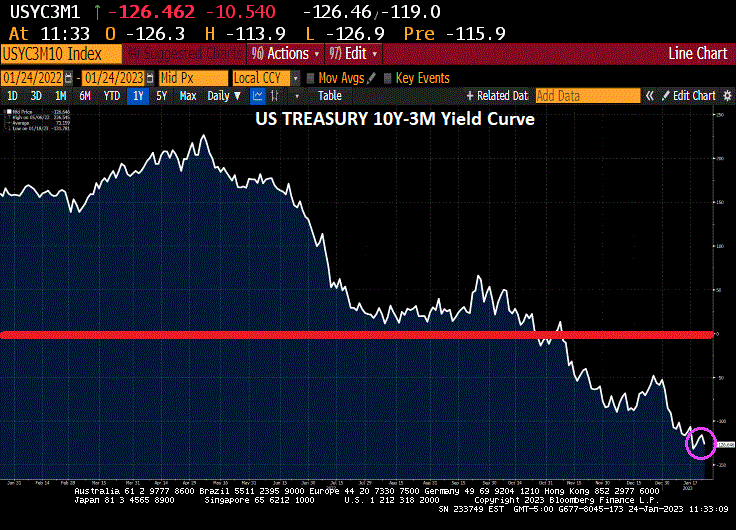
On the Treasury front, the US 10Y-3M yield curve inverted further (a signal of impending recession) just tanked to -126.462 basis points.
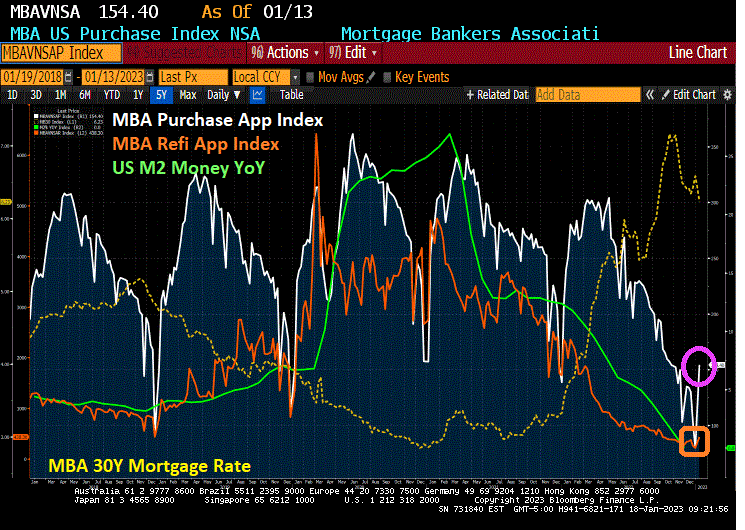
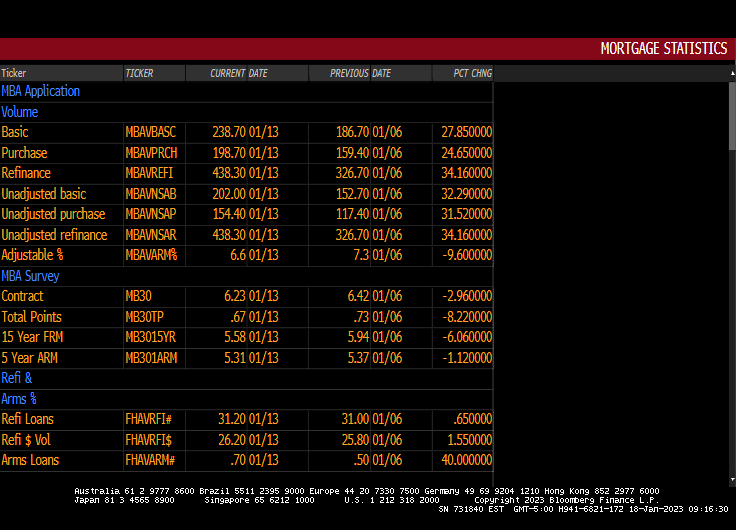
Mortgage applications increased 27.9 percent from one week earlier, according to data from the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey for the week ending January 13, 2023. But mortgage applications are 60% lower than the same week last year.
The Refinance Index increased 34 percent from the previous week and was 81 percent lower than the same week one year ago. The seasonally adjusted Purchase Index increased 25 percent from one week earlier. The unadjusted Purchase Index increased 32 percent compared with the previous week and was 35 percent lower than the same week one year ago.
Here are the stats.
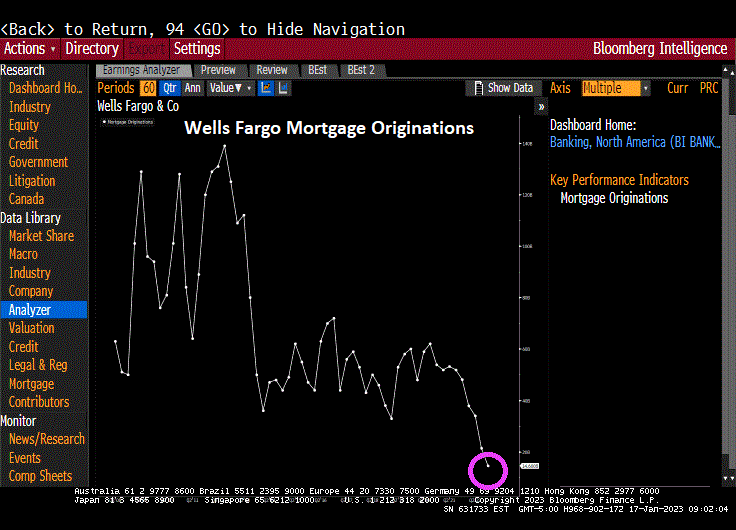
One lender in particular, Wells Fargo, smells blood in the economic waters, and has cut back mortgage originations.
Just remember, mortgage applications generally rise in the first part of the year until May, then start slowing until the last week of the year. This is called seasonality. But despite the fast growth this year, purchase applications are still down -35% compared to last year at this time.
The 2020 Covid outbreak and the resulting government shutdowns and school closures begat a Washington DC spending spree and Federal Reserve monetary stimulus barrage unlike anything other time in history. Congress and Administrations love to spend other people’s money, but as Rahm Emanuel once said “You never let a serious crisis go to waste. And what I mean by that it’s an opportunity to do things you think you could not do before” And wow, did they ever binge spend and expand the M2 Money supply. I call it “The Great Dislocation” of the economy and we never recovered from it.
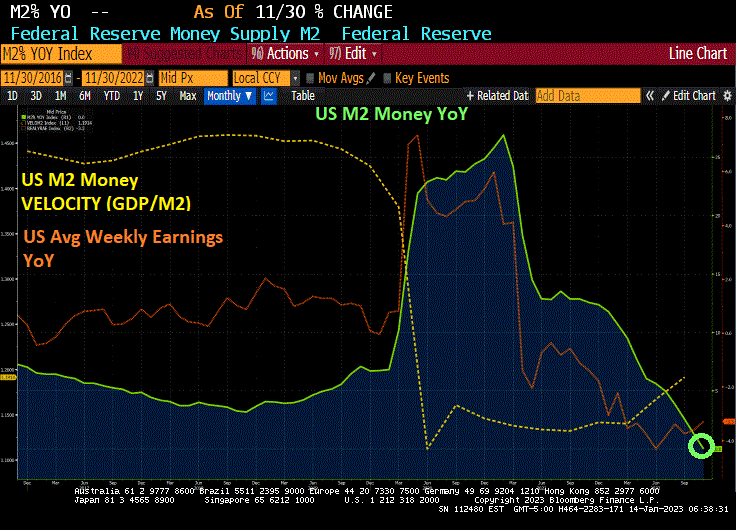
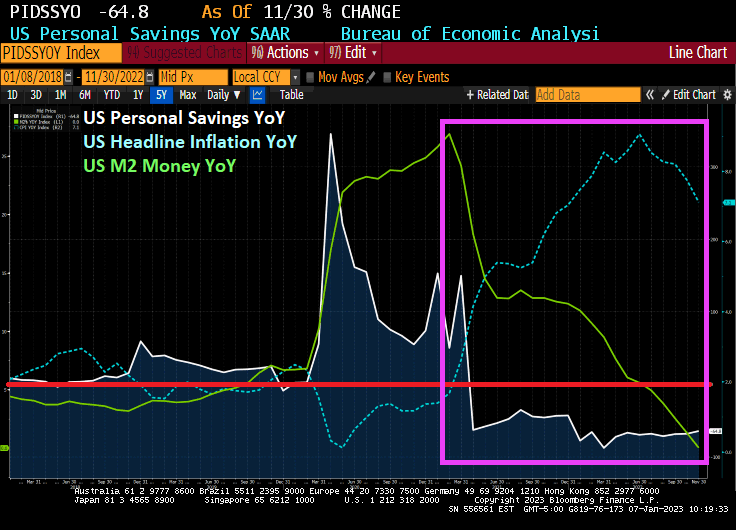
But after the massive spending splurges and Fed monetary stimultypto, The Fed finally started withdrawing “the punch bowl” to combat inflation. M2 Money growth year-over-year (YoY) is now 0%. And with inflation, US average weekly earnings growth YoY turned negativc and has been negative for 21 straight months.
After the spending explosion under Pelosi/Schumer and Powell’s monetary, M2 Money velocity (GDP/M2 Money) crashed to it lowest level in history. So now we have depressed money velocity and no M2 money growth. And the US still has 21 straight months of negative weekly earnings growth.
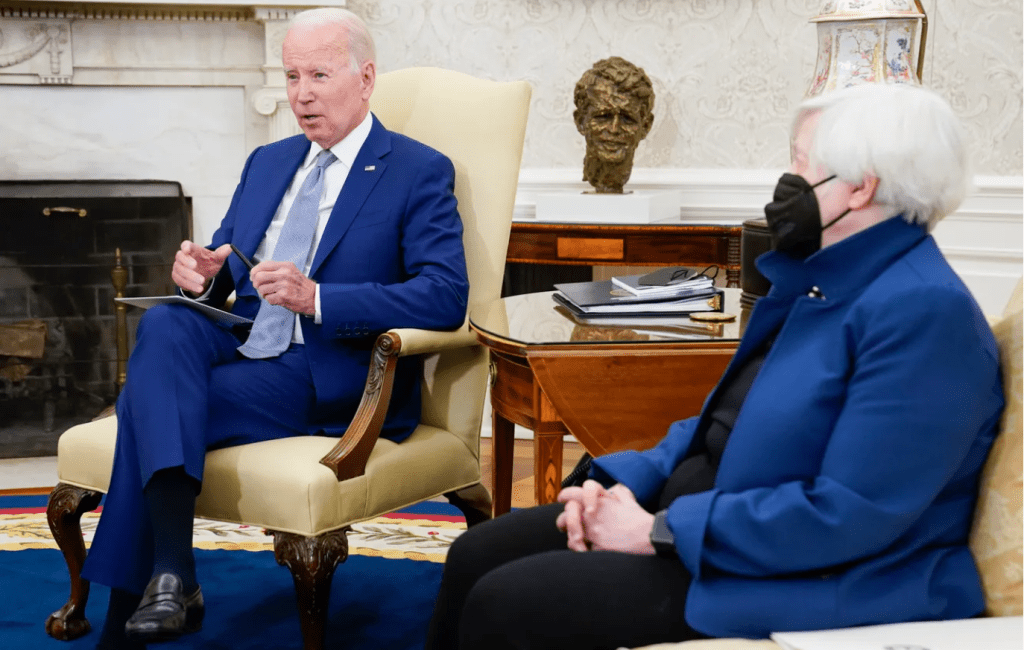
But former Fed Chair and current Secretary of Treasury Janet Yellen is pleased that inflation is FINALLY slowing which Yellen attributes to relaxing supply chains. Or is it declining M2 Money growth, Janet?
Now that the Federal government’s spending spree and The Fed’s monetary stimulypto dislocated the US economy, we are headed for a recession with no ammunition left in The Fed’s arsenal.
After all. The Federal Reserve has been destroying consumer purchasing power since 1913. And we may be at the end of The Fed’s monetary rope.
Even worse, we have Joe Biden as President, who curiously has been found to have classified documents in his possession from when he was Vice President, at least, at two locations (his Wilmington DL home that his son Hunter had access to and the now infamous Penn Biden Center in Washington DC). Even worse, Biden seems to be talking to dead world leaders like Germany’s Schmidt and France’s Mitterand.
Knowing Biden’s penchant for blatant lying and carelessness, I wouldn’t be surprised if this is a stack of classified documents on the table during his meeting with Treasury Secretary Janet Yellen.
Let’s hope Biden isn’t saying that he is talking to late Robert Kennedy, the former US Attorney General.
US headline inflation began to soar as soon as Joe Biden became President. A combination of massive stimulus spending related to the Covid economic shutdown and his war on fossil fuels, driving up gasoline and diesel fuel prices. In other words, headline inflation rose from 1.4% Year-over-year (YoY) at the end of December 2020 to 9.1% YoY in June 2021. It has now simmered down to 7.1% YoY as The Fed continues to remove monetary stimulus.
How have consumers coped with inflation caused by massive Federal spending and Biden’s anti-fossil fuel policies? In November, personal savings dropped -64.8% YoY. This marks 20 straight months of declining personal savings.
US M2 Money growth YoY is now … 0%. That is the lowest in US history.
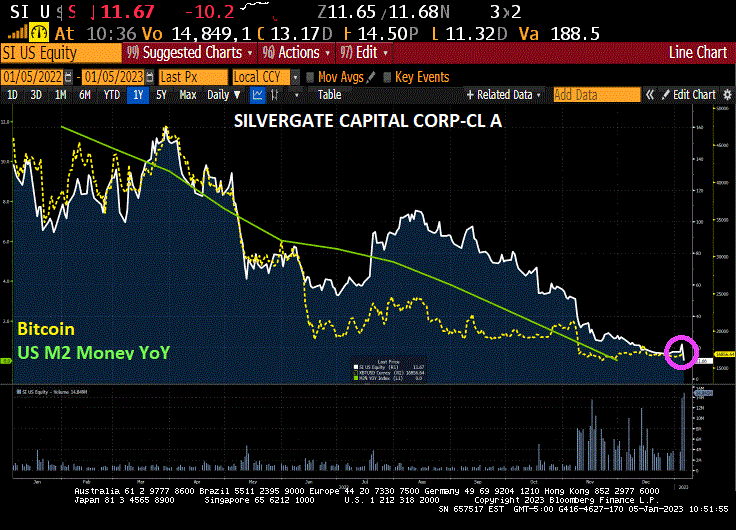
Silvergate Capital Corp. shares plunged after the bank said the crypto industry’s meltdown triggered a run on deposits, prompting the company to sell assets at a steep loss and fire 40% of its staff.
Customers withdrew about $8.1 billion of digital-asset deposits from the bank during the fourth quarter, which forced it to sell securities and related derivatives at a loss of $718 million, according to a statement Thursday. Executives said on a conference call that Silvergate may become a takeover target.
“In response to the rapid changes in the digital asset industry during the fourth quarter, we took commensurate steps to ensure that we were maintaining cash liquidity in order to satisfy potential deposit outflows, and we currently maintain a cash position in excess of our digital asset related deposits,” Chief Executive Officer Alan Lane said in the statement.
The collapse of Sam Bankman-Fried’s FTX sparked a crisis for Silvergate, which held deposits for FTX units and Alameda Research, the trading firm at the heart of the crypto exchange’s downfall. Lawmakers are also scrutinizing the bank.
Silvergate plunged 44% to $12.34 at 9:48 a.m. in New York, the steepest decline since the La Jolla, California-based company went public in November 2019. The stock is down 91% in the past 12 months. Signature Bank, which said in December that it intended to shed as much as $10 billion deposits from digital-asset clients, fell 5.8% to $111.05.
Silvergate Capital Corporation operates as a bank holding company. The Company, through its subsidiary Silvergate Bank provides a banking platform for innovators, especially in the digital currency industry, and developing product and service solutions addressing the needs of entrepreneurs. Silvergate Capital serves customers in the United States.
Silvergate once saw the crypto industry as giving it a huge growth opportunity. Over the course of a decade, it transformed itself from a firm catering to small businesses into a publicly traded company known for providing banking services to major crypto clients such as Coinbase Global Inc. and Gemini Trust Co. — as well as FTX and Alameda Research.
At least Solana is on the rise.
Sam Bankman-Fried will go down in history as commiting one of the greatest financial frauds in world history. Why did he have four meetings with Biden’s top staffers prior to FTX’s crash and burn?
2022 is one of the record books and not in a Tiger Woods way. Call it a year of pain.
First, the US enacted policies that drove up energy prices (goin’ green) that reverberated through the entire economy in the form of higher prices. Second, The Federal Reserve, in attempt to combat runaway inflation, started removing the excessive monetary stimulus that had been around since Fed Chair Bernanke initiated QE, the seemingly unlimited purchase of Treasury and Agency MBS securities. Janet Yellen continued the massive asset purchases and zero interest rate policies or ZIRP. Now that inflation has struck the American middle class hard, we are seeing Fed Chair Powell doing what Bernanke and Yellen wouldn’t do — remove the monetary punchbowl.
Using Robert Shiller’s on line data, US stocks and bonds have had an awful year, the worst combined year since 1871.
US equity returns have been demolished under the NEW dual mandate (goin’ green = rising prices = Fed tightening).
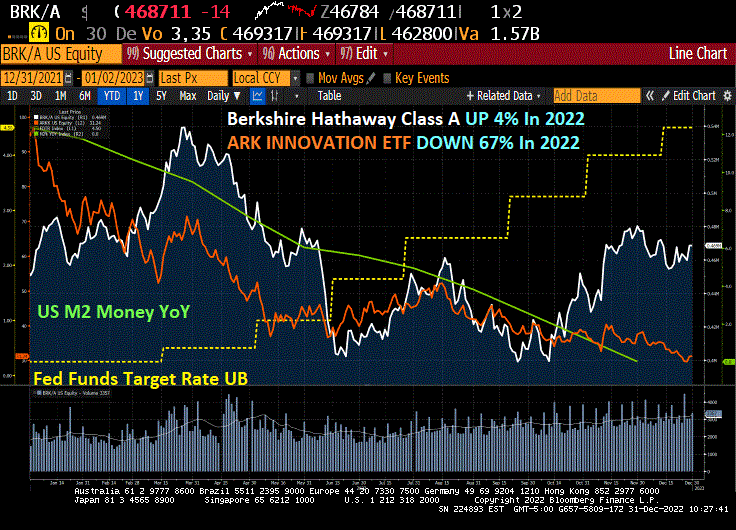
Let’s see how two of the most famous investment gurus did in 2022, Warren Buffet and Cathie Wood. Buffet’s Bershire Hathaway Class A equity was UP 4% in 2022, while Cathie Wood’s ARK Innovation ETF collapsed by -67% in 2022.
Here is the clinker. The US economy (as well as the global economy) seem dependent on “cheap money” from Central Banks like The Federal Reserve. So the question is … will The Fed pivot? Fed talking heads are saying no, but Fed Funds investors are saying yes to a pivot after June 2023.
Ulysses S Grant was the President the last time the combined stock and bond market was this bad.
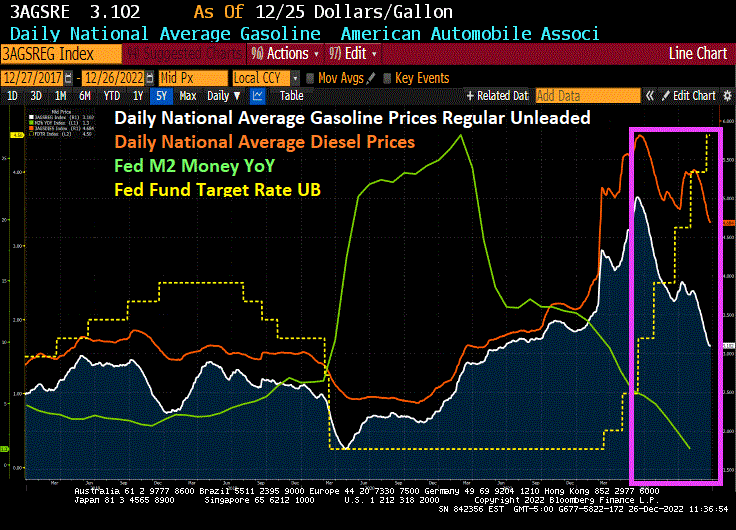
As the global economy slows and global central banks continue to tighten, we are seeing gasoline and diesel prices falling.
But bear in mind that US gasoline prices remain 30% higher since Biden was sworn-in as President. Diesel prices are up a staggering 78% since that fatal day.
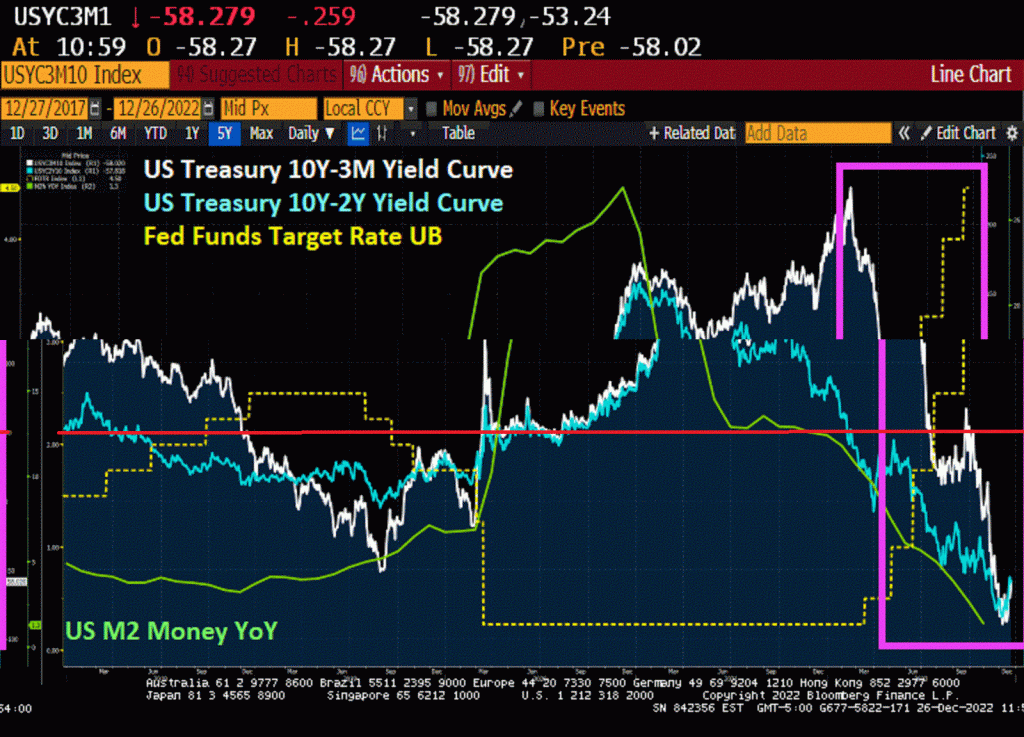
Speaking of tightening monetary policy, the US Treasury yield curves have flattened/inverted since The Fed started tightening with rate increases to fight inflation.
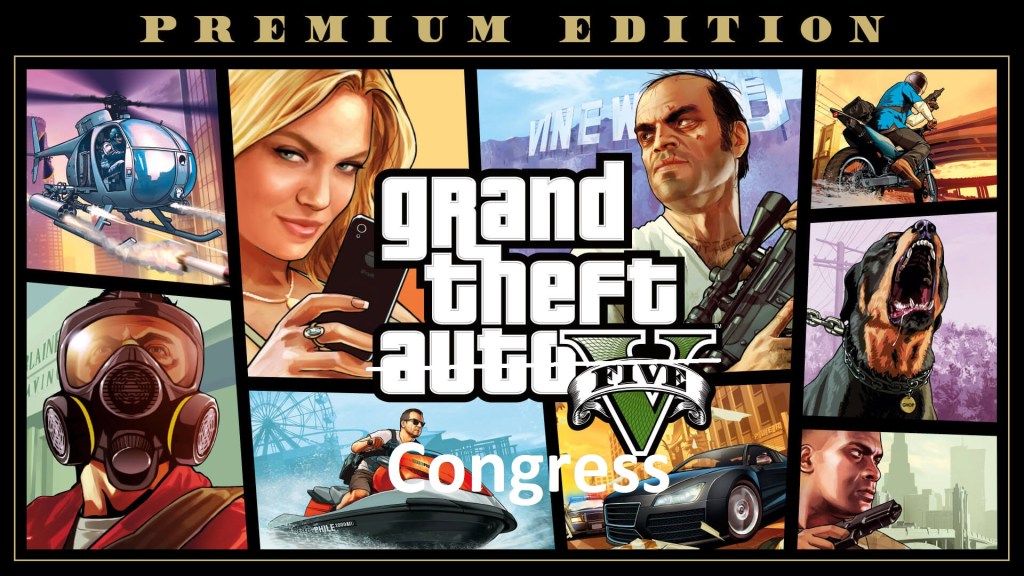
Let’s see how inflation does with Congress’ $1.7 trillion, unread Omnibus bill. Aka, Grand Theft Congress. Pelosi is holding an iPhone and Schumer is holding the scope rifle. McConnell is wearing the gas mask since the wasteful spending truly stinks.
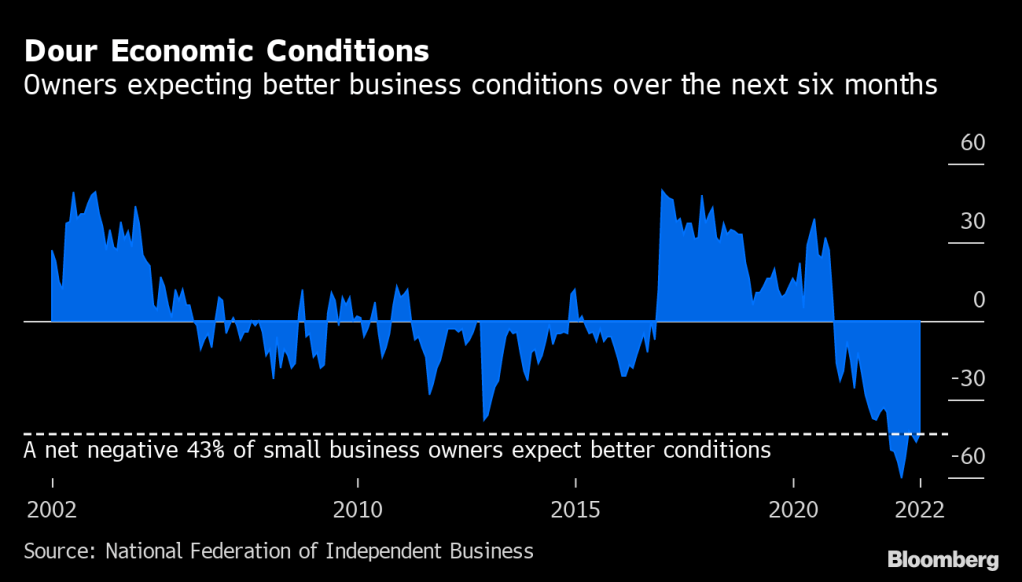
The highest interest rates in 15 years are delaying home dreams, putting business plans on ice and forcing many Americans to agree to loan terms that would have been unimaginable just nine months ago. Biden’s anti-fossil fuel policies are helping drive up prices and The Federal Reserve is hiking rates to cool it off.
Most of all, the surge in borrowing costs is punishing the cash-poor. And it’s about to get worse as the Federal Reserve carries on with its anti-inflation campaign and keeps hiking rates next year.
As the Fed’s most aggressive interest-rate hike cycle in a generation filters through the US economy, the gap is widening between the haves and the have-nots. Even without a recession, households and businesses are feeling the financial pain.
Here’s a look at pockets of the economy that are bearing the brunt of the impact.
Housing in Holding Pattern
Manda Waits from Suwanee, Georgia, feels lucky that she and her husband bought their townhouse near Atlanta a year ago with a 3% loan — less than half of where mortgage rates are now.
To trim expenses amid soaring consumer prices, the couple recently bought a freezer and stocked it with a quarter cow and half a pig sourced from an agricultural school. But they shelved their plan to upgrade to a single-family home for the time being.
“We would like to buy some land to build on, but these rates aren’t making it attractive, so we are in a holding pattern,” said Waits, who receives disability benefits.
Even in the once red-hot market of Tampa, Florida, a few people showing up at an open house is now considered a good day. “People are just waiting on the sidelines,” said Rae Anna Conforti, a realtor with Re/Max Alliance Group.
As mortgage rates hit their highest levels since 2001 this year, real estate agents suddenly found themselves hunting for clients again — if not losing their jobs. Thousands of mortgage employees have already been laid off at lenders including Wells Fargo & Co. and JPMorgan Chase & Co.
The higher rates, coupled with a surge in home values during the pandemic, pushed the monthly mortgage payment on a median-priced house to more than $2,000, up from about $1,100 just before Covid-19 hit.
‘Vicious Circle’ The widening gap between the cash-rich and the cash-strapped is playing out at car dealerships across the nation. The former are paying more upfront, while the latter are stuck with high-rate auto loans that will leave them underwater — or forced to settle for cheaper and less reliable vehicles.
Almost one in three car buyers are now taking out six- to seven-year loans on used vehicles to help lower monthly payments.
When consumers are locked for so long, the outstanding balance quickly exceeds a used car’s value, said Oren Weintraub, whose California-based service helps consumers negotiate better prices with dealers for a fee. When they buy their next car, that balance will get tacked onto to the new loan.
“It’s a vicious cycle,” he said.
Matt Tambornini was hoping to take out a car loan to build his credit history. The 22-year-old, who lives near Knoxville, Tennessee, with his parents, figured he’d be in a position to buy a house when mortgage rates eventually come down.
His plan stumbled when a local car dealership offered a 23% loan rate and a 60-month term, a deal that would’ve had him paying thousands more than he wanted. He bought the car anyway, quickly got buyer’s remorse and returned it for a refund.
For now, he’s driving a 15-year-old pick-up he bought with cash.
“It seems like everything is just unaffordable,” Tambornini said.
Soaring Credit Debt Interest rates on credit cards that averaged 16.3% at the beginning of the year have climbed to just over 19%, according to Bankrate.com, the highest level in data going back to 1985.
That’s a massive increase especially for lower-income consumers, who may be making the minimum payment and carrying a balance for 20 years, said Scott Sanborn, chief executive officer of LendingClub Corp.
“I don’t think consumers have fully internalized yet how much their cost of living has actually increased,” Sanborn said.
The surge in APRs to historical highs isn’t affecting consumers the same way. It makes no difference to those who pay off their balances monthly — many don’t even notice the rate increases — but it’s hitting those who are falling behind.
Mike Lauretti, 24, has about $12,000 in debt on four cards, as well as car, student and private debt. The high school social worker, who lives near Hartford, Connecticut, is working on paying off the card with the smallest amount first before moving to the next — known as the snowball method. He also took an extra job as a coach of the girls basketball team to supplement his income.
“I am using the snowball method to pay off the cards first and then it’ll eventually lead to me paying the private loan,” the largest, he said.
American consumers will end the year with about $110 billion more in credit-card debt than they started with, which would be close to an annual record, according to WalletHub, an online personal finance data firm. The reality may hit next year, when many economists predict the US will enter a recession. Household debt delinquencies are still well below their end of 2019 levels, but they’re picking up.
“We expect delinquencies to continue to increase, with new credit-card and auto delinquencies reaching pre-pandemic levels in the first half of next year,” Moody’s Investors Service said in a report.
Small Businesses
In Dayton, Ohio, Clara Osterhage would love to add to her 82 Great Clips hair salons and she knows people who are looking to sell.
“But I can’t put myself in a place to buy them, because the interest rates on any money that we would borrow would be astronomical,” she said.
Matt Haller, chief executive of the International Franchise Association, said high loan rates will keep smaller buyers of franchises out of the market, while bigger companies with more access to capital consolidate.
Meantime, some would-be buyers are demanding that sellers help finance the deal, said Dustin Zeher of Horizon Business Brokers in Virginia.
“We’re talking about 50% to 80% of the transaction, because they are cognizant and aware of the rising interest rates and how that has effectively reduced their buying power and has increased the cost of the transaction,” Zeher said.
Greg Vojnovic, owner of a small fast-food chain in the Youngstown, Ohio area, said the debt service — or debt payments — on his Small Business Administration loan has risen by $70,000 annually, and he expects it to climb at least another $15,000 as the Fed continues to raise rates. He’ll have to cut two part-time corporate-office positions to lower costs.
“If bacon goes up, people understand if you raise prices,” said Vojnovic, owner of the Hot Dog Shoppe. “If chicken goes up, people understand that. If debt service goes up, you just kind of have to eat that.”
Here is Joe Biden, shooting the hopes of millions of Americans in the tuchus.
Like the Mel Gibson movie “Apocalypto!”, we are seeing the US middle class and low-wage workers being economically sacrificed by The Federal Reserve, the Biden Administration and Congress.
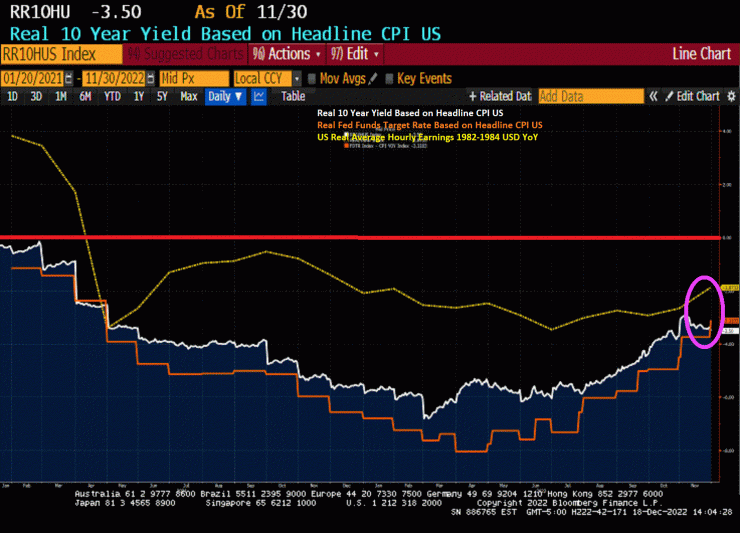
Despite the rhetoric that Fed stimulus (aka “Stimulypto!”) is being removed, the US remains plagued by NEGATIVE real 10-year Treasury yields, NEGATIVE real Fed Funds Target rate and NEGATIVE real average hourly earnings growth under Inflation Joe.
This chart demonstrates the Stimulytpo problem. Prior to Covid, US wage growth was consistently higher than headline inflation. But starting in March 2021, three months after Biden became President, headline inflation became higher than wage growth.
Even with all these negative REAL rates, the US economy is forecast to have almost no growth in 2023.
To quote Peggy Lee, Is That All There Is? Trillions in Federal spending and Fed monetary stimulus and all we get it 0.50% Real GDP??
One of the great ironies of the Sam Bankman-Fried debacle is that while SBF was a generous donor to Democrats (and a few RINOs) and President Biden, it was Biden’s green energy policies that were part of the nail in SBF’s crypto empire. As inflation exploded upon Biden taking office (and massive overspending by Congress), The Federal Reserve jumped in to cool inflation leading to the downfall of cryptos in terms of price.
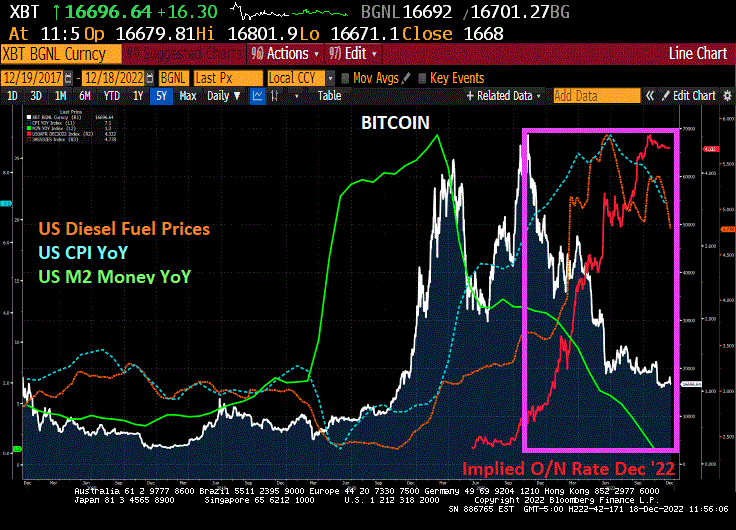
M2 Money YoY (green line) shows the massive growth money with the Covid economic shutdowns in 2020. Cryptos skyrocketed after that much money was printed by The Fed. Cryptos fell shortly after peaking in April/May 2021, then peaked again in a horrific display of asset volatility in October/November 2021.
What happened in late 2021 to crush cryptos? Ah, expectations of Fed rate increases (red line) started to soar meaning the punchbowl for cryptos was being taken away. The Fed giveth and The Fed taketh away.
The risk management question is … how did SBF and Alameda Research’s Caroline Ellison didn’t notice the relationshop between crypto prices and changing Federal Reserve monetary policy? Even worse, why didn’t investors ask questions??
Take a gander at Bitcoin relative to US diesel fuel prices (orange line) and The Fed’s inflation counterattack (red line). Sam and Sweet Caroline (who was seen walking free in NYC) must not have been monitoring how rapidly rising diesel prices would permeate the entire economy in terms of price increases. M2 Money YoY (green line) has been declining as the expectations of Fed rate tightening (red line) has increased.
SBF donated a huge amount to the midterm elections, the party that went along with Biden’s war on fossil fuels. Then inflation ensued as energy and food prices skyrocketed, leading The Federal Reserve to fight inflation by removing the monetary punchbowl. So, in a sense, SBF donations led to his own collapse.
Apparently, SBF, Caroline Ellison and the other FTXers were engaged in orgies and not paying attention to the impact of inflation and Fed policies on cryptos.
Lastly, how did Gary Genslar and the SEC not see any of this? In the same way that Fed Chair Ben Bernanke didn’t see the financial crisis as it was rapidly unfolding: eyes wide shut.
I read that Nicole Kidman underwent psychiatric treatment after filming “Eyes Wide Shut.” I saw it and was bored out of my mind.










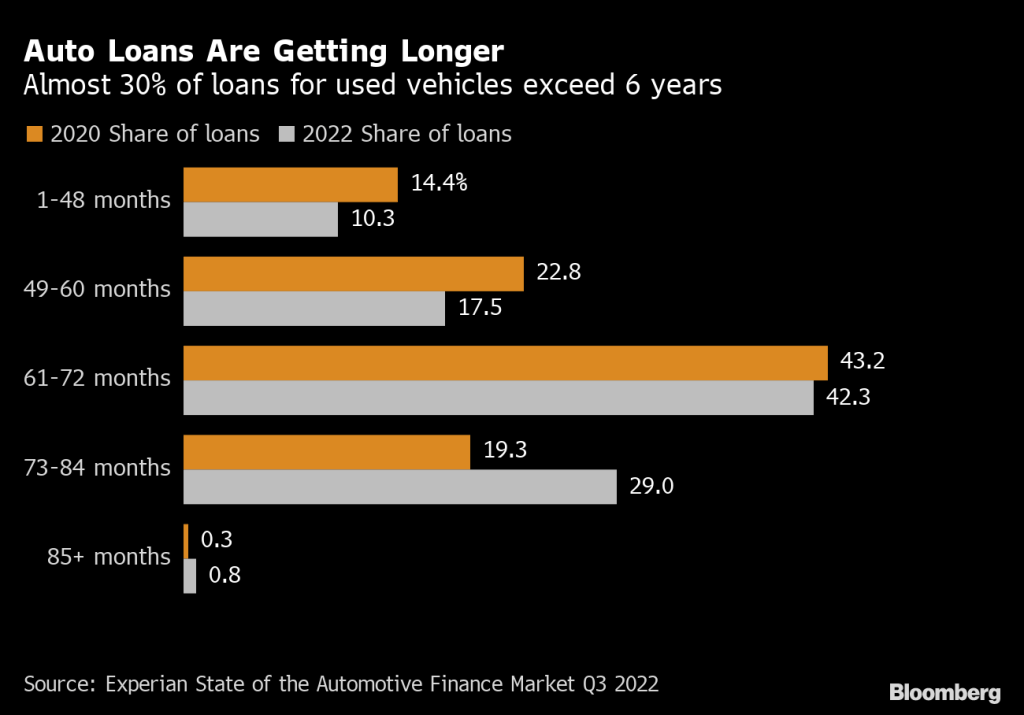










You must be logged in to post a comment.