Are You Ready? Banks Postitioned For A Bail-in As Silicon Valley Bank Fails (FDIC, Fed Weigh Special Vehicle After SVB Collapses, AOC Alert!)

Are you ready?

Despite cries from Summers, Yellen and other the DC illuminati (Biden is oddly silent), US banks are NOT fine. In fact, banks in general are suffering from Fed rates increases due to holding of long-term Treasuries and MBS.

In fact, The Federal Reserve’s fight against inflation is causing serious problems, as exemplified by AOC. No, not THAT AOC. but bank Accumulated Other Comprehensive Income.

Accumulated Other Comprehensive Income (AOCI) are special gains and losses that are listed as special items in the shareholder equity section of a company’s balance sheet. The AOCI account is the designated space for unrealized profits or losses on items that are placed in the other comprehensive income category.

On the regulatory call reports, AOCI is added to regulatory capital. Since SVB’s AOCI was negative (because of its unrealized losses on AFS securities) as of Dec. 31, it lowered the company’s total equity capital. So a fair way to gauge the negative AOCI to the bank’s total equity capital would be to divide the negative AOCI by total equity capital less AOCI — effectively adding the unrealized losses back to total equity capital for the calculation.

Getting back to our list of 10 banks that raised similar red margin flags to those of SVB, here’s the same group, in the same order, showing negative AOCI as a percentage of total equity capital as of Dec. 31. We have added SVB to the bottom of the list. The data was provided by FactSet:

Or this chart of vulnerable banks from Morningstar of unrealized losses and liquidity risk.

Here is a snapshot of SVB’s balance sheet. Or UNbalanced sheet.

After Congress passed the greatly flawed Dodd-Frank banking legislation, bailouts of banks are prohibited. But bank BAIL-INs still exist. Banks use money from their unsecured creditors, including depositors and bondholders, to restructure their capital to stay afloat. Put simply, they can convert their debt into equity to increase their capital requirements. Although depositors run the risk of losing some of their deposits, banks can only use deposits in excess of the $250,000 protection provided by the Federal Deposit Insurance Corporation (FDIC).

In any case, the FDIC and Fed are weighing a special vehicle after SVB swiftly collapses. Special vehicle? Sounds an awful like the mega bank bailout of 2008 under Hank Paulson.

No, not THIS AOC!

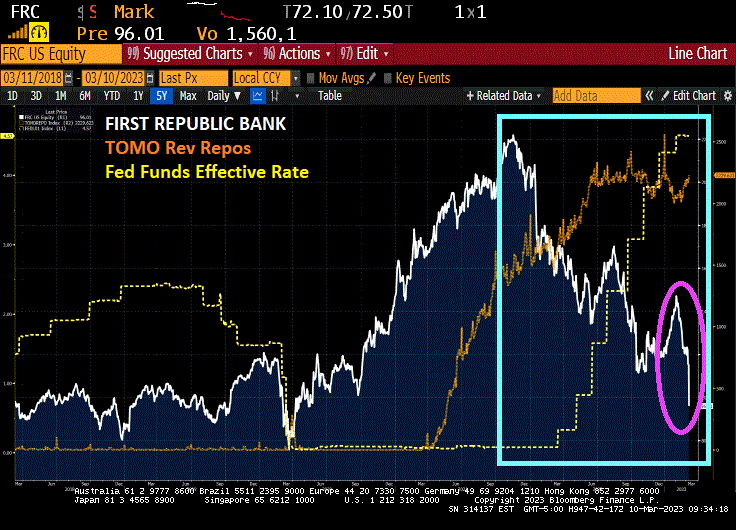
Bank Contagion? First SVB Crashes, Now First Republic Bank (Down -28% At Open)

Ah, memories! I still remember the 2000s housing bubble and subsequent financial crisis and bank bailout from 2008/2009 like it was yesterday. And I remember Representative Barney Frank (D-MA) claiming that the Dodd-Frank legislation would end bank bailouts. I laughed out loud when I heard Mr. Frank utter those preposterous words.

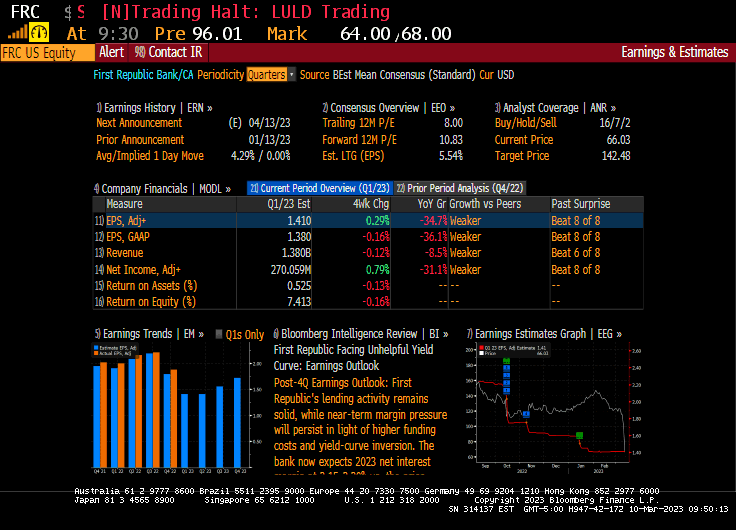
Now here we are again with yet another bank contagion. First it was Silicon Valley Bank, now it is First Republic Bank (down -28% at opening).

And there is a trading halt on First Republic. But YoY growth on FRC’s earnings of -34.7% is horrendous.

At least cryptobank Silvergate isn’t down as much as Silicon Valley Bank and First Republic Bank.

And the SPDR Regional Bank index is getting clobbered as Fed withdraws stimulus.

SVB’s management’s solution appears to have been to seek out yield through a lot of long-duration bonds. The bank started to lose deposits as VCs pulled cash/burnt through operating capital.

SVB’s CEO Greg Becker saw this coming and dumped his holdings.

Where were the regulators??

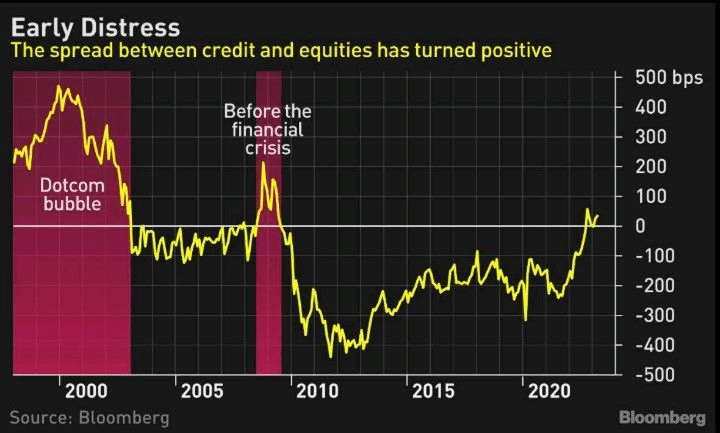
Hang ‘Em High! US Treasury 10Y-2Y Yield Curve Inverts To Near Lowest Since 1981, Credit/Equity Spread Turns Positive As Fed Tightens Monetary Noose

Hang ’em high!

As inflation remains persist (thanks to endless Fed stimulus and endless Federal spending splurges), we are seeing The Federal Reserve finally withdrawing the monetary stimulus (tightening the monetary noose). And with it, the US Treasury yield curve (10Y-2Y) goes down with it.

Another sign of distress is the spread between credit and equities which has turned positive as it does in times of crisis.

UPDATE! Recession predictor the US Treasury yield curve just went “red alert”, inverting to -100 basis points.

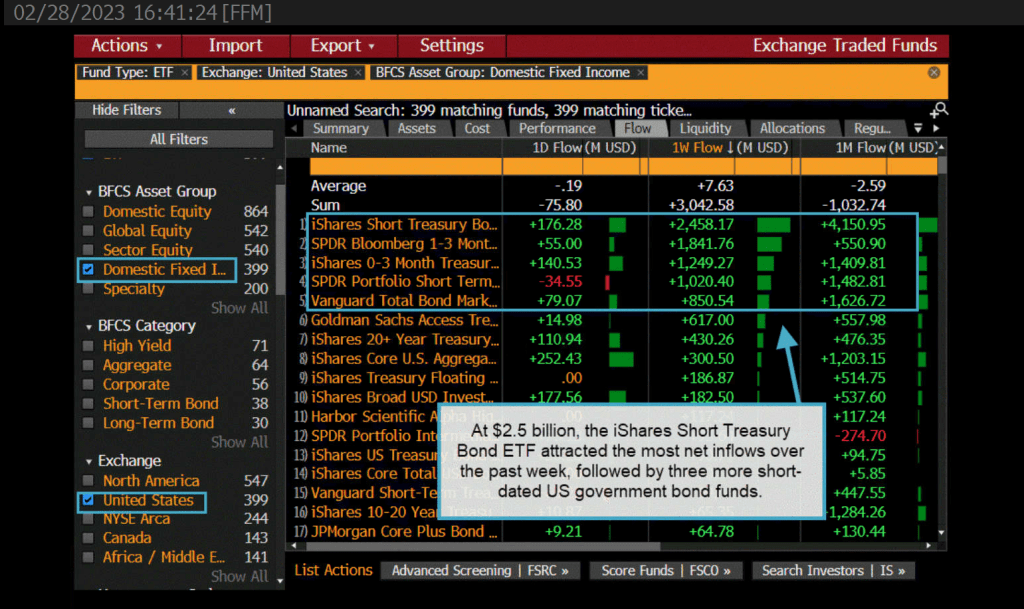
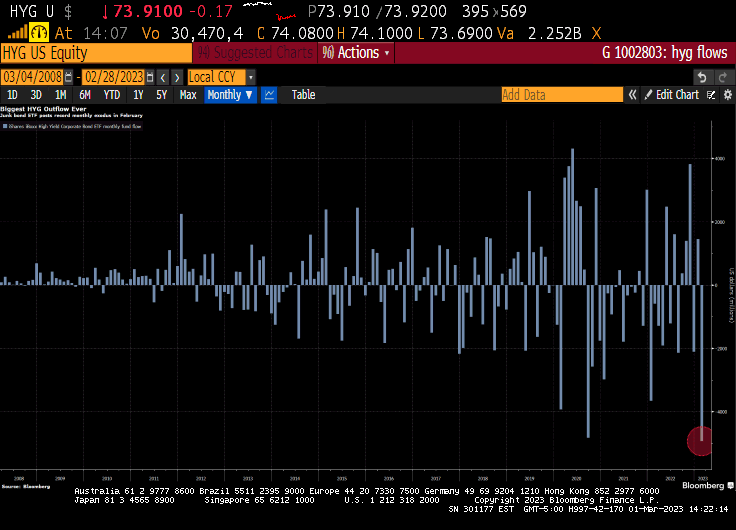
Dazed And Confused! Treasury Flows Show Bullish $2.5 Billion Shift to ST Sovereigns Versus S&P 500 (Credit ETFs Hammered by Record Outflows of Almost $12 Billion As Fed Worries About Inflation)

The Federal Reserve is dazed and confused about inflation.

As The Federal Reserve reaffirms their draining of the monetary punch bowl, we are seeing investors flock towards the bond market. Particularly the iShares Short Treasury ETF. $2.5 BILLION to be exact.

Meanwhile, credit ETFs are hammered by record outflows of almost $12 Billion.

The reason why? Inflation remains elevated which is leading The Fed to keep their foot on the monetary brake pedal.

I’m an economist.

Terminal Velocity! Fed Implied Terminal Rate Now 5.363% At July ’23 FOMC Meeting As US GDP Report Revised Lower On Weaker Consumer Spending In Q4 ’22 (GDP PRICE Index Revised UP To 3.9%)

Yesterday, we saw The Federal Reserve release the minutes of the last meeting. In a nutshell, The Fed is going to keep raising rates.

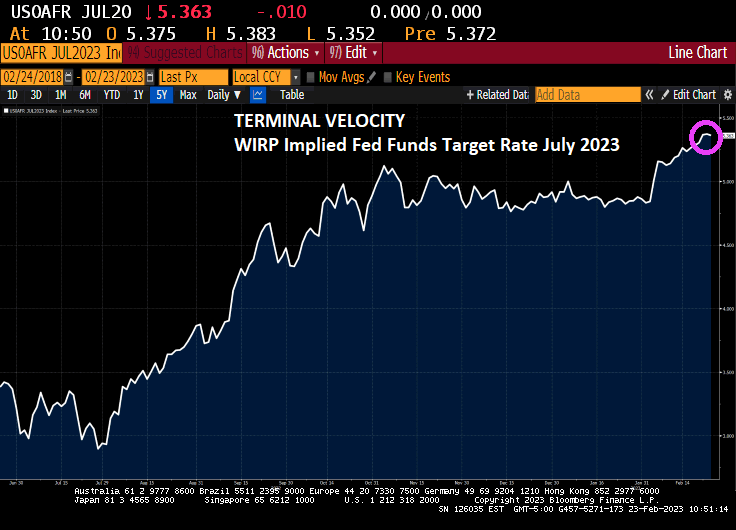
The terminal Fed Funds target rates is now 5.363% for the July FOMC (Fed Open Market Committee) meeting in 2023.

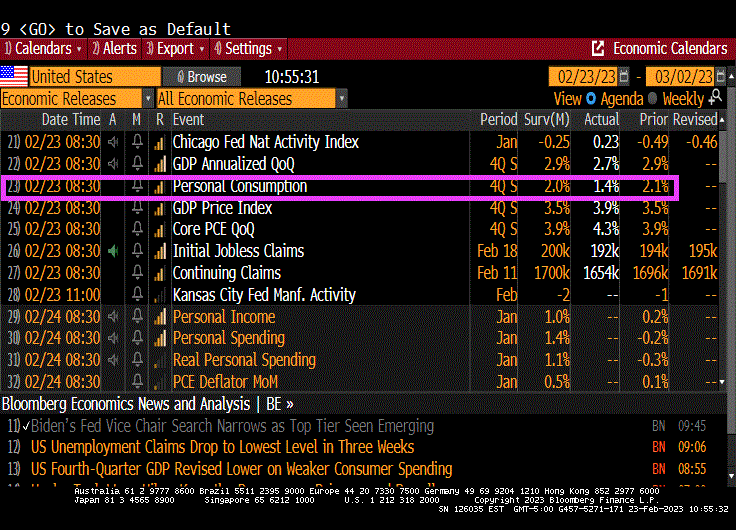
This comes as US Q4 GDP was revised lower on weaker consumer spending, revised downward to 1.4%

With the revision of Personal Consumption, real GDP was revised downward to 2.7% annualized QoQ.

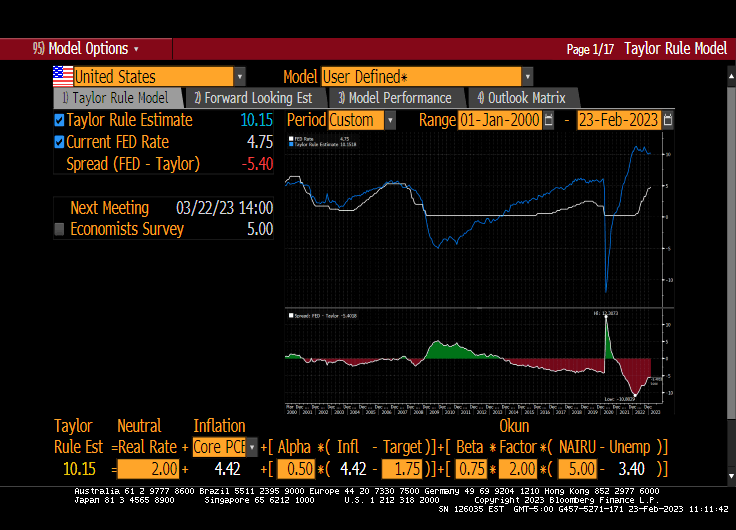
The Taylor Rule estimate for The Fed Funds Target rate is 10.15%. The Fed is only at 4.75%, so there is a long way to go! Except that The Fed doesn’t follow any useful rule like the Taylor Rule. Just the “seat of the pants” rule.

Don’t Be Misled By The Low US Unemployment Rate, It Goes Low Just Prior To A Recession (Treasury Curve Remains Deeply Inverted, Mortgage Rates Rise)

Biden’s State of the Union address saw him bragging about his record job creation (actually, it was the private sector, not Biden than created jobs) and historic unemployment rate. What Biden didn’t mention (along with not discussing the porous Mexican border with fentanyl pouring across or why he failed to shoot down a Chinese spy balloon until after it has passed over numerous military reservation) is that the unemployment rate always hit a low point just prior to a recession.

So, here we sit at 3.4% unemployment. But we also see the US Treasury yield curves (10Y-3M and 10Y-2Y) remaining deeply inverted.

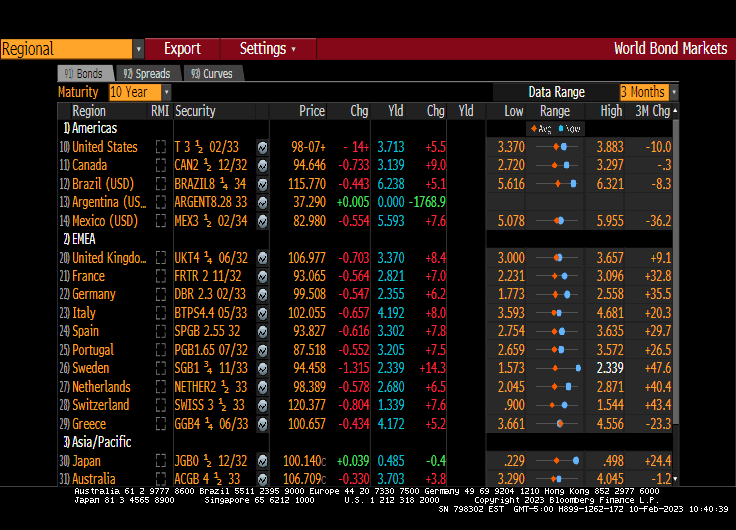
The US Treasury 10-year yield is up 5.5 basis points today.

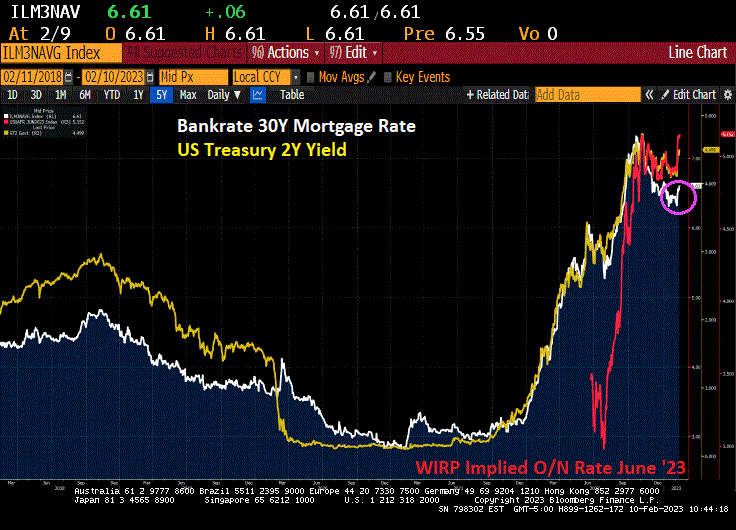
And Bankrate’s 30-year mortgage survey rate is up slightly today.

Help US, McCarthy! Price of Insuring Against US Debt Default Remains Elevated As No End In Sight (Effective Rate Of Interest On US Mortgage Rate Rises)

Everyone seems to have amnesia about Joe Biden’s hatred of Social Security and Medicare. He has tried to cut Social Security, Medicare and Veteran’s benefits as a US Senator. In addition, it was Biden that led the charge to TAX Social Security benefits for seniors. Now Biden has pivoted and is claiming that Republicans are the ones that want to cut Social Security. Wow. Biden simply goes where the political winds blow.

Here is where we set today. The cost of insuring for a US debt default remains elevated as the US has hit its statutory debt limit. This is happening at the effective rate of interest on US mortgage debt is rising.

Help us McCarthy! Because Biden and Schumer don’t want to cut ANY spending.

We need somebody like Mr. Garvey from Key and Peele to lead the debt ceiling debate.

But never fear! Congress LOVES to spend your money, so will eventually raise the debt ceiling.

Just Like The Fed! Despite Cooling Inflation, Forecasts Of Fed Rate Hikes Increase To Peaking In July 2023

It’s just like The Fed to ignore what is going on and do something else.

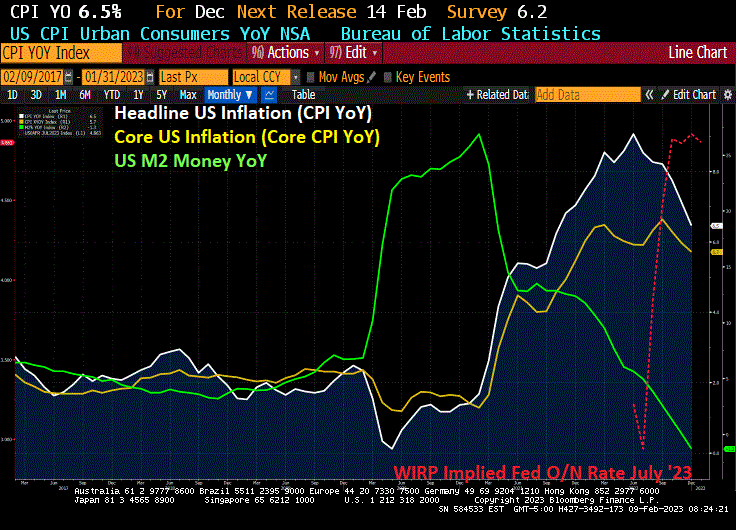
The one statement that Biden made in his State of the Union Address that was factually accurate was that inflation is coming down. Of course, he then blew it by saying he inherited inflation from Trump which was not true. Headline inflation (CPI YoY) was only 1.4% when Biden was sworn-in as President and rose to 9.1% YoY by June 2021 before finally starting to decline.

But despite the cooling of inflation (and M2 Money growth), The Fed seems hell bent on increasing their target rate, now forecast by Fed Funds Futures to peak in July 2023 at 5.123% before pivoting.

The Fed’s themesong. Drinking with my low-companions, dancing with a woman that’s not my wife, laughing at a joke I’ve heard before, welcome to a night in their life.

The Tighten Up! Banks Tightening Credit Boxes As Median Age Of US Homebuyers Rises From 31 To 47

The Federal Reserve is doing Archie Bell and The Drells “Do The Tighten Up!”

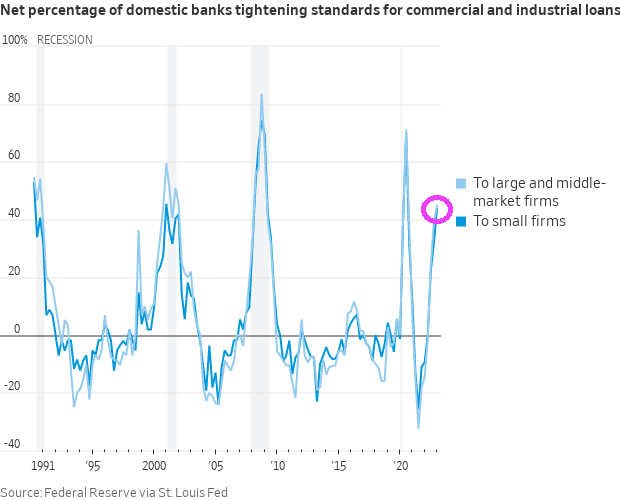
Over the fourth quarter, significant net shares of banks reported having tightened standards on C&I loans to firms of all sizes.

Banks also reported having tightened all queried terms on C&I loans to firms of all sizes.

Actually, banks are tightening standards across the various credit boxes.

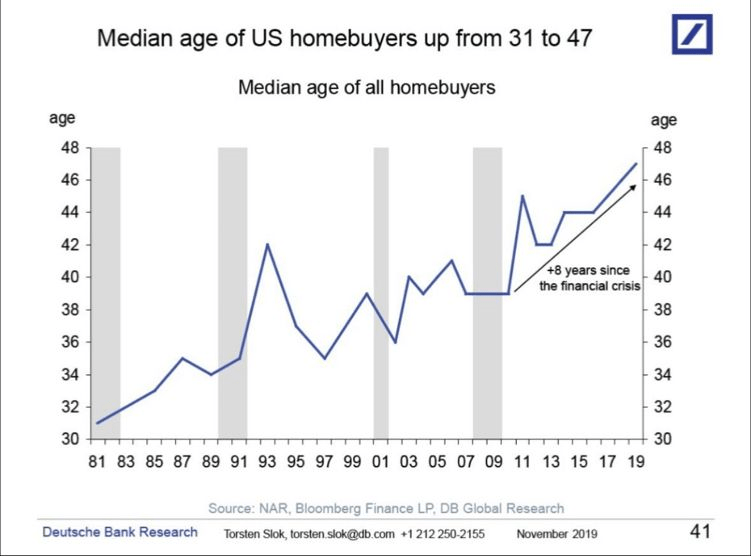
And as banks tighten up their credit box, we are seeing the median age of US homebuyers rising from 31 to 47 years.

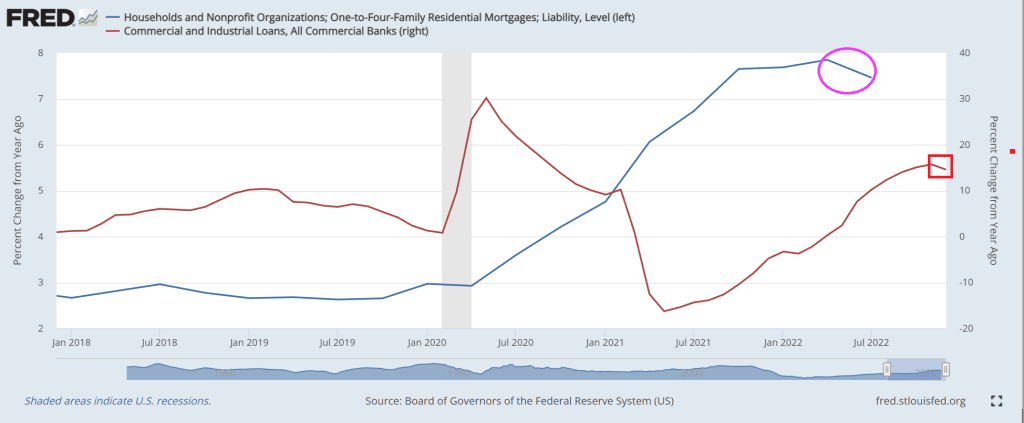
As banks tighten, we are seeing a slow down in the growth rate for C&I lending and 1-4 unit mortgage lending.

This is reminding me of Germany where you save for your entire life to buy a home.

Somehow, I don’t think Biden will mention any of this is his State of the Union address tonight.

Just Like The Fed! M2 Broad Money Supply Growth Falls To -1.8% YoY, M1 Money Growth Falls To -3.6% YoY As US Job Layoffs Accelerate

Its just like The Federal Reserve to be cutting US money growth as US jobs cuts accelerate.

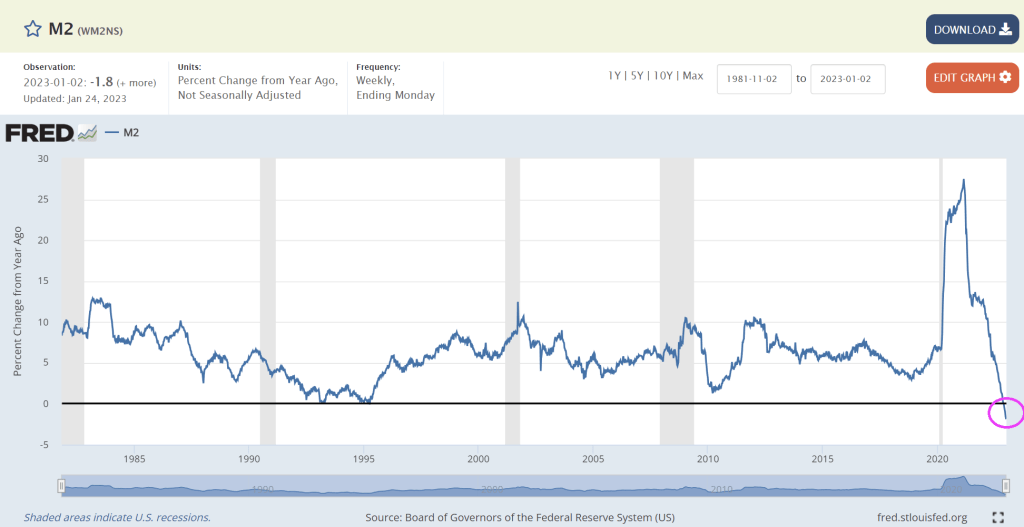
The latest US money growth numbers are out and they are daunting. M2 Money growth YoY is now negative at -1.8%.

M1 money, a narrower defition of money, is now down -3.6% YoY.

This is happening as the labor market is seeing a wave of layoffs.

As M2 growth YoY and The Fed balance sheet shrinks, so does Cathie Wood’s AARK.

We are just the stepping stone for The Fed.

As The Fed ponders inflation versus job growth, its a case of “Him or Me, What’s it going to be?”