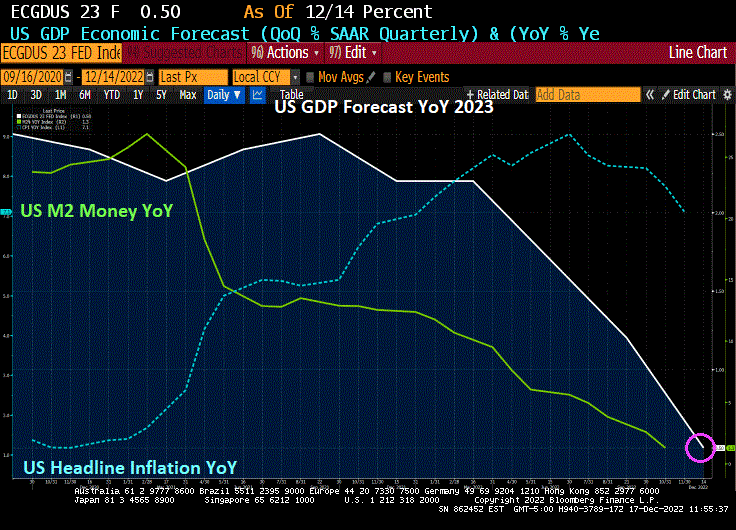
The Federal Reserve forecast for the US economy is a dismal 0.50% YoY. Do I detect a trend?
The FOMC forecast for 2023 and 2024. Core PCE YoY (inflation) is forecast to drop to 3.50%, still considerably higher than The Fed’s target rate of inflation of 2%. And unemployment is forecast to be 4.60%.
To cope with Bidenflation, US personal savings rate as of October is -67.9% YoY. The “good” news is that rents YoY are crashing. But food prices under Inflation Joe remain very high. But most everything is slowing down, not due to Biden’s policies, but a global and US economic slowdown.
With a big slowdown coming our way, you can understand why The Fed’s December Dot Plot is showing declining Fed Funds Target rate starts declining in 2024.
Even US mortgage rates are headed down.
Speaking of going down, cryptos are down across the board with Cardano leading the decline at -6.91%.
Apparently, despite the denials from the Biden Administration, someone at Bureau of Labor Statistics or someone in Congress or the Federal Reserve or the Biden Admininstration itself likely tipped the wink on the soft CPI report on Tuesday.
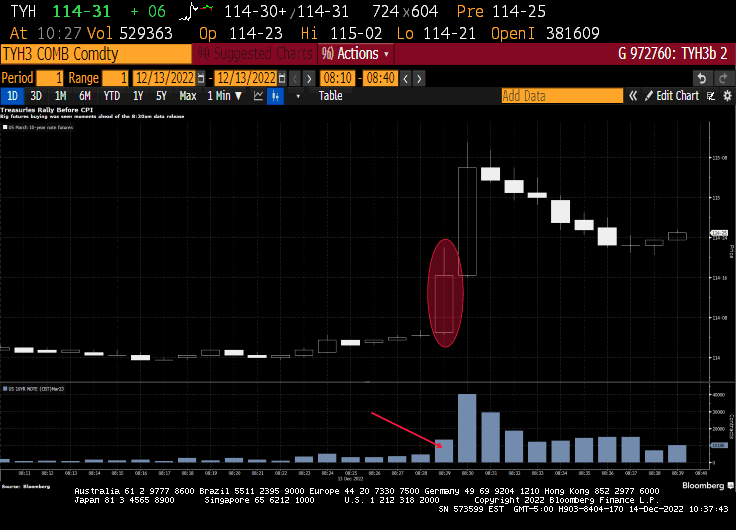
Treasuries were well on the front-foot in the lead up to the below-estimate November CPO print, as a surge of buying took place seconds before the official 8:30 am New York release time. Over a 60 second period before the data, 13,518 March 10-year futures traded as the contract moved from 114-04+ up to 114-22. Gains were then extended up to 115-11 session highs once the data was released.
On the equity side, stock futures suddenly spiked more than 1%. Trading in Treasury futures surged, pushing benchmark yields lower by about 4 basis points. Those are major moves in such a short period of time — bigger than full-session swings on some days. And they should get scrutinized by regulators, long-time market observers say, even if a leak is only one of several possible explanations for why traders suddenly started buying right before the report was published.
Remember that current Treasury Secretary Janet Yellen was accused of leaking information to a NY hedge fund ahead of the Fed Open Market Committee meeting? And then we have the Wolf of Wall Street.
I wonder if the REAL Wolf of Wall Street did this?
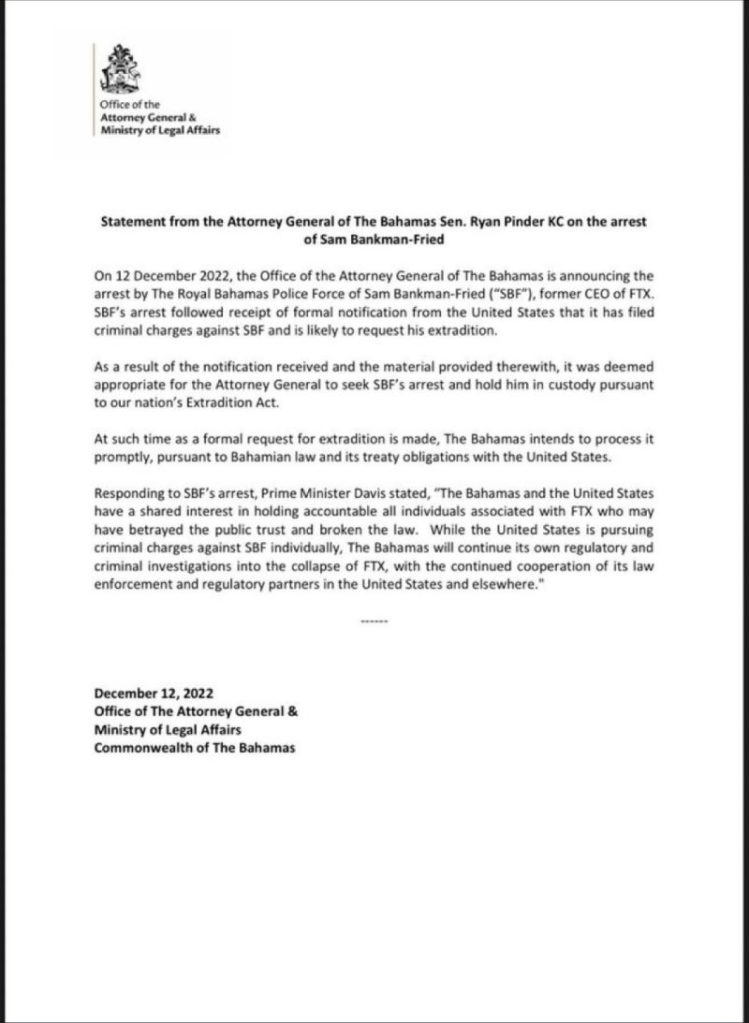
First, Sam Bankman-Fried agreed to testify in the House Financial Services Committee meeting on December 13, 2021. Then Bankman-Fried said he would testify remotely. Then ,,, he was arrested by the Bahama’s police. How convenient!
WASHINGTON, Dec 12 (Reuters) – Sam Bankman-Fried, the founder and former CEO of now-bankrupt crypto exchange FTX, on Monday said he would testify remotely at Tuesday’s U.S. House Financial Services Committee hearing to examine the collapse of the company.
FTX filed for U.S. bankruptcy protection last month and Bankman-Fried resigned as chief executive, triggering a wave of public demands for greater regulation of the cryptocurrency industry.
That might be kind of difficult, since Sam Bankman-Fried has been arrested in the Bahamas.
Perhaps, The SEC Gary Genslar will testify as to why he met with SBF and gave him the green light for his trading? And why did Genslar erase Hillary Clinton from his schedule after meeting with her? And why was Genslar meeting with Hillary in the first place since she is now just an American cititzen??
Will SBF be extricated by tomorrow morning hearing time?
Central bankers won’t ride to the rescue when growth slows in this new regime, contrary to what investors have come to expect. They are deliberately causing recessions by overtightening policy to try to rein in inflation. That makes recession foretold. We see central banks eventually backing off from rate hikes as the economic damage becomes reality. We expect inflation to cool but stay persistently higher than central bank targets of 2%.
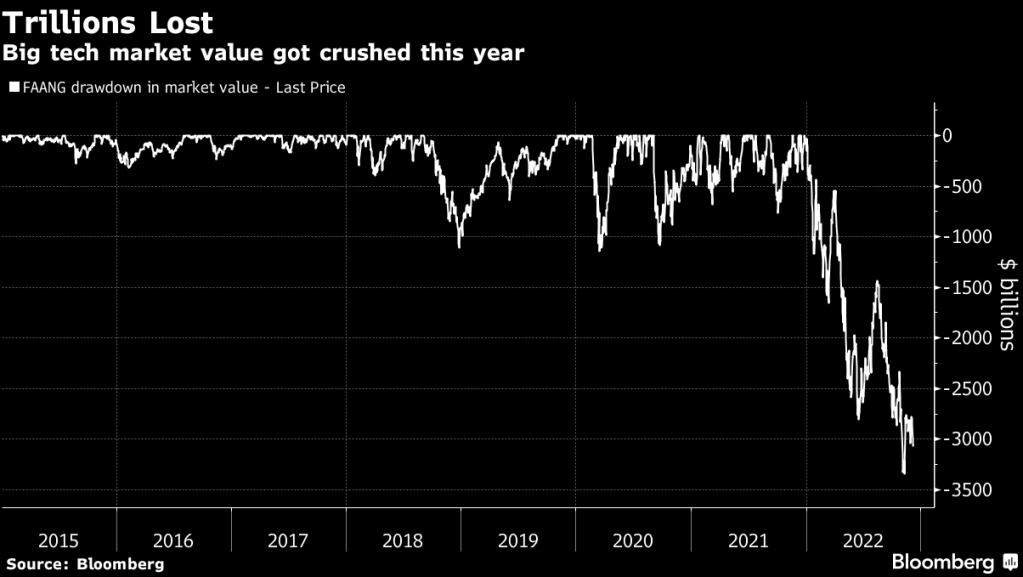
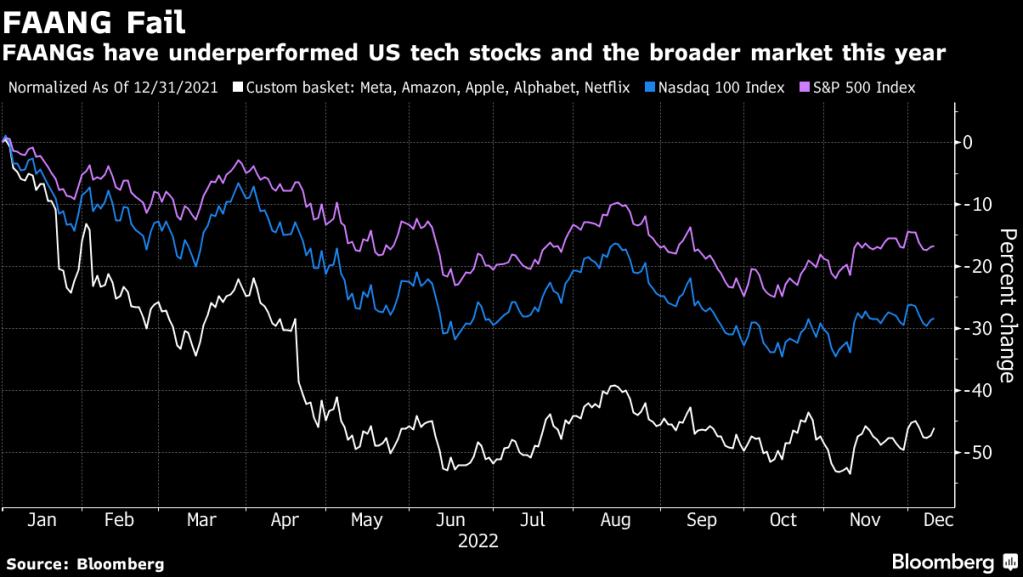
For some investors, this year’s rout in high-flying technology stocks is more than a bear market: It’s the end of an era for a handful of giant companies such as Facebook parent Meta Platforms Inc. and Amazon.com Inc.
Those companies — known along with Apple Inc., Netflix Inc. and Google parent Alphabet Inc. as the FAANGs — led the move to a digital world and helped power a 13-year bull run. And FAANG drawdown have reached over $3 trillion.
FAANGs (Meta, Amazon, Apple, Alphabet, Netflix) are getting clobbered in 2022.
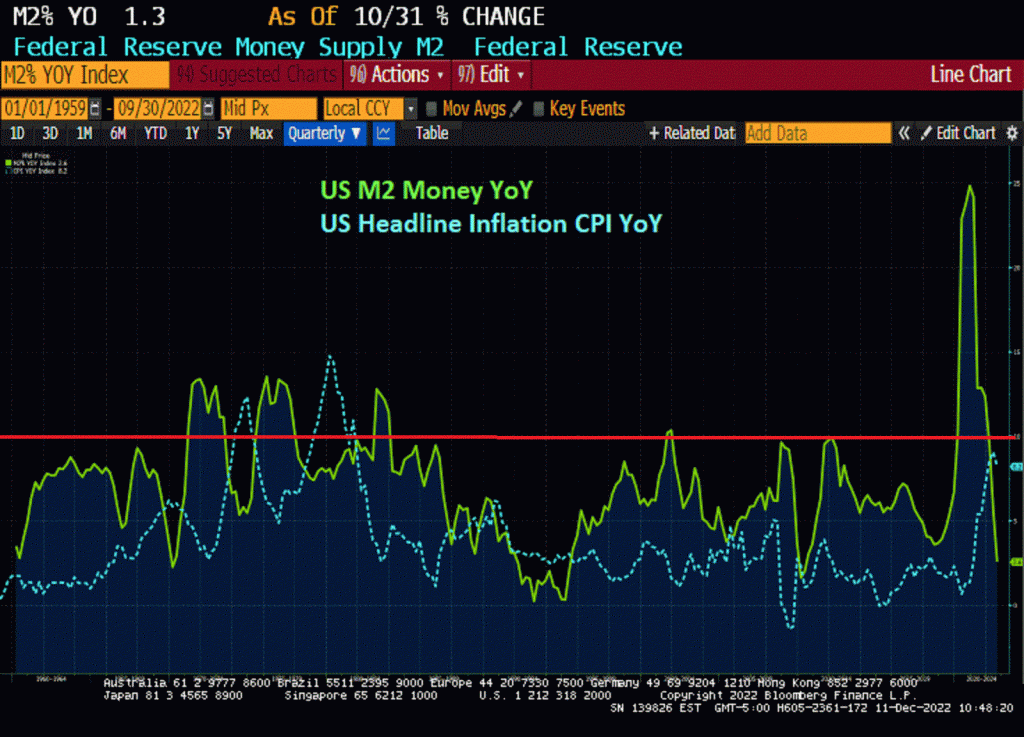
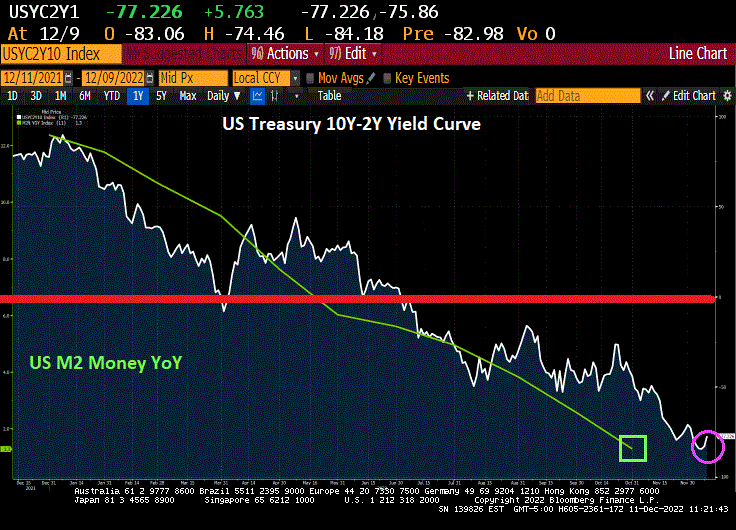
Typically, when The Fed prints too much money, such as 10% or higher (red line), inflation follows. Particularly when The Fed prints at 25% YoY in Q4 2020, it was followed by the highest inflation rate in 40 years. But if M2 Money continues to slow, inflation will likely slow, but not to The Fed’s target of 2%.
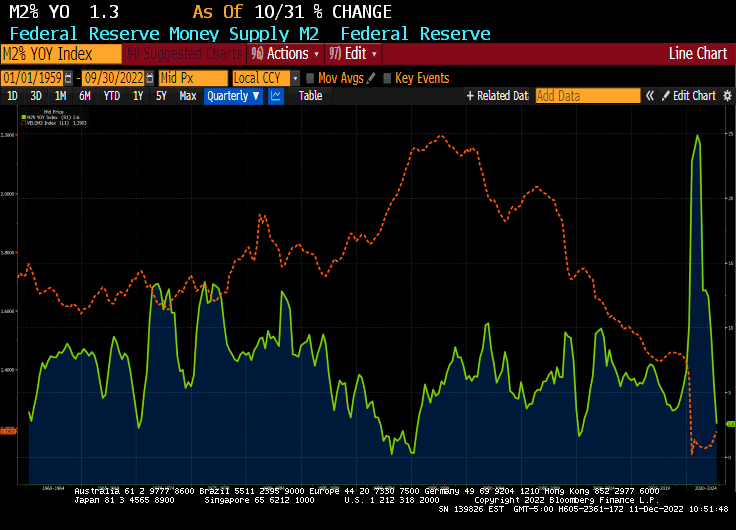
Despite what Minneapolis Fed’s Neal Kashkari said about The Fed having infinite printing resourses, The Fed is going to fight inflation THAT THEY HELPED CAUSE. Biden’s energy policies (did you see that Elon Musk has a car that uses plentiful hydrogen?), and excessive Federal spending by Biden/Pelosi/Schumer, are culprits in creating the supply chain problems facing America. BUT after the 25% surge in M2 Money in 2020 and 2021, we saw M2 Money VELOCITY crash and burn to its lowest level in history. Which means the “bang for the buck” for printing more money is negligible.
Of course, big tech firms got caught influencing the 2020 Presidential election (see Musk’s release of Twitter files) and engaged in restriction of the 1st Amendment (Freedom of Speech). How much will that impact FAANG stocks going foward?
And yes, the US Treasury yield curve is inverted pointing to a recession in 2023.
And yes, apparently Biden was complicit in the Twitter fiasco.
The good news for Americans? The global slowdown is helping to lower US Treasury yields which, in turn, helps to help to lower US mortgages rates. Kind of a perverse “good news” story when you think about it.
The bigger picture is the slowdown caused by 1) a global economic slowdown and 2) the tightening of Fed monetary policy to fight inflation.
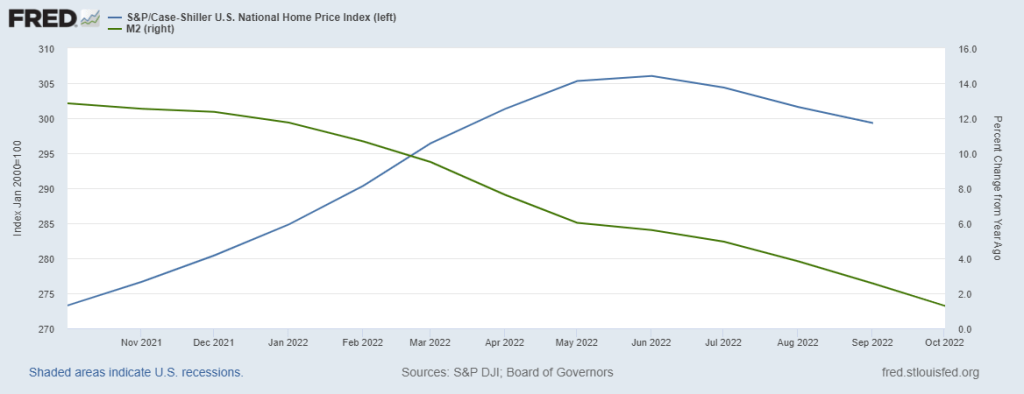
Look at the Case-Shiller national home price growth YoY (blue line) against M2 Money growth YoY (green line). Just move the green line to the right and it covers home price growth. Both are slowing down with anticipated Fed rate hikes (red line) now at 50 basis points for the December 14th FOMC meeting. And note that The Fed’s balance sheet (orange line) has barely budged.
Unlike Archie Bell and the Drells, this tighten-up is about The Federal Reserve tightening-up its monetary policy.
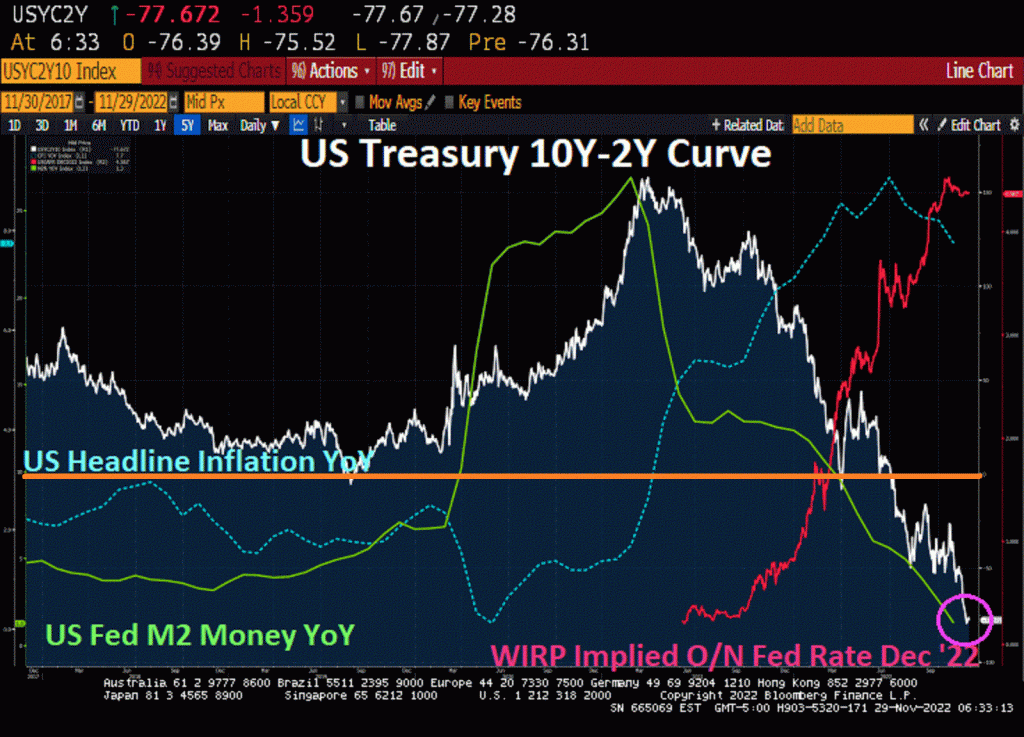
On December 31, 2021, the US Treasury yield curve (10Y-2Y) stood at +77.4 basis points, generally a good omen.
Then markets woke up. And not in a woke way.
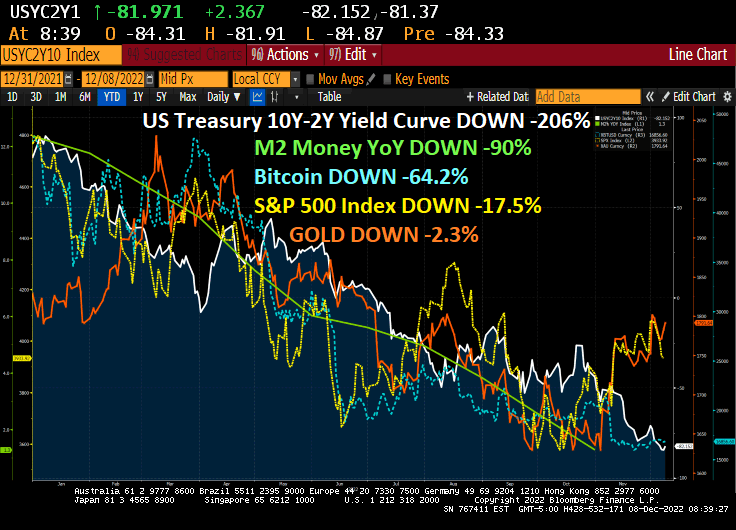
As The Fed tightens to tamp down on inflation in 2022, we are seeing a pattern. The US Treasury 10Y=2Y yield curve has sunk to -82 basis points, a -206% decline.
In addition to the inversion of the US Treasury yield curve we have witnessed M2 Money growth declining -90%, the S&P 50) index down -17.5%, Bitcoin down -64.2% and gold down only -2.3%.
But we now have to worry about Project Cedar, a seemingly innocent project to replace the US Dollar. A new digital currency would allow Washington DC to monitor your purchases and behavior. And perhaps create a Social Credit Score like in China measuring how well you conform to Biden’s notion of a utopian, green society.
And the US yield curve has been inverted for 109 straight days.
Yes, The US Treasury 10Y-2Y yield curve remains inverted, for the 104th straight day. And Bankrate’s 30-year mortgage rate has dropped -57 basis points since November 3, 2022.
This comes after a gruesome Pending Home Sales and mortgage applications reports today.
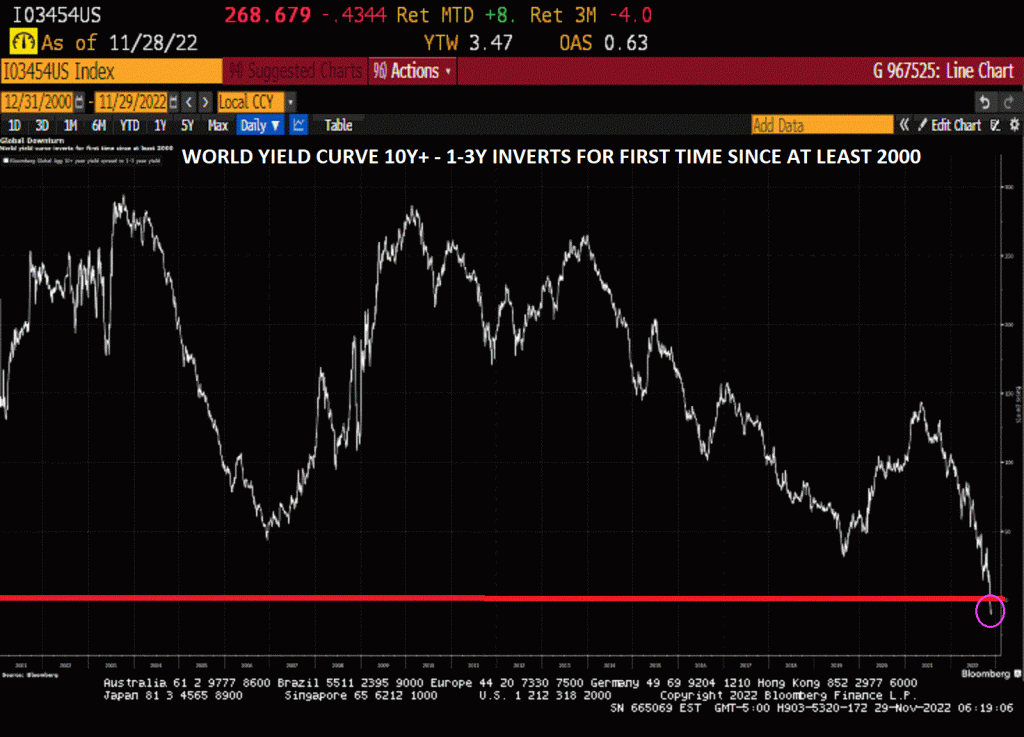
The hawkish drumbeat from central bankers is raising fears of a downturn, with global bonds joining US peers in signaling a recession, as a gauge measuring the worldwide yield curve inverted for the first time in at least two decades.
The US Treasury 10Y-2Y yield curve, on the other hand, has been inverted for 107 straight months.
And in Europe, 10-year sovereign yields are dropping like a paralyzed falcon.
The world and US yield curves are pointing to trouble. And drums along the Potomac (DC) and East River (NYC).









You must be logged in to post a comment.