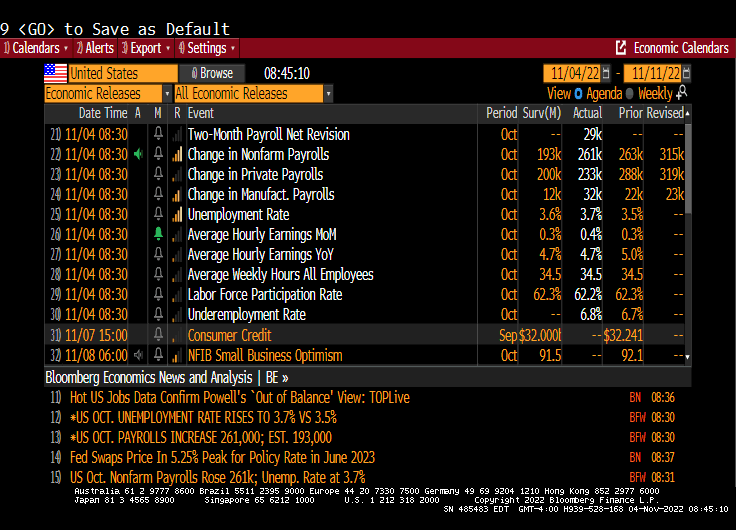
Private payrolls added 233k jobs in October, which is a -27% decline from September’s revised private payroll figures.
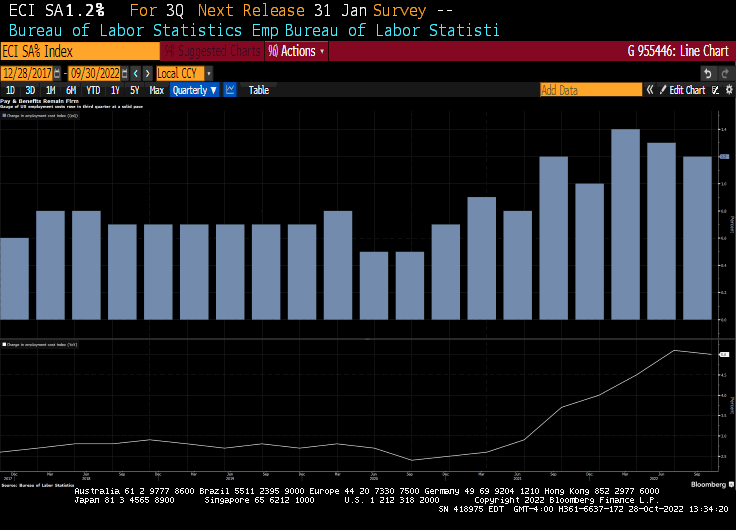
The good news? Average hourly earnings growth is still positive, but fell to 3.7% YoY. But with inflation raging at 8.2% YoY, workers are getting clobbered by inflation.
Here is the rest of the story.
The Fed is now green-lighted to raise rates even higher.
Biden’s campaign promise was to unite rather than divide. But Biden has morphed into Gustaf Holst’s, Mars – Bringer of War! Both domestically and in the Ukraine.
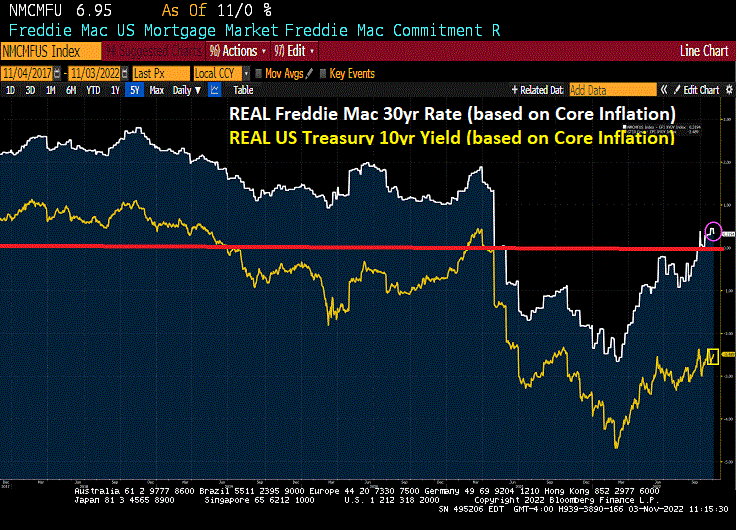
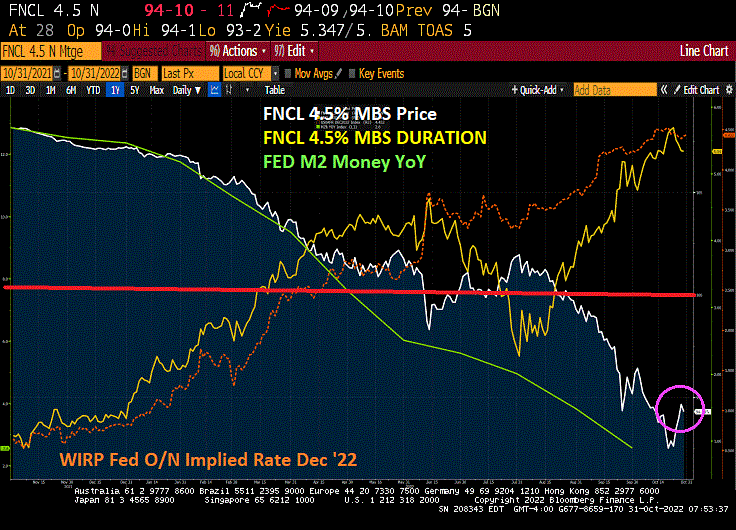
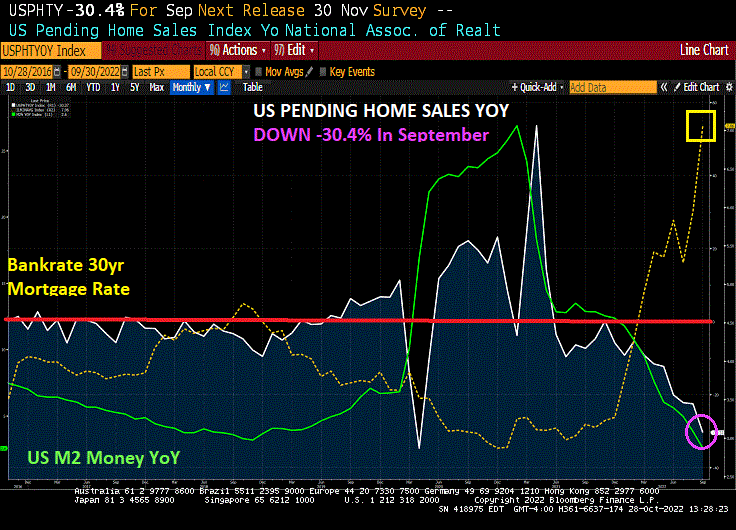
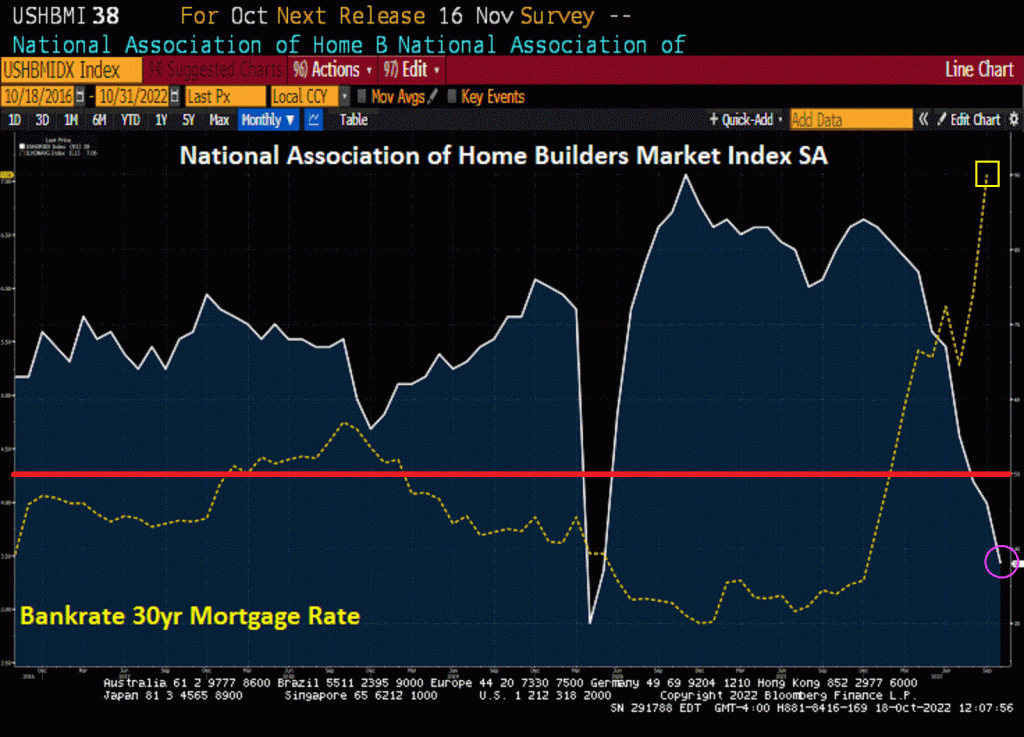
It has been a wild and mostly negative ride under Biden’s Reign of Error. 40-year highs in inflation (caused by Biden’s fossil fuel mandates and Federal spending) have left the US mortgage market FINALLY seeing positive REAL mortgage rates (now 0.32%), even though the REAL 10yr Treasury yield is still negative (-2.50%).
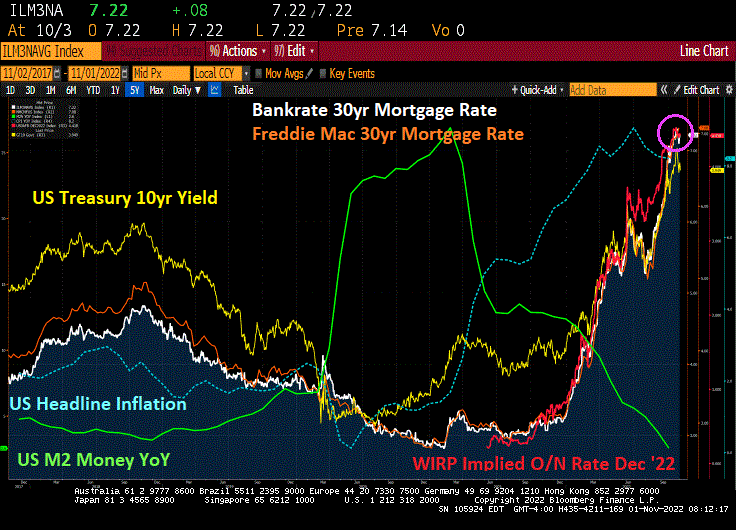
US 30-year mortgage rates are above 7% as The Federal Reserve slowly withdraws its Covid-related monetary stimulus and attempt to combat near 40-year highs in inflation under Biden (aka, Bidenflation).
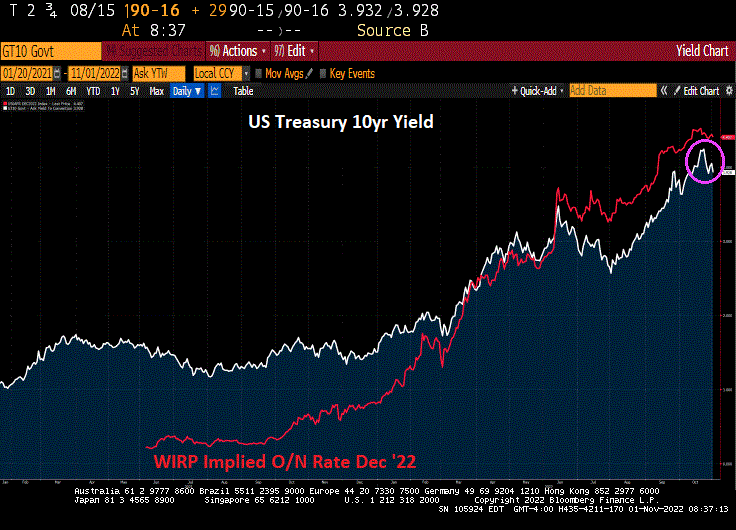
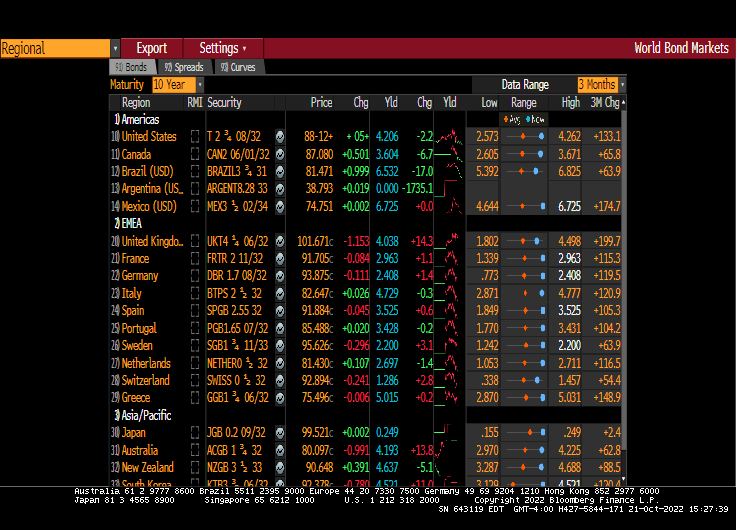
However, the US Treasury 10-year yield is down -12 basis points this morning.
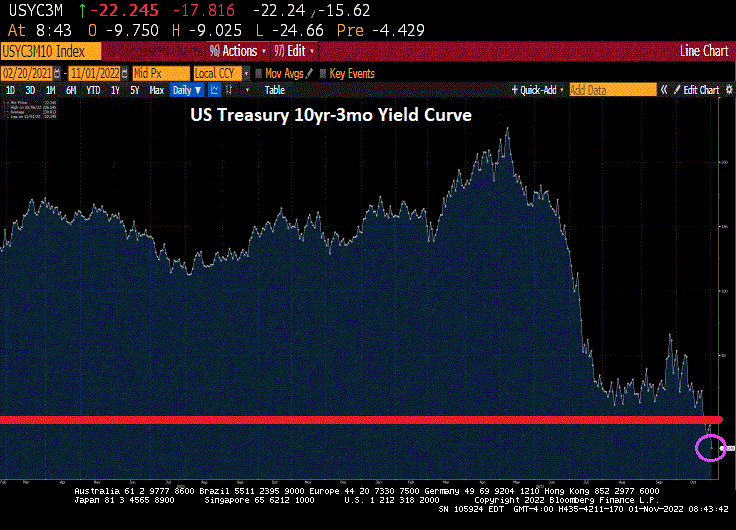
And we have an important predictor of recession, the Treasury 10yr-3mo yield curve.
And if the Republicans win The House (and maybe the Senate) at the midterms, Biden can blame Republicans for the recession.
The next Federal Reserve Open Market Committee (FOMC) meeting in on Wednesday, November 2nd. Let’s see what The Fed does with its BIG GREEN BAG … OF MONEY.
As I set here on Sunday morning waiting to see how the Cleveland Browns will lose to cross-state rival Cincinnati Bengals, I see that both the US Treasury 10yr-2yr and 10yr-3mo yield curves are inverted (below zero).
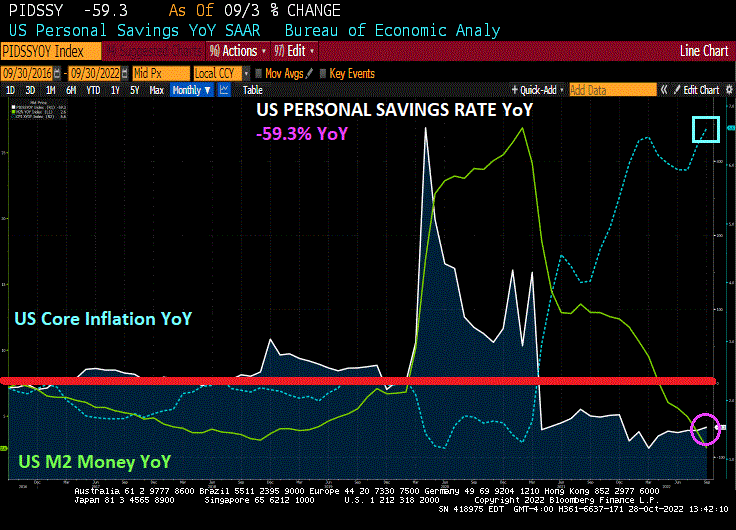
Core inflation (CPI less food and energy) YoY (blue line) was only 1.3% in February 2021 shortly after Biden was sworn-in as President and is now 6.6% in September 2022. That is over a 400% increase in core inflation!
We have this tantalizing headline on Bloomberg:
Goldman Sachs Now Sees Fed Rates Peaking at 5% in March By Simon Kennedy(Bloomberg) —
Goldman Sachs Group Inc. economists said they now expect the US Federal Reserve to raise interest rates to 5%, higher than previously predicted.
The central bank will lift its benchmark rate to a range of 4.75% to 5% in March, 25 basis points more than earlier expected, economists led by Jan Hatzius wrote in an Oct. 29 research report.
The route to the new peak includes increases of 75 basis points this week, 50 basis points in December and 25 basis points in February and March, they said.
The economists cited three reasons for expecting the Fed to hike beyond February: “uncomfortably high” inflation, the need to cool the economy as fiscal tightening ends and price-adjusted incomes climb, and to avoid a premature easing of financial conditions.
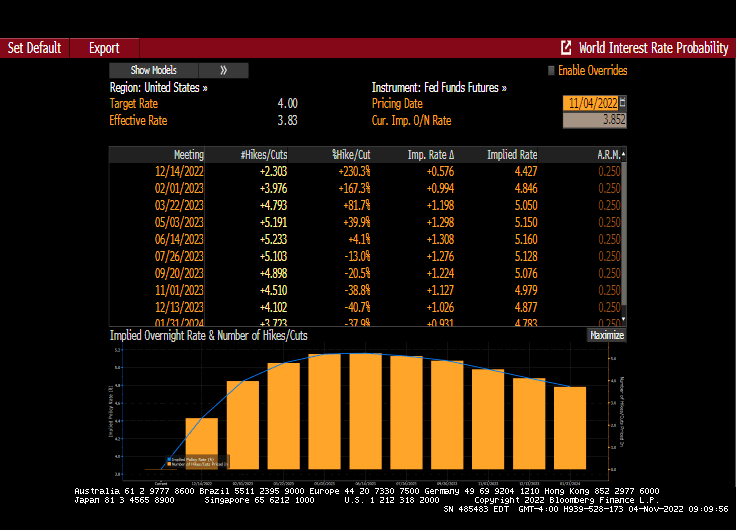
Well, not exactly earth-shattering. Fed Funds Futures data point to a peak of near 5% (4.905%) for the May 2023 FOMC meeting, so Goldman Sachs is calling for an earliest peak at the March 2023 FOMC meeting,
Regardless of what Goldman Sachs thinks, Fed officials are expecting a peak in 2023 followed by a decline to 2.5%.
Brainard and Bostic are the only “doves.” Which is silly because Chicago’s Evans is a perma-dove. Let’s see how the Dots Plot changes at the November 2nd meeting.
America’s distressed debt pile is biggest since September 2020.
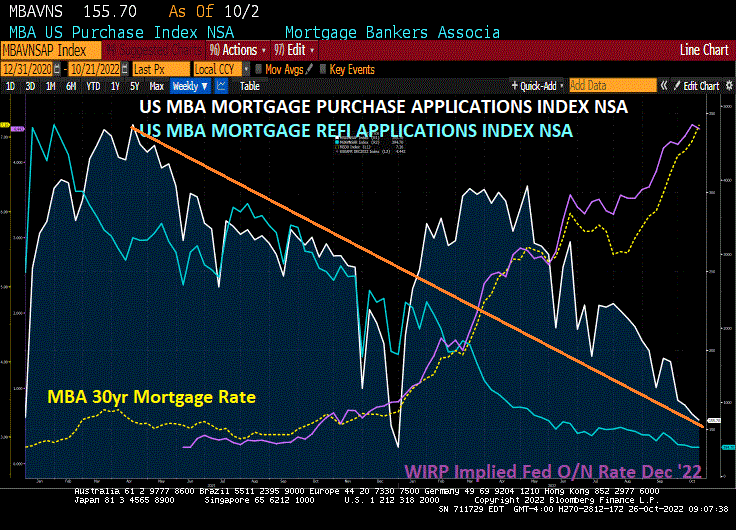
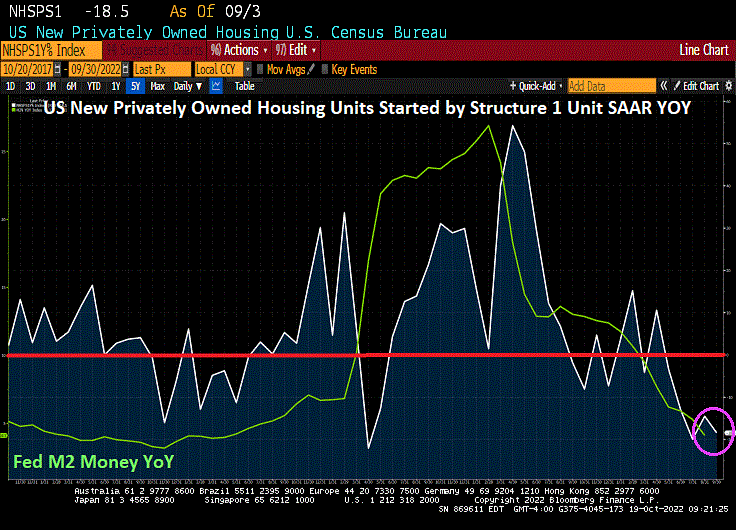
As The Federal Reserve continues to withdraw its massive Covid-related monetary stimulus, US mortgage applications continue to fall to the lowest level since 1997.
Mortgage applications decreased 1.7 percent from one week earlier, according to data from the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey for the week ending October 21, 2022.
The Refinance Index increased 0.1 percent from the previous week and was 86 percent lower than the same week one year ago. The seasonally adjusted Purchase Index decreased 2 percent from one week earlier. The unadjusted Purchase Index decreased 3 percent compared with the previous week and was 42 percent lower than the same week one year ago.
Under Biden, we have seen (orange line) a significant decline in mortgage purchase applications (peak 2021 to this week). Mortgage rates are the highest since 2001 (wait for it!)
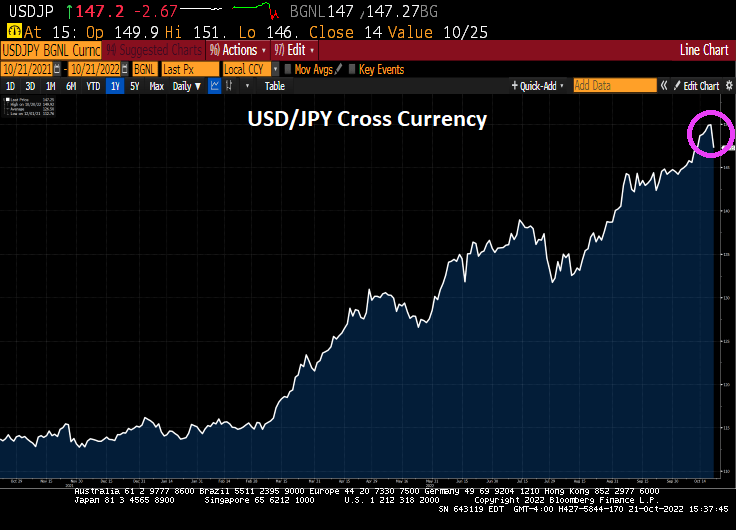
Wall Street saw another day of stunning reversals, with stocks rallying after a Treasury selloff sputtered. The yen jumped as Japan intervened again to prop up the currency.
After many twists and turns, the S&P 500 pushed solidly into the green and headed for its best week since June as 10-year yields fell from the highest since 2007.
Probably because The Fed is likely to pivot with impending recession. The Dow is up 774 points this Friday. And today was a huge option expiration day!!
And the 10-year Treasury yield fell -2.2 basis points.
Here is the result of Japan’s intervention.
But today’s numbers were largely monthly stock index option expiration.
Why did it fall upon Powell to be the wielder of the Fed tightening scimitar? Why didn’t Yellen? Because “Good Girls Don’t.” But Powell did.
Have a nice weekend. I will be rooting for Ohio State to annihilate the Iowa Hawkeyes at noon on Saturday.











You must be logged in to post a comment.