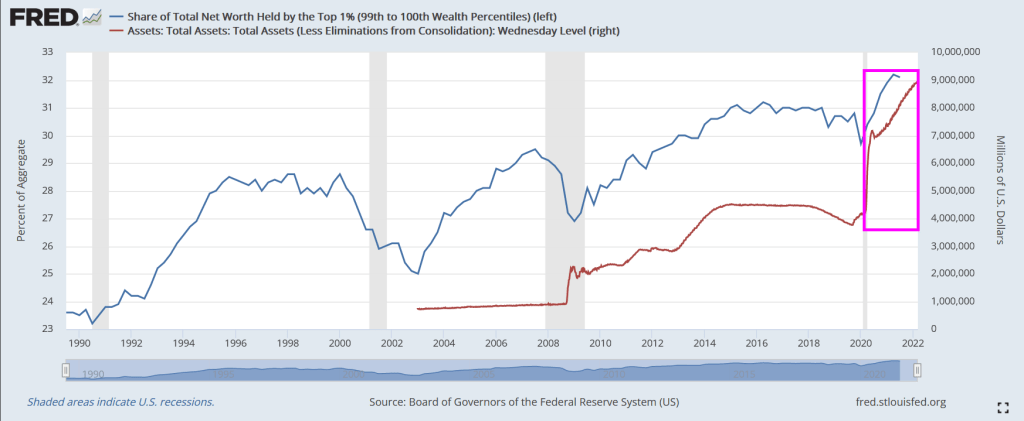
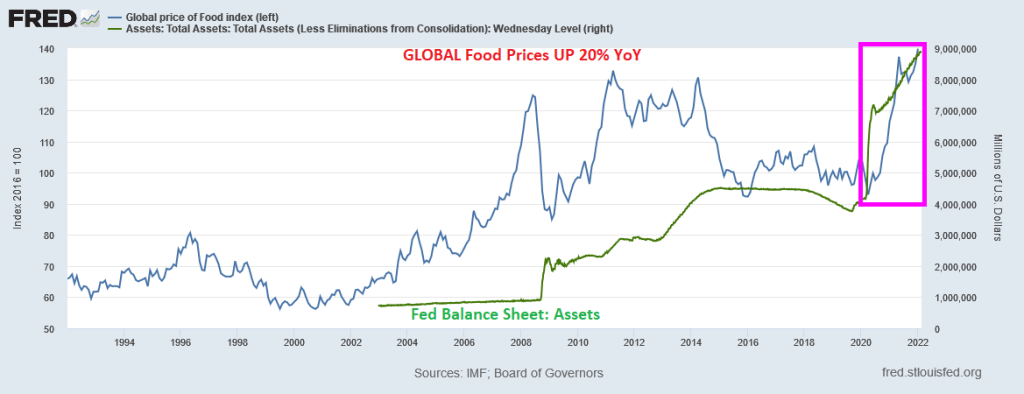
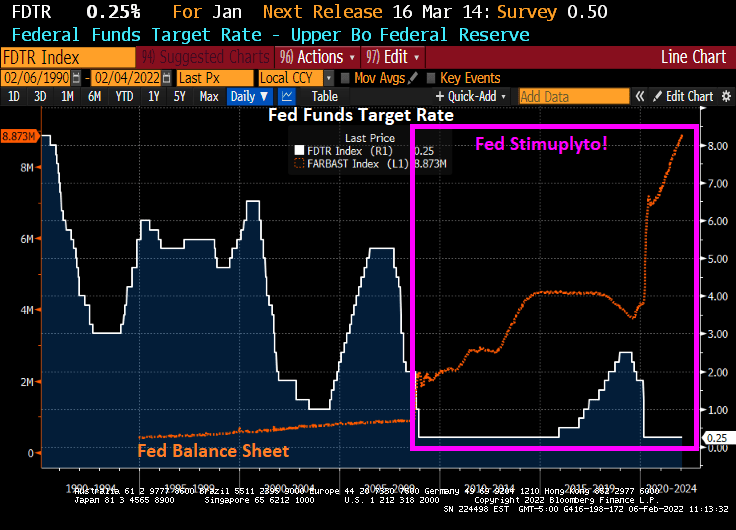
Following the financial crisis of 2008/2009, The Federal Reserve began their dramatic purchase of assets such as Treasuries and Agency mortgage-backed securities (AgencyMBS). And then Covid struck and The Fed went berserk with asset purchases.
So, who benefited the most? The top 1% or the bottom 50%?
Answer? The top 1%. The share of total net worth spiked dramatically after the Fed infusion.
Even the bottom 50% benefited with The Fed’s Covid stimylpto, but no where near how the top 1% benefited.
World Economic Forum’s elitist Klaus Schwab approves of this message!
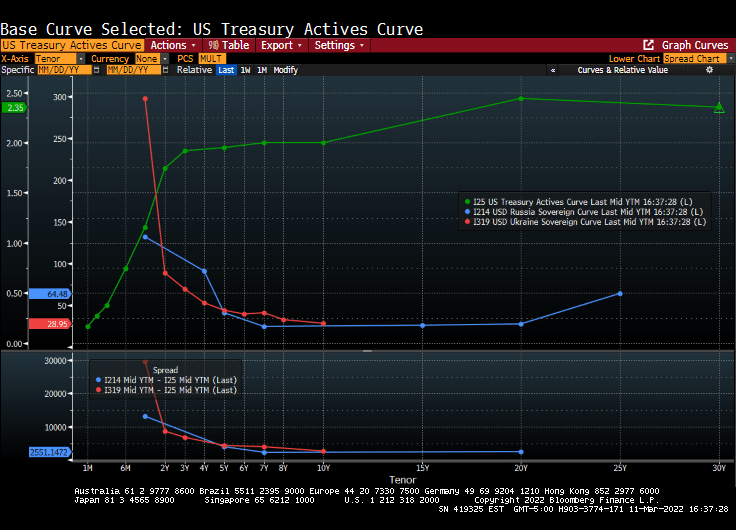
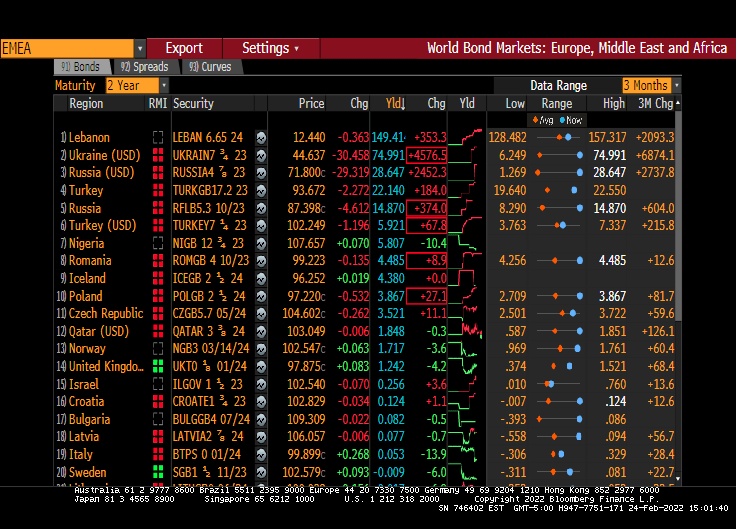
On an unrelated note, the US Treasury yield curve is strongly UPWARD sloping, while Russia’s and Ukraine’s yield curves are inverted and collapsing.
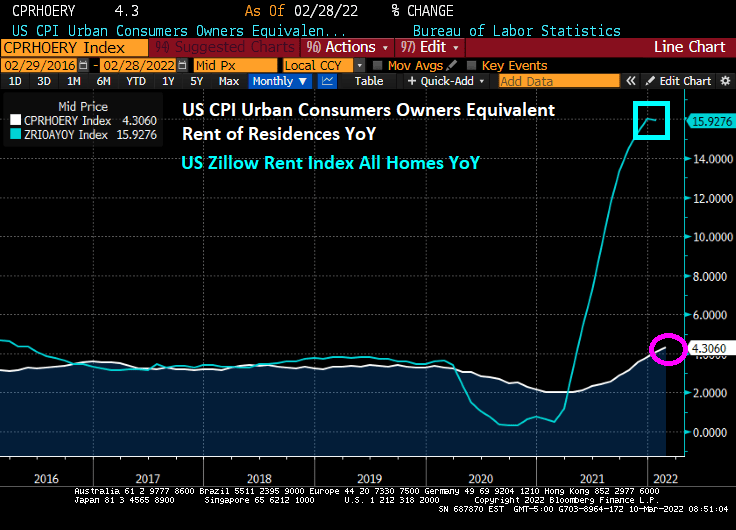
US rent inflation (owner’s equivalent rent of residence YoY) surged to 4.30%. However, Zillow’s rent index last month was 15.93% YoY.
But if we look at US Monthly Rent YoY, we see that rents are climbing at a 17.6% rate.
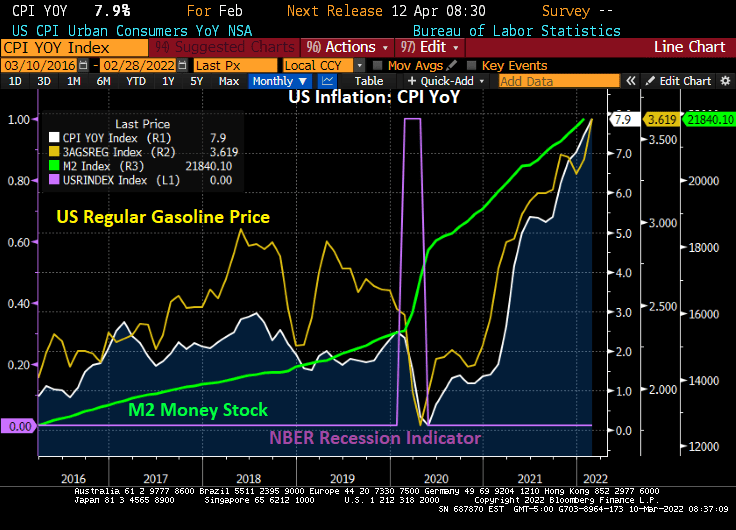
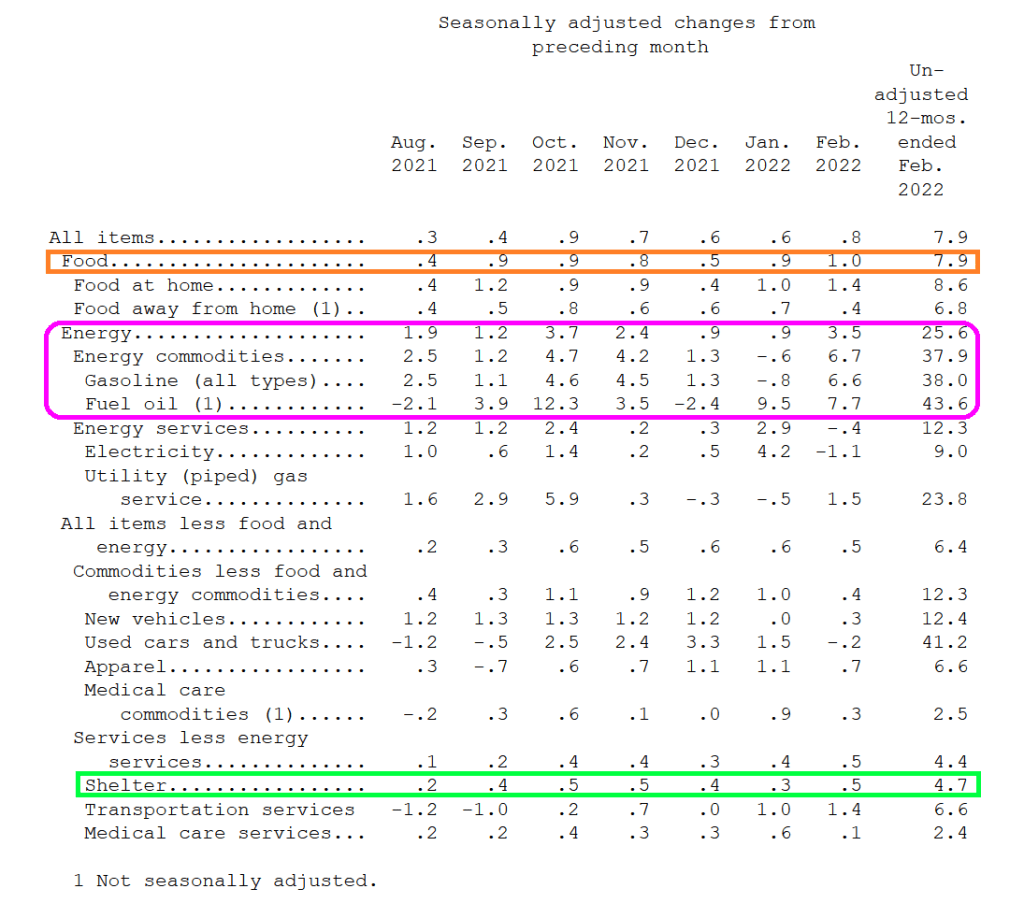
Energy costs soared in February YoY. Gasoline was up 38%. Fuel Oil was up 43.6%. Food was up 7.9%.
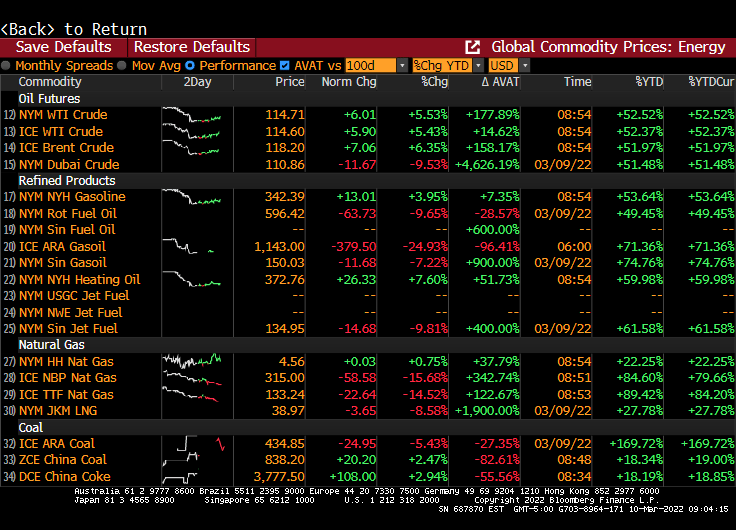
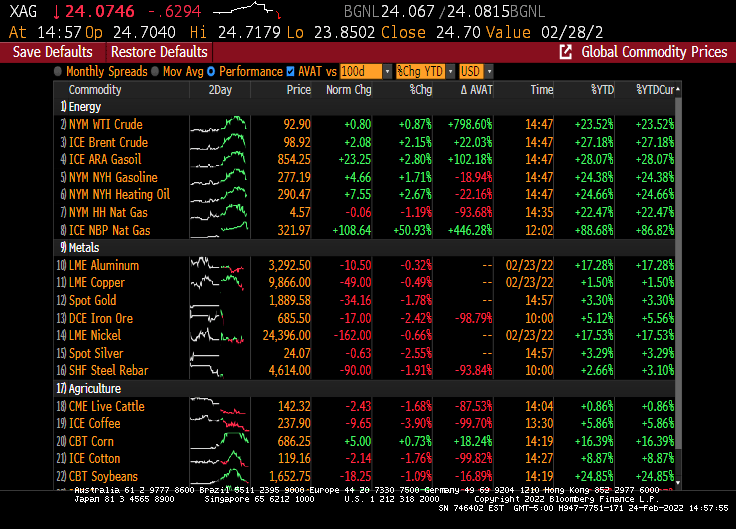
Volatility (AVAT) rages in the energy sector.
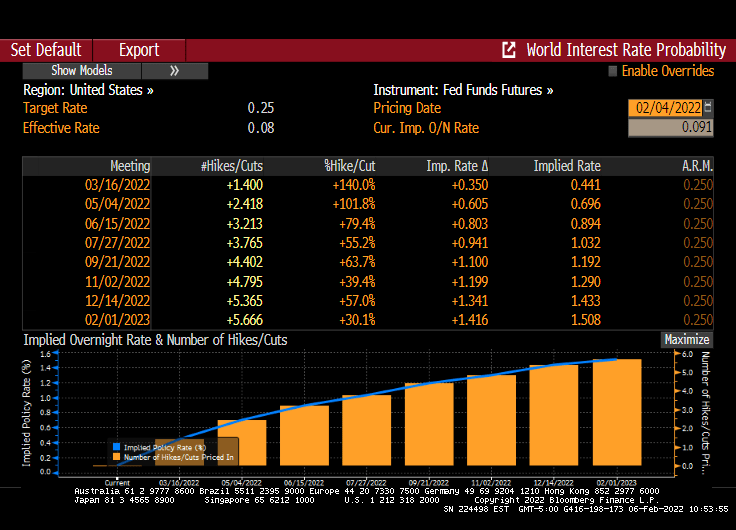
There are still 7 rate hikes in the cards from The Federal Reserve.
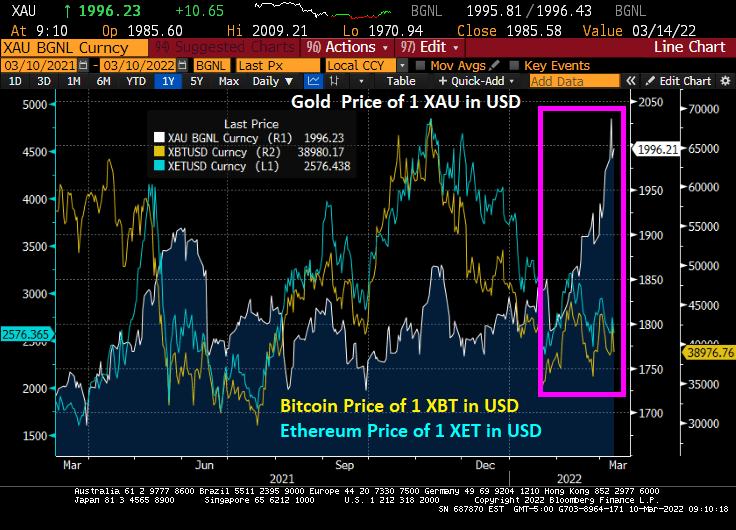
Gold has been climbing as Russia invades Ukraine. Cryptos Bitcoin and Ethereum are steady, even as the Biden Administration issues an executive order to “study” cryptocurrencies.
WTI Crude Oil spot price was up 91% from the beginning of 2021 to the Russian invasion of Ukraine. Now it is up 142% thanks to the invasion of Ukraine.
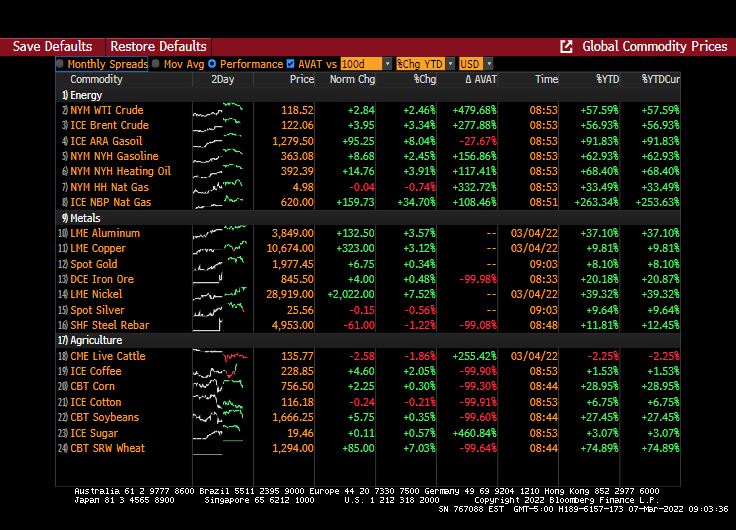
Energy prices are still soaring with UK Natural Gas prices up another 34.70% today with Brent Crude futures up 3.34%. Wheat futures are up 7.03%.
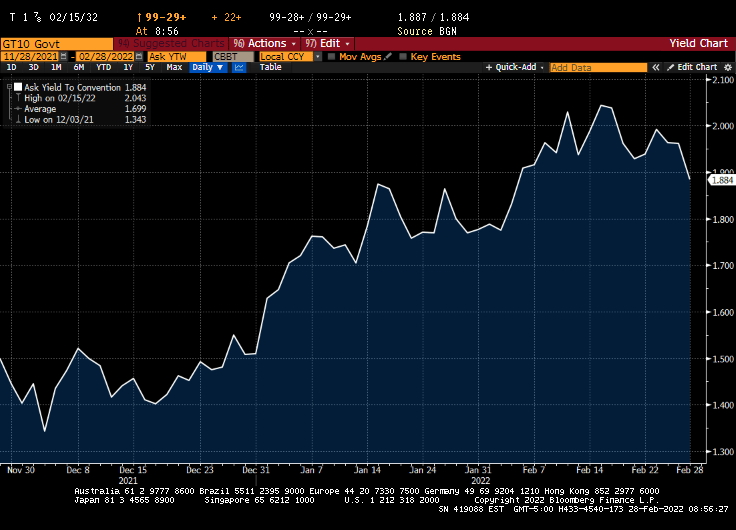
The US Treasury 10Y yield rose 6.8 bps this morning (UK takes the lead with a 10.3 bps increase).
The US Treasury 10Y-2Y yield curve slope continues to swoon to where it is now flatter than when President Biden entered office.
Gold is now at it highest level since before Biden was sworn-in as President as WTI Crude Oil soars.
Gold hit $2,000 before retreating back down.
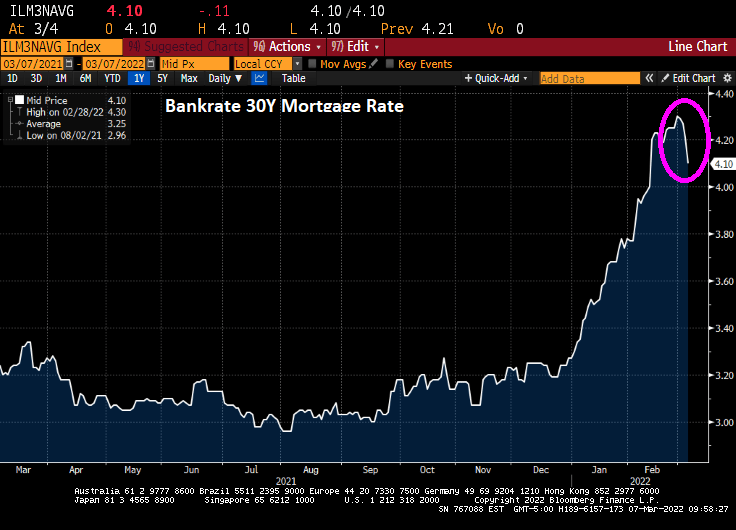
And Bankrate’s 30Y mortgage rate declined to 4.10%.
Russia is the world’s largest exporters of wheat and Ukraine is the 5th largest exporter.
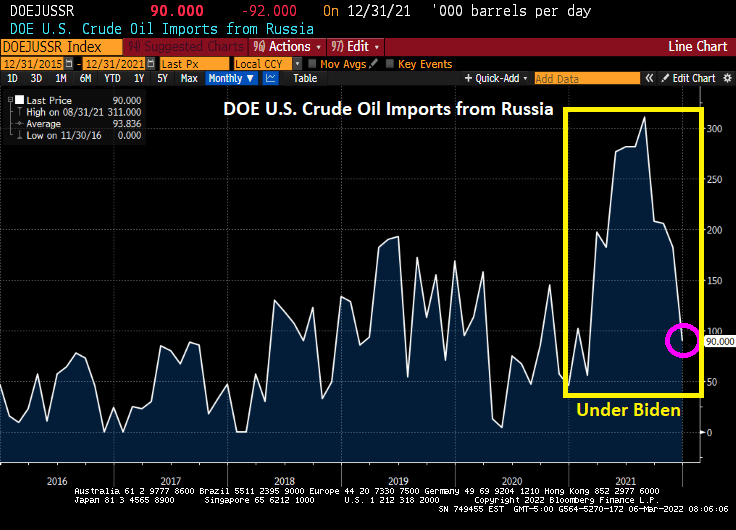
Russia is still engaged in its invasion of Ukraine. And the US continues to import crude oil from Russia. In fact, US crude oil imports from Russia soared under Biden only to decline again in December 2021.
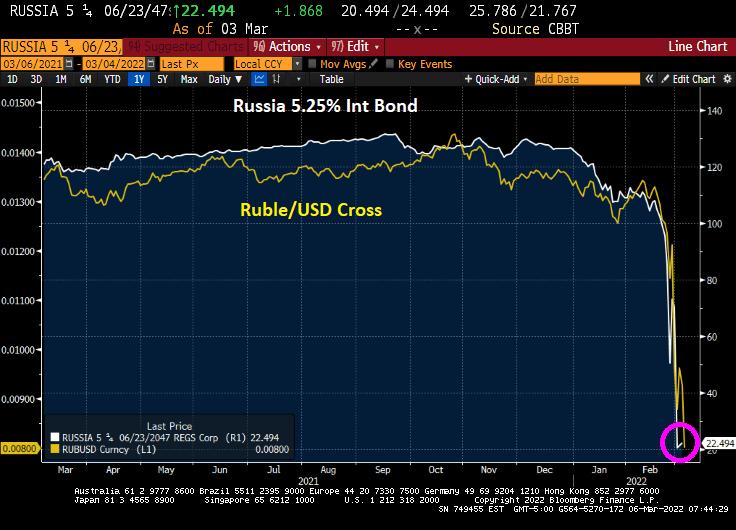
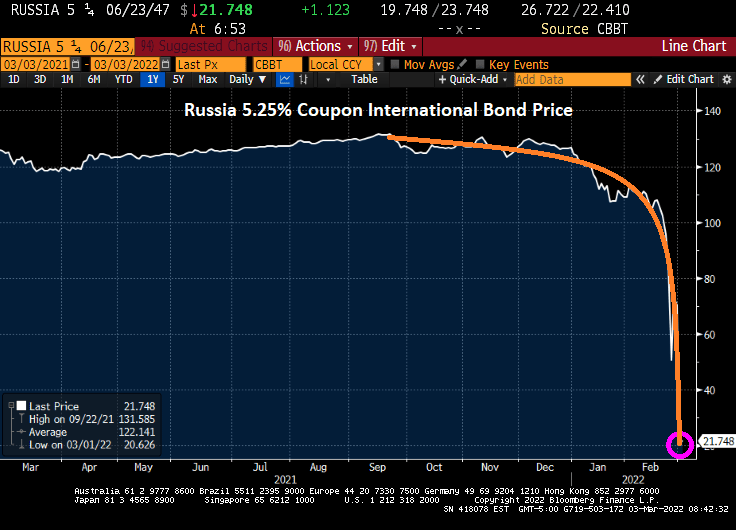
On the sovereign bond and currency front, the 5.25% coupon Russian international sovereign bond has crashed to 22.494. And the Ruble/USD cross has crashed as well.
Sberbank Bank 5 1/8% corporate bond has crashed to 25.
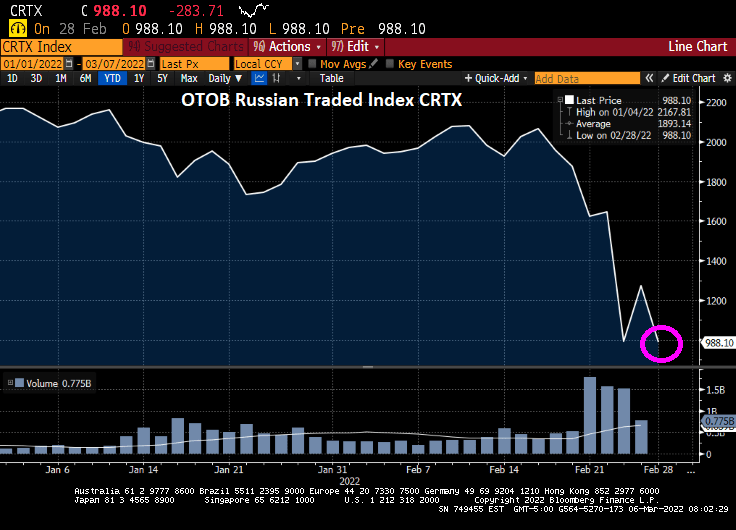
The Russian blue-chip stock market (OTOB Russian Traded Index CRTX) has crashed by over 50% since the invasion of Ukraine.
Fortunately, I like Cheerios for breakfast made from oats, since wheat futures are soaring.
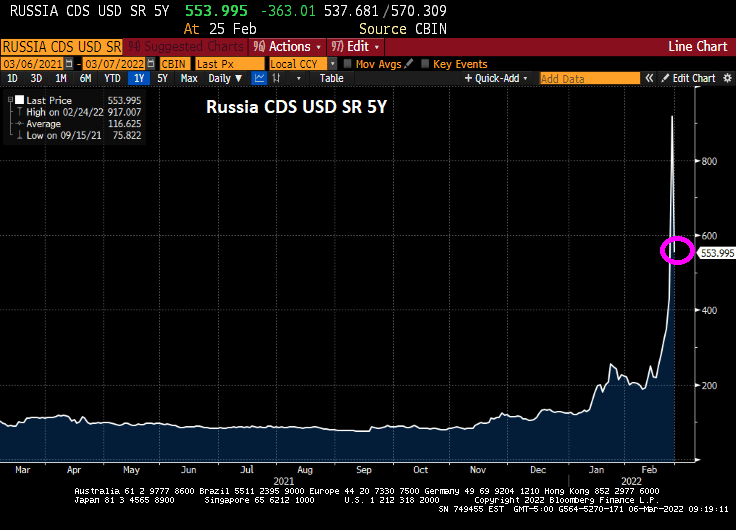
Russia’s Credit Default Swap (CDS) 5Y has dropped to a still-elevated 554.
The US really needs to ban Russian crude oil imports, since Biden’s failed in game theory by cutting US energy exploration on Federal lands and offshore drilling.
War is hell, as Vlad “The Ukrainian Impaler” Putin has demonstrated.
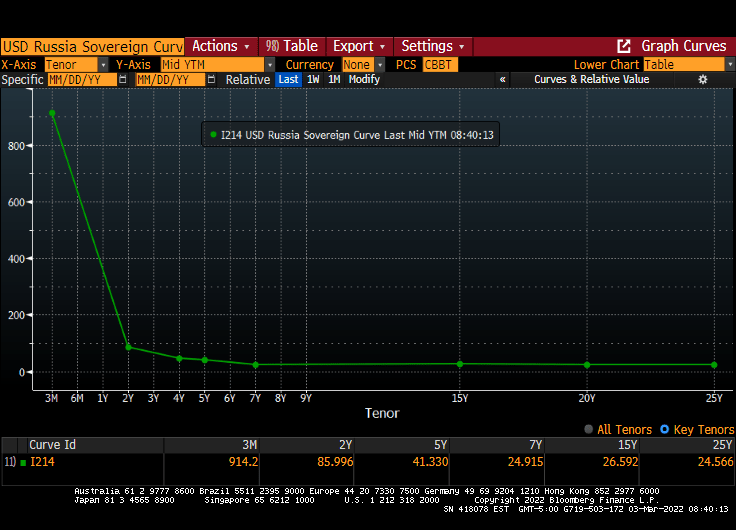
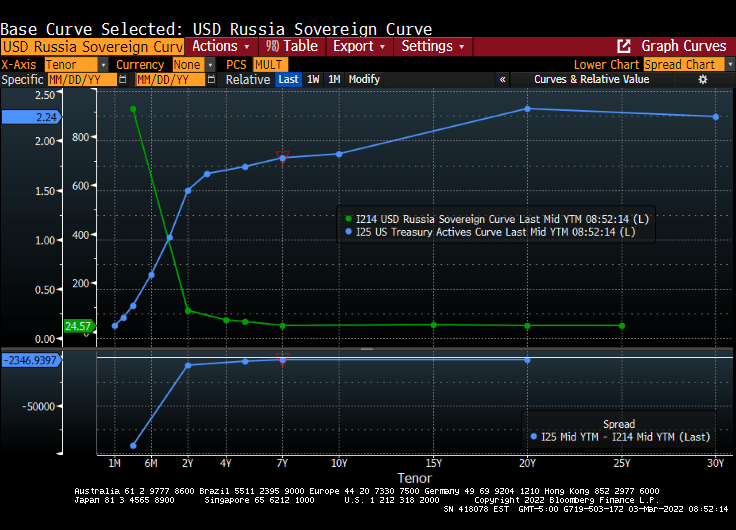
The US still has a steeply upward-sloping yield curve, but Russia has the exact opposite: a steeply downward-sloping or inverted yield curve.
Here is a comparison of the US Treasury Actives curve (steeply-upward sloping) compared to Russia’s sovereign curve (steeply-downward sloping).
Russia’s technical default on international bonds has led to its 5.25% coupon international bond (denominated in Euros) to plunge from 131.6 in September 2022 to only 21.75 this morning.
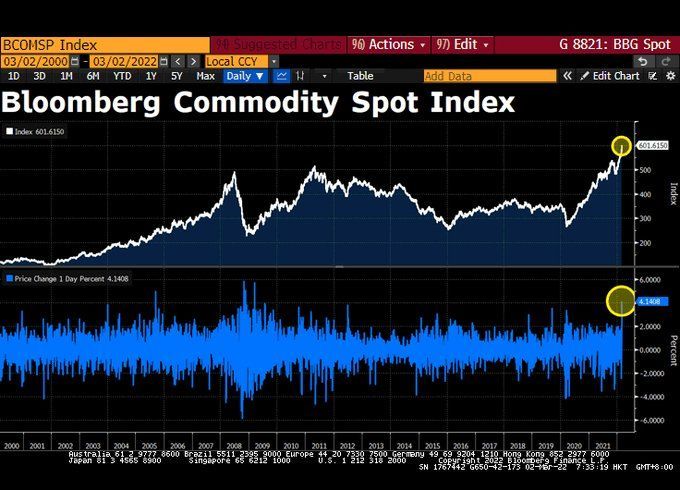
Commodity prices? Commodity prices saw the biggest one-day gain in 13 years on Tuesday.
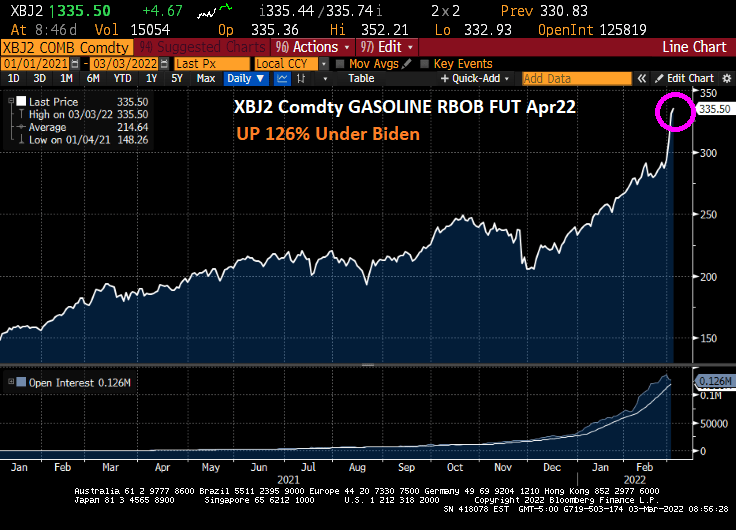
Between Biden’s anti-fossil fuel executive orders and the Russian invasion of Ukraine, gasoline futures are up 126% since the start of January 2021.
The U.S. merchandise-trade deficit unexpectedly widened in January to an all-time high, reflecting a record value of imports and a drop in shipments overseas.
The shortfall grew to $107.6 billion last month from $100.5 billion in December, according to Commerce Department data released Monday.
Meanwhile, the US Treasury 10Y yield fell to 1.884%.
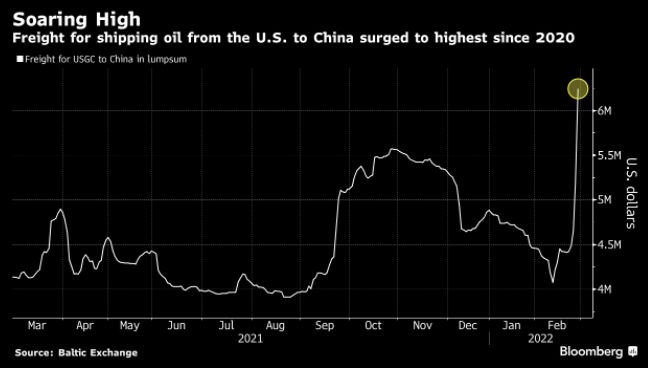
The cost for shipping from the US to China has surged.
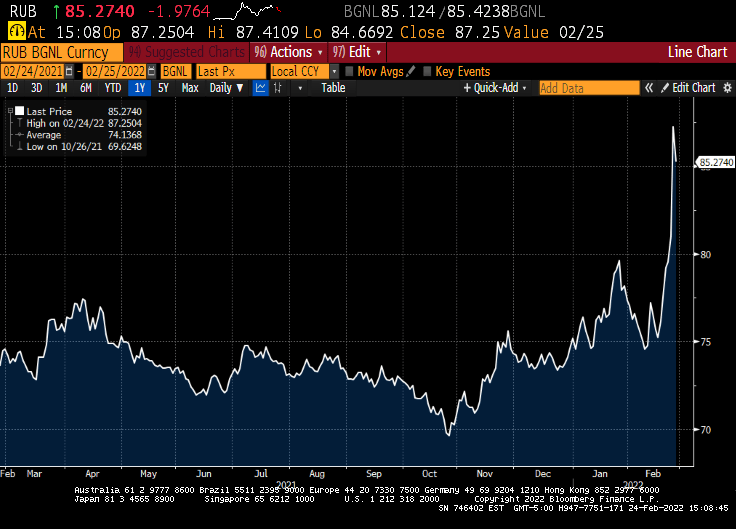
Meanwhile, the Russian Ruble is getting clobbered.
At least Putin hasn’t put himself on Russian currency … yet. Or nyet.
We now know that Russia has invaded Ukraine and President Biden really threw the booklet at Putin in a speech today. Rather than removing Russia from the SWIFT banking system which would have really hurt Russia’s trade with Europe, he gave a surprisingly cogent speech about the US and NATO agreeing to do … not much. He did warn us that energy prices would rise (which he helped do when he took office) and told energy companies not to gauge consumers.
The reaction in Russia? Their stock market tanked over 30% (not because of Biden’s speech, but because of negative costs of war).
Russia’s 10-year sovereign yield rose to 15.23%.
The Russian Ruble crashed and burned.
UK natural gas prices rose 51% today.
And while 17 Euro nations have negative 2 year sovereign yields, Russia has 2-year sovereign yield of 28.65% which is nothing compared to Ukraine’s 75% 2-year yield (in US Dollars).
The SWIFT system, or Society for Worldwide Interbank Financial Telecommunication, facilitates financial transactions and money transfers for banks located around the world. The system is overseen by the National Bank of Belgium and enables transactions between more than 11,000 financial institutions in more than 200 countries around the world. Removing Russia from the SWIFT system would really hurt Russian trade with Europe. I assume that Europe is scared of soaring energy costs, so probably doesn’t want Russia removed from SWIFT.
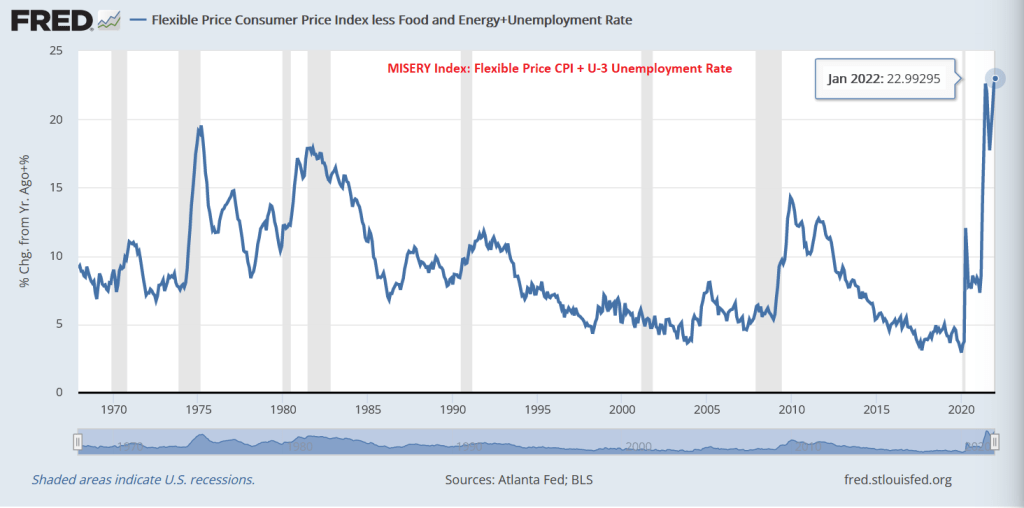
It is truly a miserable time for many Americans as demonstrated by the Misery Index (inflation rate + unemployment rate). But rather than using the CPI YoY measure at 7.5%, I am using the FLEXIBLE CPI YoY to compute the misery index. And is it ever miserable!
In January, the CORE flexible CPI YoY + U-3 unemployment rate hit a modern high at 22.99%. Or at least since 1967.
Like the movie “50 Shades of Gray,” we have 50 shades of inflation. Examples?
How about hardwood? Producer Price Index for hardwood is up 30.8% YoY.
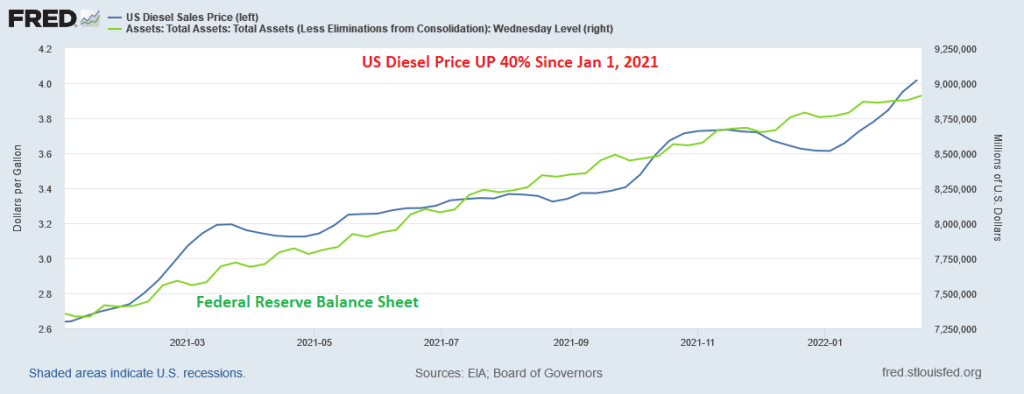
How about diesel fuel prices? They are UP 40% since January 1, 2021.
How about housing? UP 20% YoY according to Zillow’s home value index.
Global food prices? UP 20% YoY.
I could go on and on, but you get the picture. Rising energy, food and construction materials are soaring making many Americans miserable.
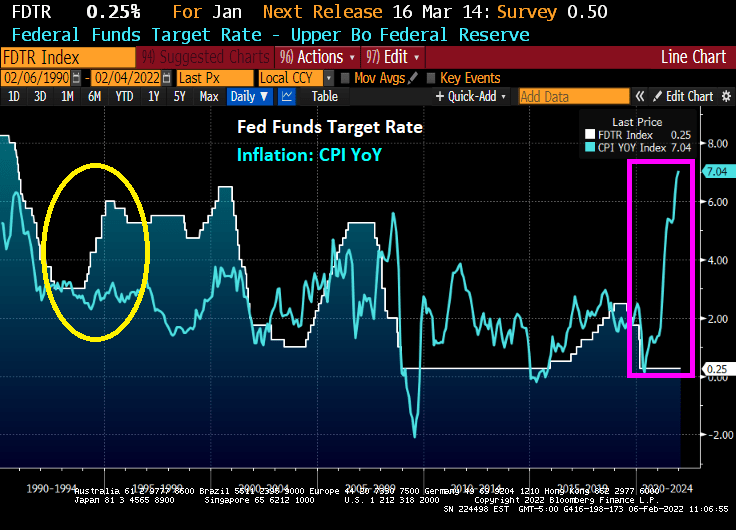
But Powell and The Fed have promised to whip inflation. Whip it good … with interest rate increases.
(Bloomberg) What a difference 25 years makes. Worried that inflation was about to turn higher, the Federal Reserve in February 1994 began raising interest rates, taking the federal funds rate from 3% to 6% a year later. As it turned out, those worries were unfounded: The U.S. consumer price index barely budged, finishing the year at 2.7%, right where it had started.
Although inflation in many developed-world countries is now well above those levels — 7% in the U.S. alone — of the major central banks only the Bank of England has started to raise short-term rates. They are now, um, 0.25%. Across the developed world, short rates are still either barely above zero or negative. What’s more astonishing is that even though they have cut their purchases, the Federal Reserve and European Central Bank continue to buy about $140 billion of longer-maturity bonds every month, suppressing long-term yields even as inflation rages.
Some central banks say that rate hikes are coming, but their extraordinary reluctance to deal with actual inflation means it will become entrenched. Not only will policy makers have to raise rates more than they envision, but they will have to cut the size of their massive balance-sheet assets, too. Don’t expect that the process will be anything other than awful for risky assets of all stripes.
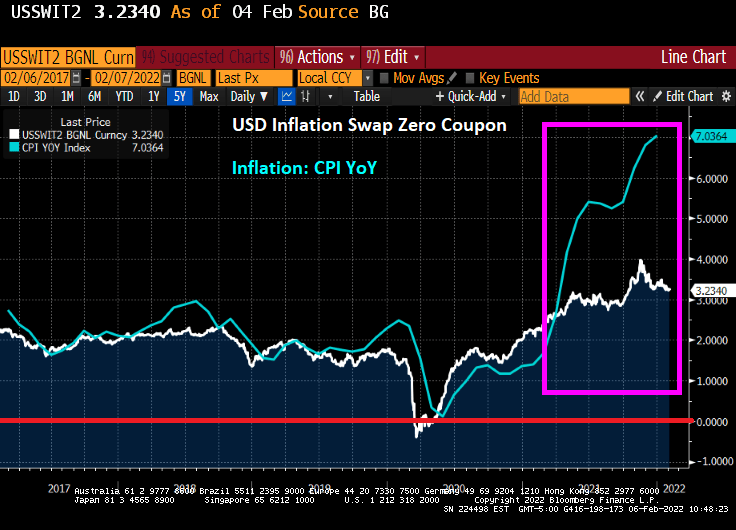
Over the last year and a half, inflation has not only accelerated but also broadened. It started with goods prices and has now expanded to services, even in the moribund euro zone. Central bankers and markets still believe inflation rates will come down a lot. The part of the swaps market that in essence predicts inflation in the future is pricing in a drop in the U.S. CPI to 3.6% by the spring of 2023 and to 3.25% the year after. Alas, like central bankers, the inflation swap market’s record is dreadful. In late spring of 2020, markets predicted a CPI of minus 1.35% a year later and staying below zero by the spring of 2022.
The US DollarInflation Swap is a poor predictor of inflation, at least under President Biden.
I’m not suggesting inflation will remain at current nosebleed levels. More likely is that having had a couple of decades of headline inflation that was on the low side — for central bankers, but not for anyone else — we are in for a few years when it remains above their targets.
Short rates will of course need to rise. That is problem enough for markets, but the bigger problem comes from the trillions of dollars of assets that central banks have accumulated on their balance sheets. Taken together, the Fed, ECB, Bank of Japan, Bank of England and Swiss National Bank have some $27 trillion of assets. In 2007, before the global financial crisis, the combined total was a little more than $4 trillion. Central bank assets will stop growing this year, undermining a major source of support for all types of bonds. But if inflation remains persistently high, central banks won’t simply be able to let their assets roll off as they mature, as most assume. They will have to start selling them. That is the big problem.
Central banks resorted to buying bonds and other financial assets (so-called quantitative easing) for a few reasons. The main one was to drive up inflation and inflation expectations from uncomfortably low levels by injecting more liquidity into the financial system and driving down longer-dated yields. Now that central banks have got much more inflation than they wanted, they will, by the equal and opposite token, need to sell the assets they bought. The longer inflation remains at current levels, the greater the pressure to sell. And they will probably need to do so sooner and faster than most expect and at prices a lot lower than they fetch today. The Fed alone owns about 30% of all the notes and bonds issued by the U.S. Treasury Department.
To say that central bank purchases have had a large effect on yields would be an understatement. One way of seeing this is to split the yield of a longer-dated bond into the part that reflects the expected path of interest rates over the life of the security from everything else. That “everything else” is the term premium. This should compensate investors for, say, sudden surges in inflation. Clearly, this is no longer true. Depending on what model you use, the term premium on 10-year Treasury reached a high of 450 basis points to 500 basis points in the early 1980s. At the nadir of the pandemic, it was minus 100 points and is now about minus 10 points. To be clear, this means that you get less buying a 10-year Treasury than would be suggested by the expected path of rates over the life of the bond — expectations that are almost certainly too low.
Term premiums below zero suggest bond investors are no longer compensated for things like inflation.
The driving down of government bond yields also compressed yields and spreads on investment-grade and junk bonds. That was the intent. Junk spreads reached their narrowest level ever in June of last year. With so little yield available in fixed income and central banks seemingly always on hand to bail them out, investors flooded into equities. As a result, many developed-world equity indexes are either very expensive or, in the case of the U.S., not far off their most expensive levels ever based on valuation measures that are a decent guide to future returns. That is what a decade and a half of market manipulation by central banks has done.
The policies of zero or negative rates and seemingly infinite QE looked idiotic (and were) when they were adopted, and time has not been kind. Paradoxically, they could only be sustained if central banks were wrong, and their policies failed to spark inflation. Now that inflation has taken hold, rates will go up substantially and balances sheets will need to shrink.
What would you pay for fixed-income assets now if you knew that central banks will become, in effect, forced sellers later? I can’t see how any financial asset will escape the damage from the likely lurch higher yields. The way out of these policies will be as nasty as the way in was nice.
Particularly since Fed Funds Futures are pointing toward 6 rate increases over the next year.
At least Treasury Secretary Janet Yellen is wearing her Mao jacket.

























You must be logged in to post a comment.