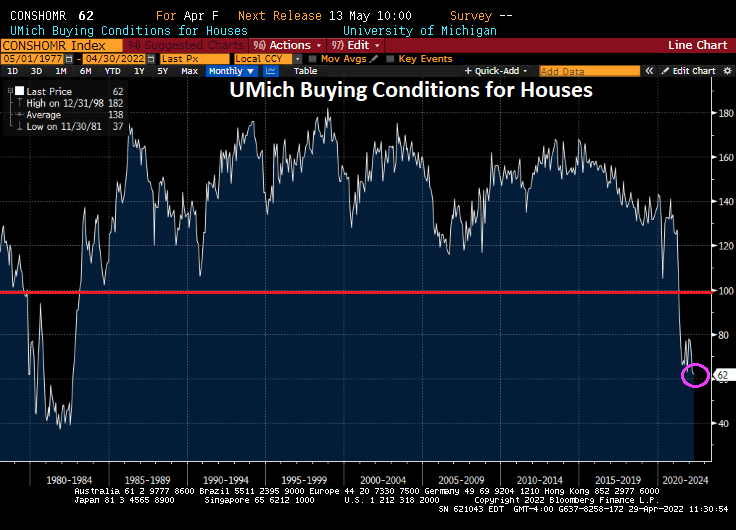
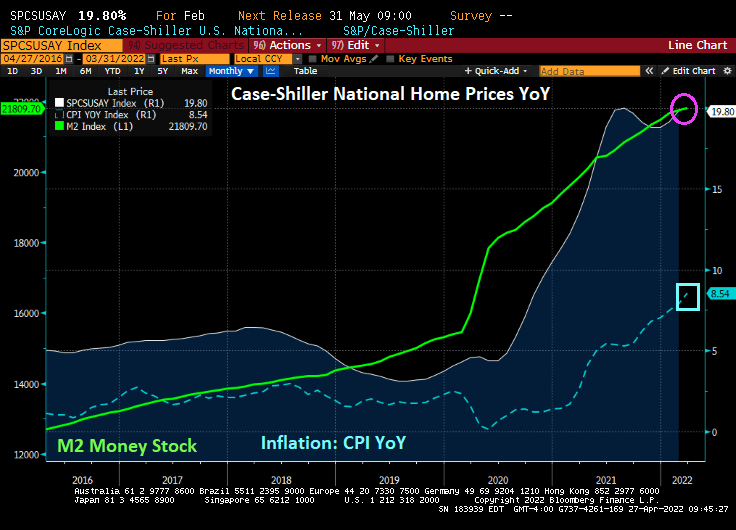
Rising home prices and The Fed signaling an end to the perpetual punch bowl have resulted in the University of Michigan buying conditions for houses to hit the lowest level since 1982.
While bearish sentiment in markets highest since 2009 in the stock market.
I don’t get why Biden created a “Disinformation Control Board” led by Nina Jankowicz – a disinformation spewer. We already have disinformation media outlets like CNN, MSNBC, ABC, CBS, NBC, New York Times, Washington Post, etc., so why create a Federal control board? All in time for the midyear elections!!
If this move by Biden doesn’t terrify you, then you didn’t study history.
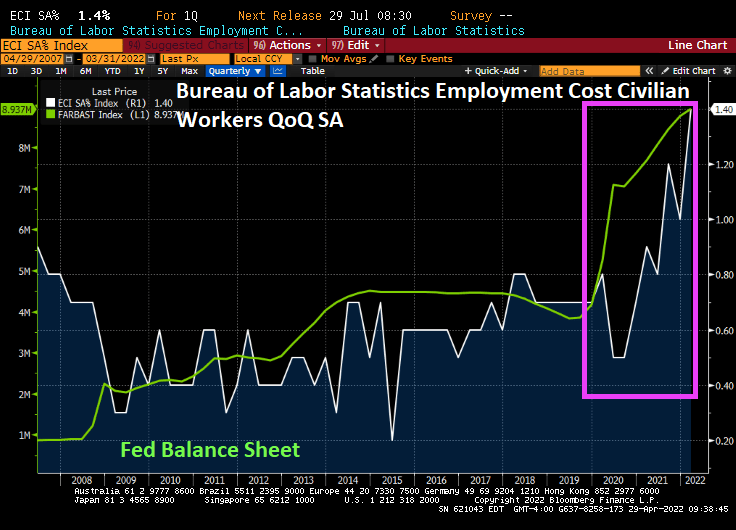
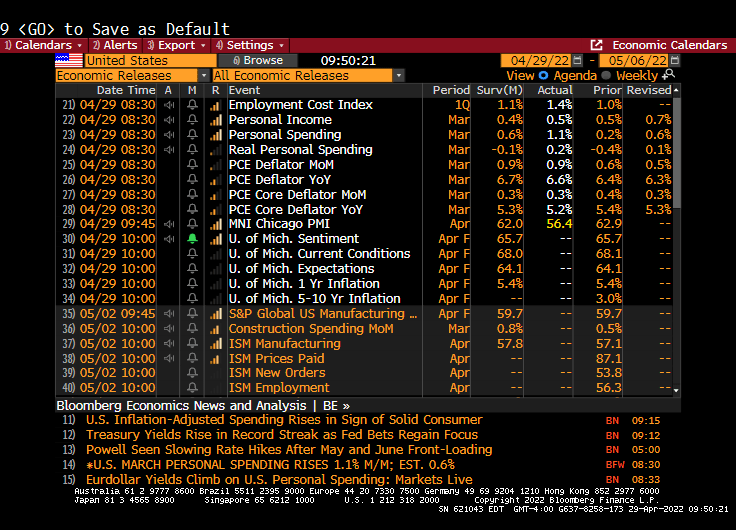
Not only has The Federal Reserve driven M2 Money Velocity to near historic lows, but now we find out that the Employment Cost Index just rose to a historic high.
Of course, a variety of minimum wage laws have helped drive up employments costs. Don’t tell lawmakers that minimum wage laws lead to higher inflation since they typically deny responsibility for anything. But I can almost picture the 4 Horsemen of the Inflation Apocalypse (Powell, Biden, Pelosi, Schumer) sitting around asking “What we can do to make inflation worse?”
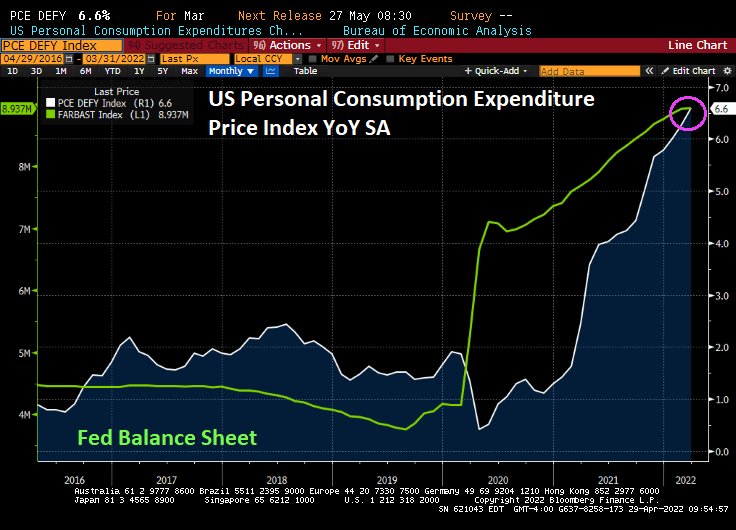
We did see the PCE Deflator YoY rise to 6.6%, the highest since 1982, the highest in 40 years.
Personal spending increased to 1.1% in March, probably panicking buying over further inflation.
A PCE Deflator of 6.60% leads to a Taylor Rule estimate of 9.05% for The Fed Funds Target Rate.
I hope America’s foreign policy wizards (Biden, Harris and Blinken) weren’t relying on the Russian Ruble staying pulverized, because the Ruble (relative to King Dollar) has regained all its losses.
On the other hand, the Japanese Yen and Chinese Yuan have crashed harder than Biden’s popularity.
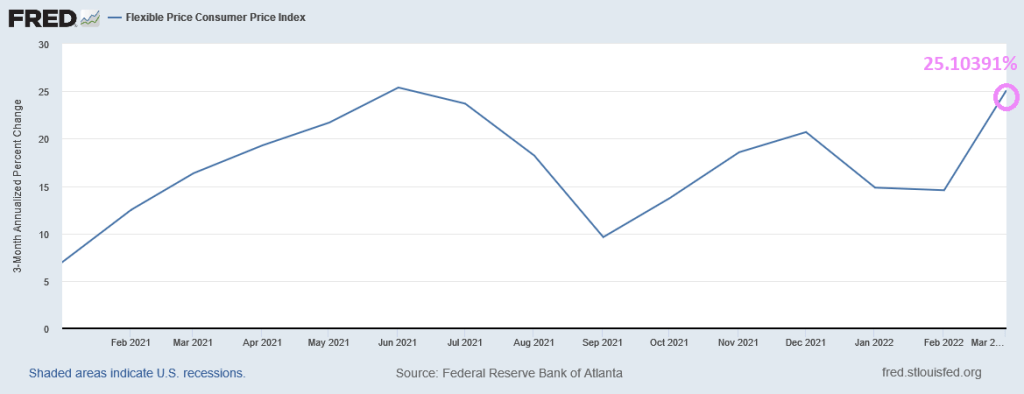
Actually, The Atlanta Fed’s flexible price inflation rate is 25%, up from 3.90% Pre-Joe.
Perhaps Biden, Harris and Blinken think Putin is a pasta sauce.
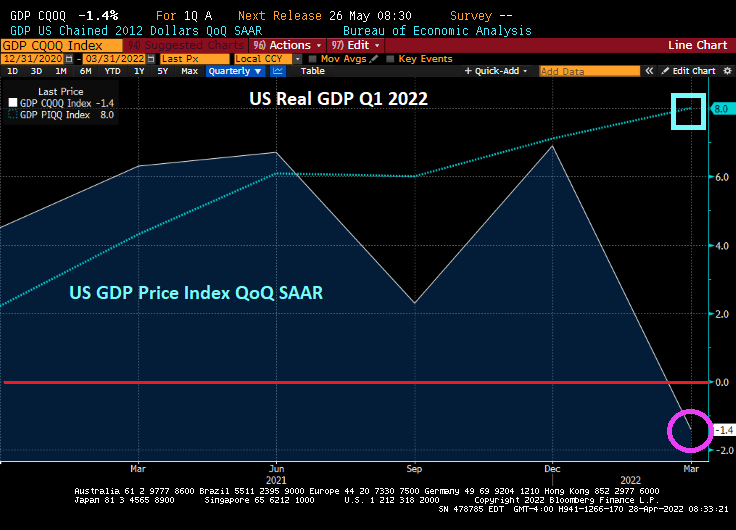
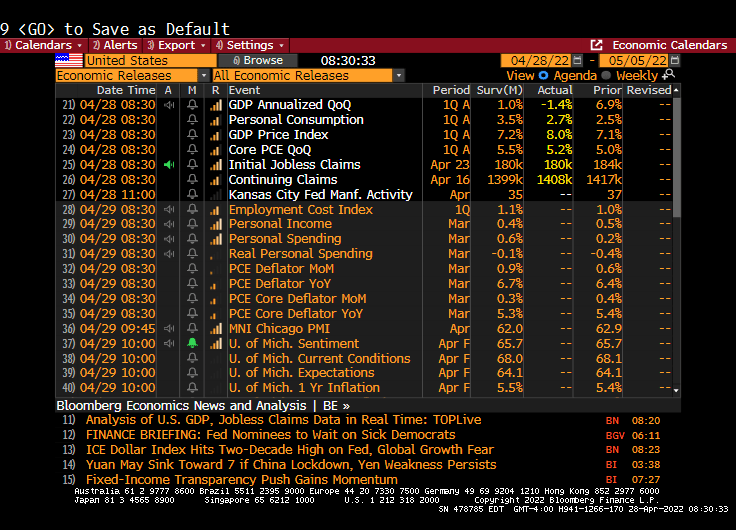
Heartaches in heartaches. US GDP growth for Q2 has stumbled to 0.446% as The Fed is launching quantitative tightening (QT) to fight the inflation that they caused in the first place.
According to the Atlanta Fed’s GDPNow real-time GDP tracker, US GDP growth has stumbled to a meager 0.446%. Despite the massive stimulus from The Federal Reserve and Washington DC’s massive fiscal stimulus.
From the MBA: Mortgage Applications Decrease in Latest MBA Weekly Survey. Mortgage applications decreased 8.3 percent from one week earlier, according to data from the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey for the week ending April 22, 2022.
The Refinance Index decreased 9 percent from the previous week and was 71 percent lower than the same week one year ago.
The seasonally adjusted Purchase Index decreased 8 percent from one week earlier. The unadjusted Purchase Index decreased 7 percent compared with the previous week and was17 percent lower than the same week one year ago.
The percentage of adjustable-rate mortgages (ARMs) increase 9.4% from previous week.
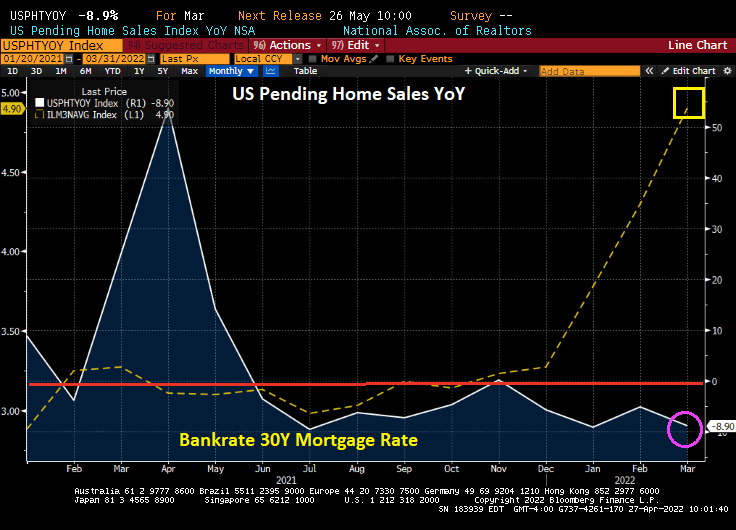
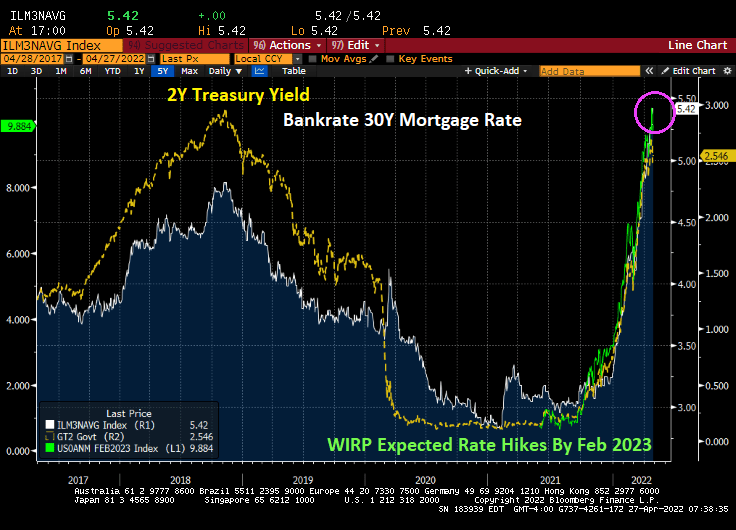
Yes, the 30-year mortgage rate is rising extremely fast.
“You’re Going Down” by Jerome Powell and The Constitution Avenue band. President Joe Biden conducting.
US existing home sales in March were expected to fall -0.6% from February, but they actually fell -8.6%. This is happening at The Federal Reserve is signaling tightening and mortgage rates are rising rapidly.
Here is Dvorak’s New World Symphony, an appropriate piece the global turmoil that has taken place after Russia’s invasion of Ukraine.
Here is the ratio of the S&P 500 index against the Bloomberg Commodity Price Index. This ratio is plotted against The Federal Reserve’s balance sheet of assets. Notice the decline in the Commodity Ratio in 2022, even ahead of the Russian invasion of Ukraine.
Global currencies, on the other hand, have been really crushed since the Russian invasion of Ukraine. The Japanese Yen, China’s Renminbi and Europe’s Euro relative to the US Dollar are falling due to a variety of reasons. Covid lockdown in China, Japan’s insistence on monetary easing while other Central Banks are tightening and the Euro with Russia threatening nuclear war.
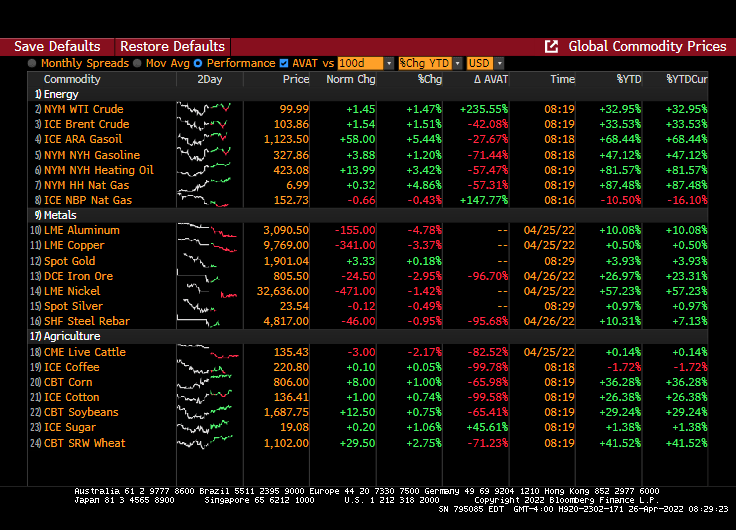
WTI Crude is back to $100 a barrel. Critical metals are down today related to a slowing global economy and wheat is up 2.75%.
Could it be that US Dollar hegemony is nearly over and commodity-backed currencies are the way of the future?
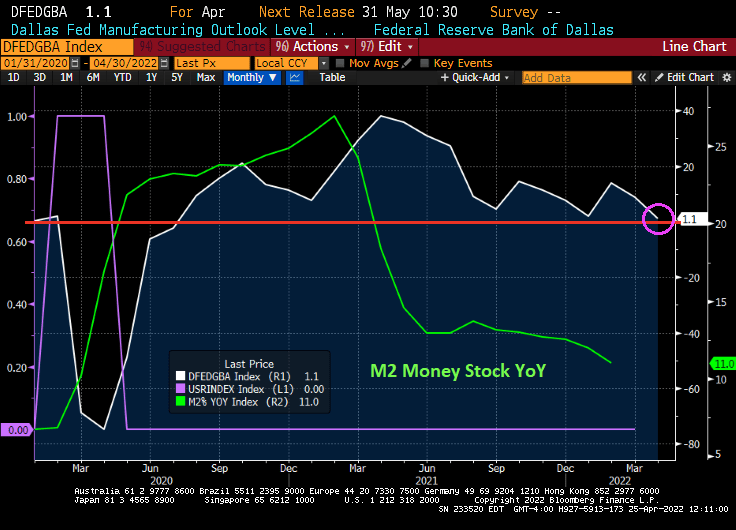
M2 Money stock YoY skyrocketed during the Covid mini-recession, peaking at 21% during February of 2021. The Dallas Fed manufacturing outlook grew to 38.1 in March 2021.
However, as M2 Money growth has slowed 11%, the Dallas Fed manufacturing outlook has plunged to near zero.
Its Saturday and I am dreading markets opening on Monday. But here is where we sit today.
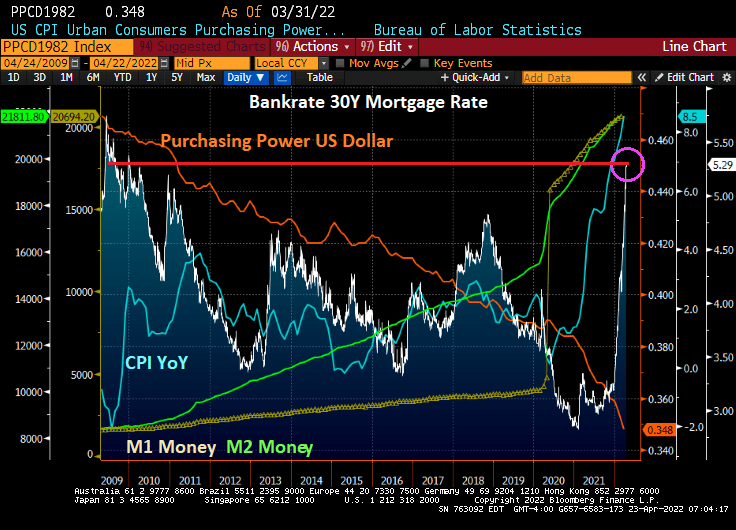
The 30-year mortgage rate has soared to 5.29%, the highest level since 2009 at the beginning of Obama’s Presidency. Since 2009, we have seen the purchasing power of the US Dollar decline further (orange line) while inflation (blue line) has soared. M1 (yellow) and M2 (green) has been growing since the financial crisis, but really took-off with the Covid outbreak in 2020 and The Fed’s massive overreaction coupled with Federal government stimulus.
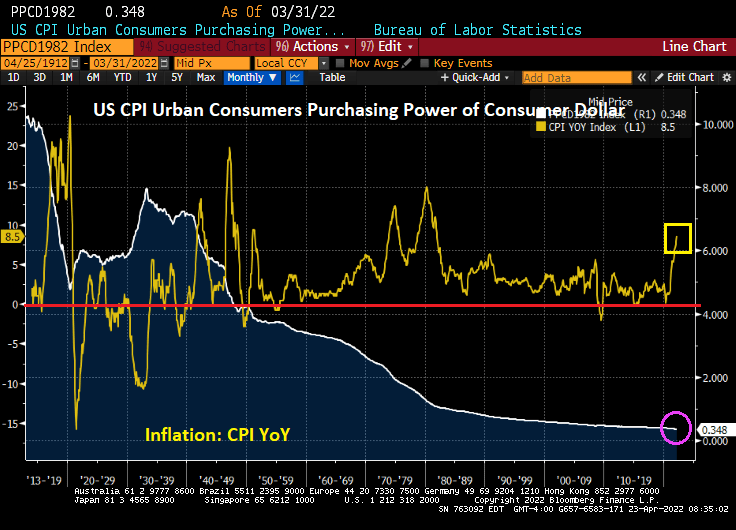
Since the creation of The Federal Reserve System under President Woodrow Wilson, the purchasing power of the US Dollar has collapsed so much that $10 in 1913 in worth 34.8 cents today. But notice that since 1949, the CPI YoY has rarely been negative meaning that prices are pretty much only going up.
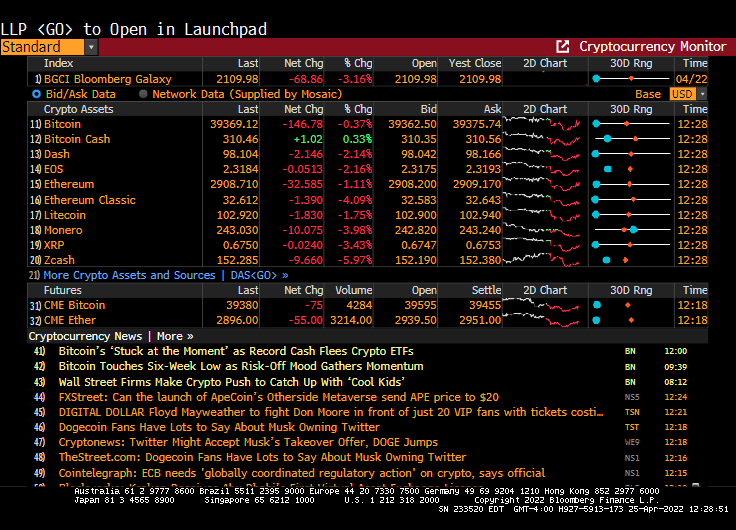
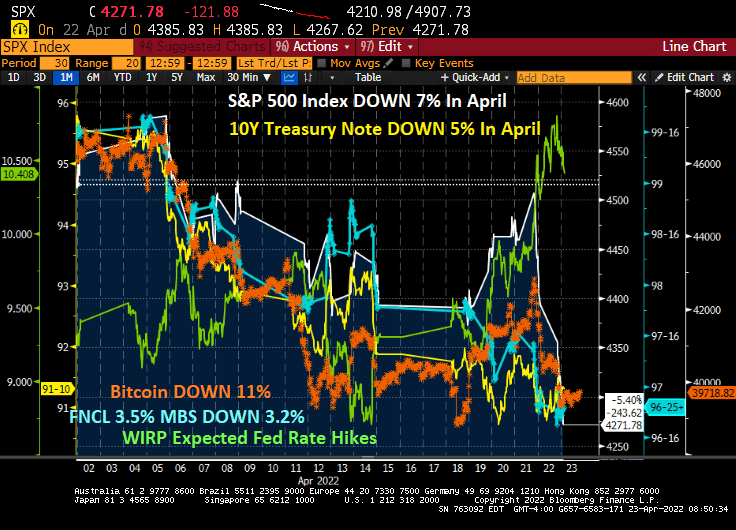
Instead of April showers bring May flowers, it is April expected Fed rate hikes (now 10.408 rate hikes by February 2023) bringing declining assets prices. In April so far, the S&P 500 index is DOWN 7%, the 10-year Treasury Note price is DOWN 5%, Bitcoin is DOWN 11%, the 3.5 coupon agency MBS price is down 3.2%.
We are seeing increased volatility in both the equity and bond markets.
Well, Powell and The Fed are hurling fireballs at mortgage rates and asset prices in April.



















 Confounded Interest - Anthony B. Sanders

You must be logged in to post a comment.