Bidenomics! Ford Will Lose $4.5 Billion On EVs This Year, Up From $2.1 Billion Last Year (Ford DOWN -48% Since January 2022, GM DOWN -40% As Fed Withdraws Stimulus)

Bidenomics, the term for “Government Gone Wild! in terms of spending and EPA regulations, is a disaster for the US middle class and low wage workers. Even the 1% are now hurting if bought into Biden’s green lunacy. Ford is now down -48% since January 14, 2022 as The Fed started raising rates to fight inflation. GM is down “only” -40%.
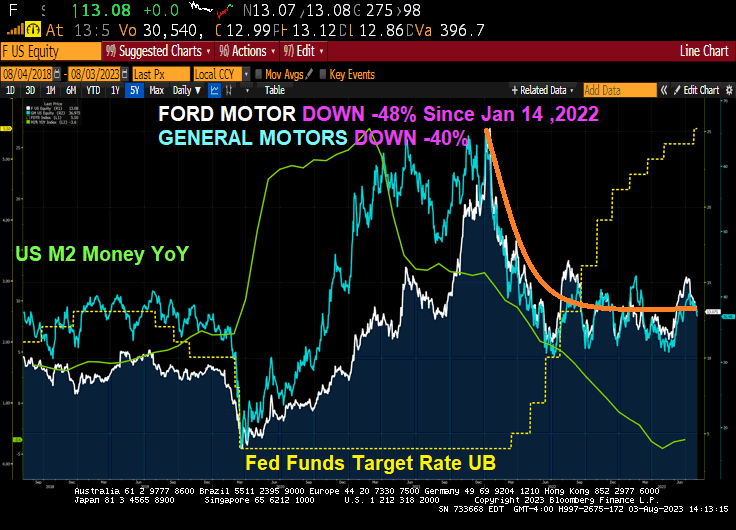
Ford is slated to lose $4.5 billion from its EV segment this year, a $1.5 billion larger loss than the company had expected. 

So far this year, the division has lost $1.8 billion and this year’s $4.5 billion loss figure blows away last year’s $2.1 billion loss. Ford also announced that its electric F-150 pickup trucks will undergo a price cut, according to Fox.

Ford beat earnings on Thursday and reported adjusted EPS of $0.72, beating expectations of $0.54. It posted revenue of $45 billion and adjusted EBITDA of $3.8 billion, above estimates of $3.15 billion. 

The company also raised its guidance, forecasting adjusted EBIT of $11 billion to $12 billion from $9 billion to $11 billion. The company is now guiding for free cash flow of $6.5 billion to $7 billion, from $6 billion. 

But reality has sunk in about the company’s comments regarding its EV production schedule and spending plans. Price cuts in the industry, led by Elon Musk and Tesla, have thrown Ford’s production targets into a tailspin and Morgan Stanley noted on Friday morning that “major changes to the EV strategy” could be necessary, according to a wrap up by Bloomberg. 

Ford now says it is “throttling back” on plans to ramp up EV production, the wrap up said. It blamed the price war for EVs as part of the cause and told shareholders it would need another year to meet its target of 600,000 EVs produced annually. 

Ford CEO Jim Farley said late last week: “The shift to powerful digital experiences and breakthrough EVs is underway and going to be volatile, so being able to guide customers through and adapt to the pace of adoption are big advantages for us. Ford+ is making us more resilient, efficient and profitable, which you can see in Ford Pro’s breakout second-quarter revenue improvement (22%) and EBIT margin (15%).”

CFO John Lawler said yesterday that the company “has ample resources to simultaneously fund disciplined investment in growth and return capital to shareholders – for the latter, targeting 40% to 50% of adjusted free cash flow,” Bloomberg added. He now says Ford is “not providing a date” for producing 2 million EVs per year, which was previously the company’s target for 2026. 

Ford’s inability to compete with Tesla was noted earlier this year in a piece titled Tesla ‘Weaponizes’ Price-Cuts To Crush EV Competition. 

Is the company pulling an Intel and “kitchen sinking” its guide for the year, or has Elon Musk’s price cuts over at Tesla really put the legacy automaker on the ropes? Ford reports again on October 26, where we’ll get our next glimpse into its continuing operations this year. 

Tesla is down -26% since January 14, 2022. And showing a nice turnaround!

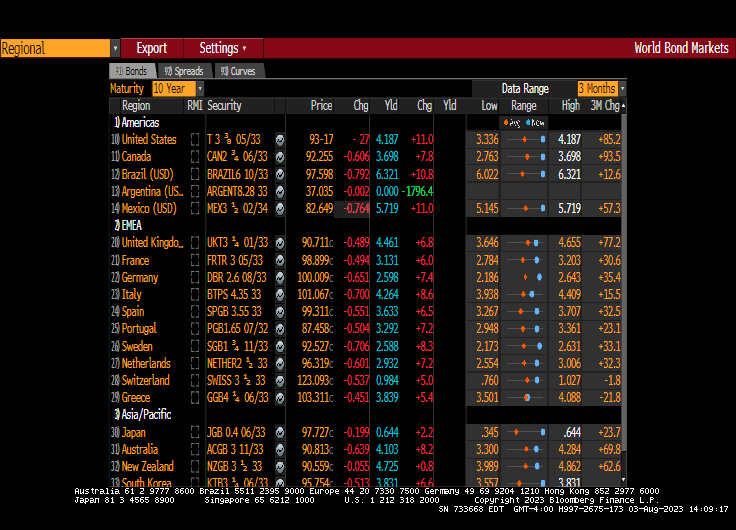
Today, the 10-year Treasury yield is up 11 basis points.
Government Gone Wild!
Bidenomics! Biden Blames USA Downgrade On Trump (But Economy Added 12.53 Million Jobs After Covid Shutdowns Ended Under Trump While It Took 2 1/2 Years For Bidenomics To Add 12.56 Million Jobs)

Bidenomics is where the Attorney General Garland gives Hunter Biden blanket amnesty and arrests Biden’s Presidential opponent. Welcome to the United Venezuelan States of America!e

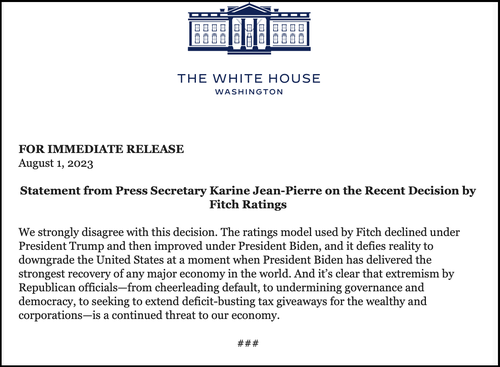
The new regime talking points are out – namely that Fitch downgraded the US credit rating from AAA  to AA+ on Tuesday because of MAGA Republicans and all things Trump.

But while Fitch cited “the expected fiscal deterioration over the next three years, a high and growing general government debt burden, and the erosion of governance relative to ‘AA’ and ‘AAA’ rated peers” as reasons for the downgrade, the Biden administration is of course blaming Donald Trump and his supporters due to one portion of Fitch’s explanation: “a steady deterioration in standards of governance over the last 20 years,” and that “repeated debt-limit political standoffs and last-minute resolutions have eroded confidence in fiscal management.”

Then on Wednesday, Fitch’s Richard Francis told Reuters that the downgrade was ‘due to fiscal concerns and a deterioration in U.S governance as well as polarization which was reflected in part by the Jan. 6 insurrection.’

“It was something that we highlighted because it just is a reflection of the deterioration in governance, it’s one of many,” he said, adding “You have the debt ceiling, you have Jan. 6. Clearly, if you look at polarization with both parties … the Democrats have gone further left and Republicans further right, so the middle is kind of falling apart basically.”

And so of course, the Biden administration is blaming Trump.

“This Trump downgrade is a direct result of an extreme MAGA Republican agenda defined by chaos, callousness, and recklessness that Americans continue to reject,” said Biden re-election campaign spokesman Kevin Munoz. “Donald Trump oversaw the loss of millions of American jobs, and ballooned the deficit with the disastrous tax cuts for the wealthy and big corporations.”

Ah, so now it’s the Trump downgrade™

Meanwhile, White House spox Karine Jean-Pierre also blamed Trump on Tuesday, saying that the White House “strongly” disagrees with the decision, adding “it’s clear that extremism by Republican officials — from cheerleading default, to undermining governance and democracy, to seeking to extend deficit-busting tax giveaways for the wealthy and corporations — is a continued threat to our economy.”

Former Clinton Treasury Secretary Larry Summers called the decision “bizarre and inept,” while former Obama economic advisor Jason Furman called the move “completely absurd.”

On Wednesday, CNBC wheeled out Jared Bernstein, chair of Biden’s Council of Economic Advisers and former Obama official, who similarly blamed Trump.

“I think again the timing issue is is Jermaine here. The deficit went up every year under President Trump. The debt to GDP ratio rocketed under President trump. It has stabilized admittedly at a higher level under this president but we’re doing all we can to try to ameliorate those tensions,” he said.

Bernstein reflected on the “cognitive dissonance” he felt at the downgrade amid the success of ‘Bidenomics’ commenting that “creditworthiness deteriorated significantly under President Trump for good reasons… and under President Biden, it started to track back up…”

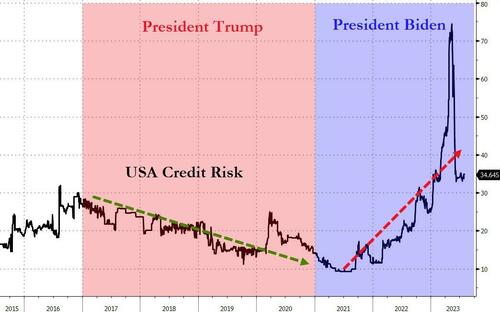
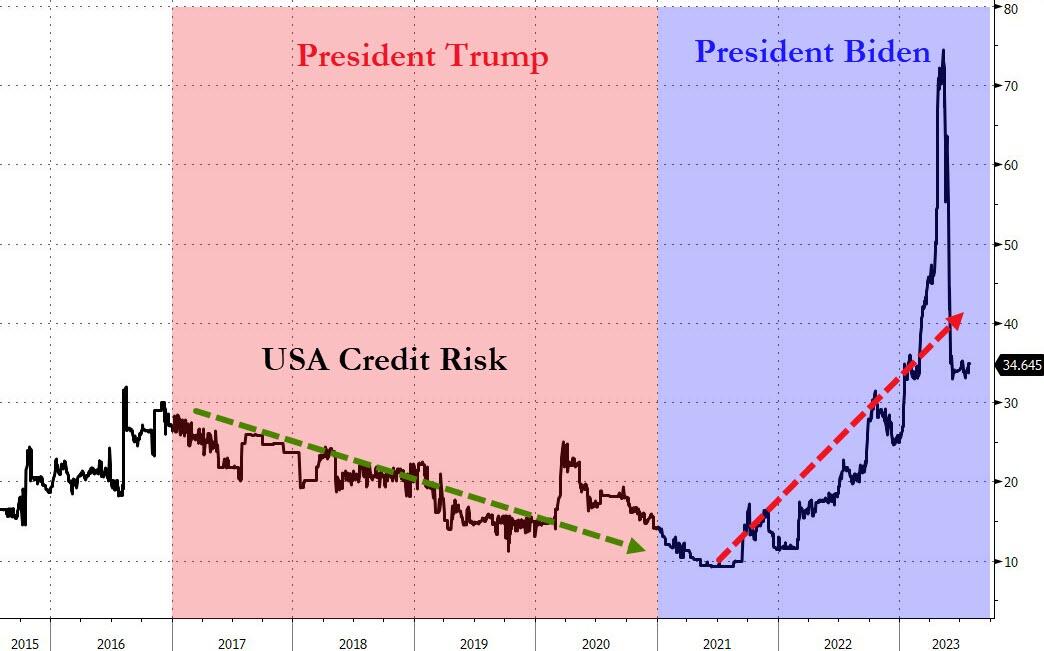
Except that’s the exact opposite of what happened. According to the 100% non-partisan “market”, the creditworthiness of US Treasury debt improved almost constantly under President Trump and worsened dramatically almost immediately upon President Biden’s inauguration:

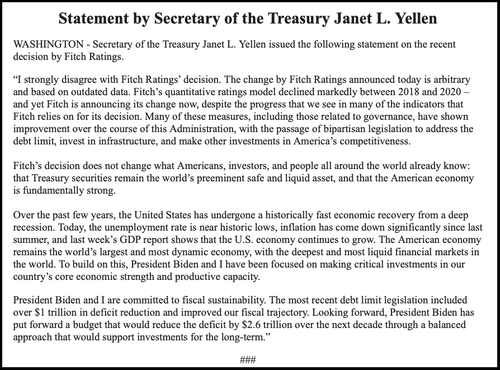
Treasury Secretary Janet Yellen said that the downgrade was “arbitrary and based on outdated data,” adding “Today, the unemployment rate is near historic lows, inflation has come down significantly since last summer, and last week’s GDP report shows that the U.S. economy continues to grow.”

CNN also blamed Trump, penning the headline: Fitch downgrades US debt on debt ceiling drama and Jan. 6 insurrection.”

The stupidity on CNN and Jared Bernstein are appalling. True, the media and Biden Administration are terrified of losing the 2024 Presidential election, but outright lies and misrepresenation are wrong no matter what.

But the claims that the US was downgraded because Trump’s economy lost miilions of jobs is ridiculous.

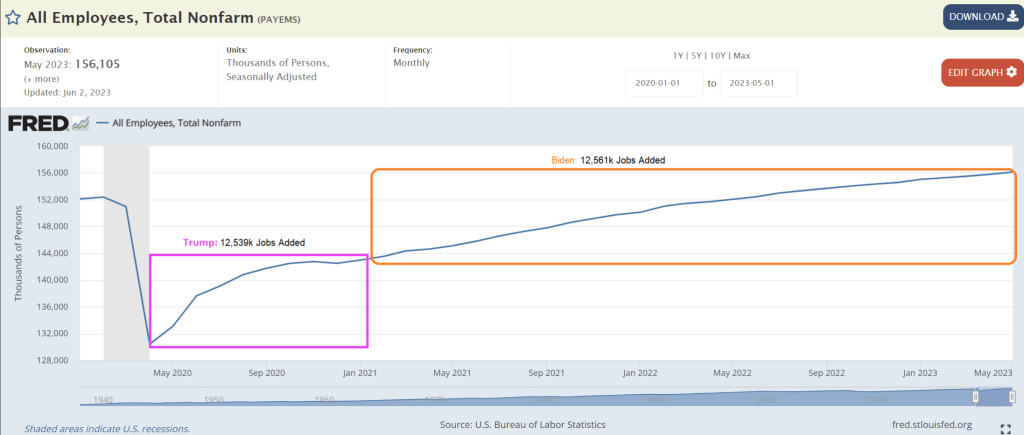
Actually, the US economy added 12.53 million jobs after April 2020 (Trump) while Bidenomics created took 2 1/2 years to add 12.56 million jobs. So, Biden took over twice as long to create jobs after Covid than it did under Trump. Simply opening the economy and schools produced that magical claim by Biden. And the National Teacher’s Union and Randi Weingarten worked with Fauci to orchestrate shutting down schools. Blaming Trump for local governments shutting down the economy is pure bunk.

Bidenomics and massive Federal spending is the cause for the downgrade. Not Trump.

Bidenomics! Wheels Come Off The “Strong Jobs” Myth As Job Openings Drop To 2 year Low (Number Of Hires And Quits Plunge As Fed Withdraws Monetary Stimulus)

The wheels are coming off the Bidenomics recovery.

US job openings (JOLTS) keep declining as The Fed withdraws its Covid sugar splash of monetary stimulus and raise The Fed’s target rate.

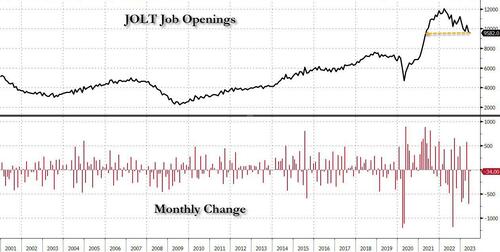
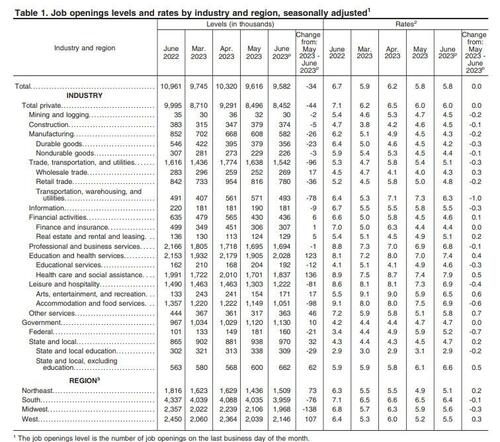
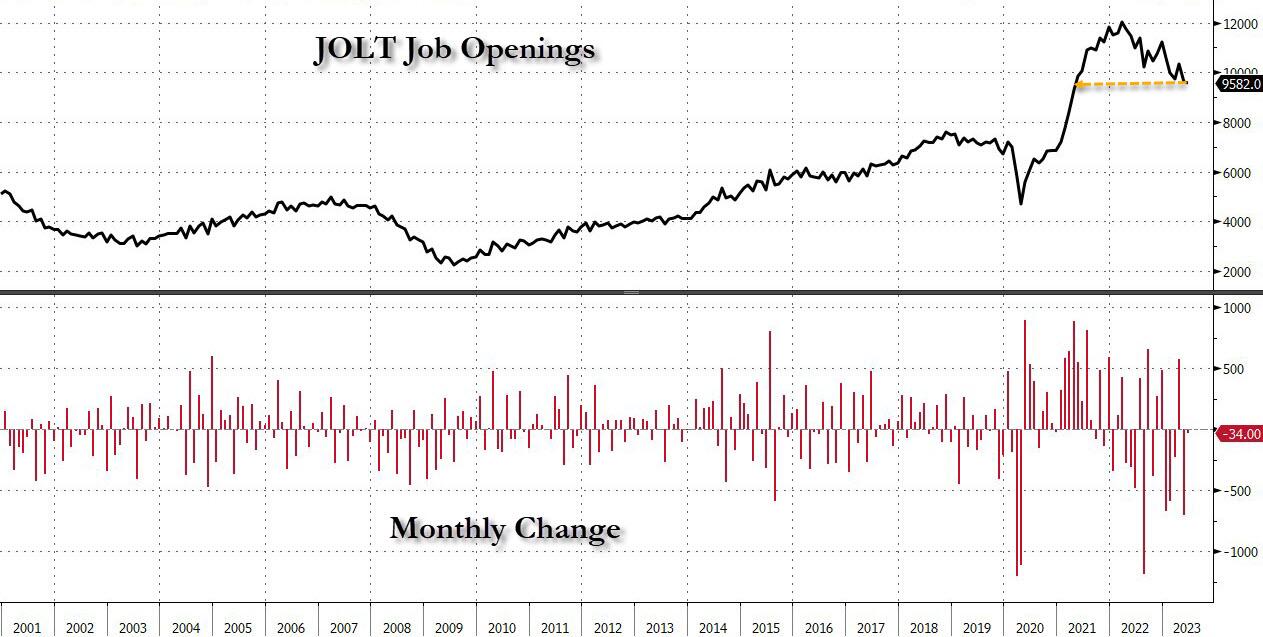
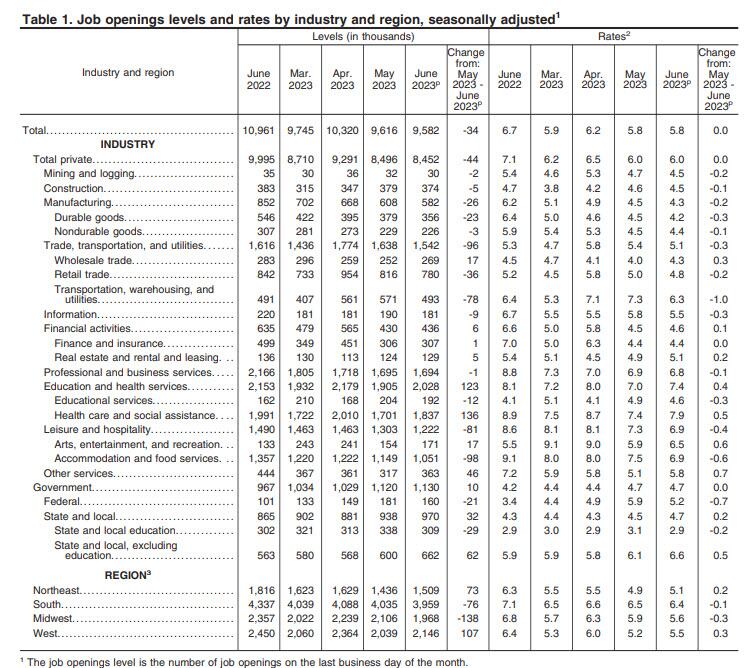
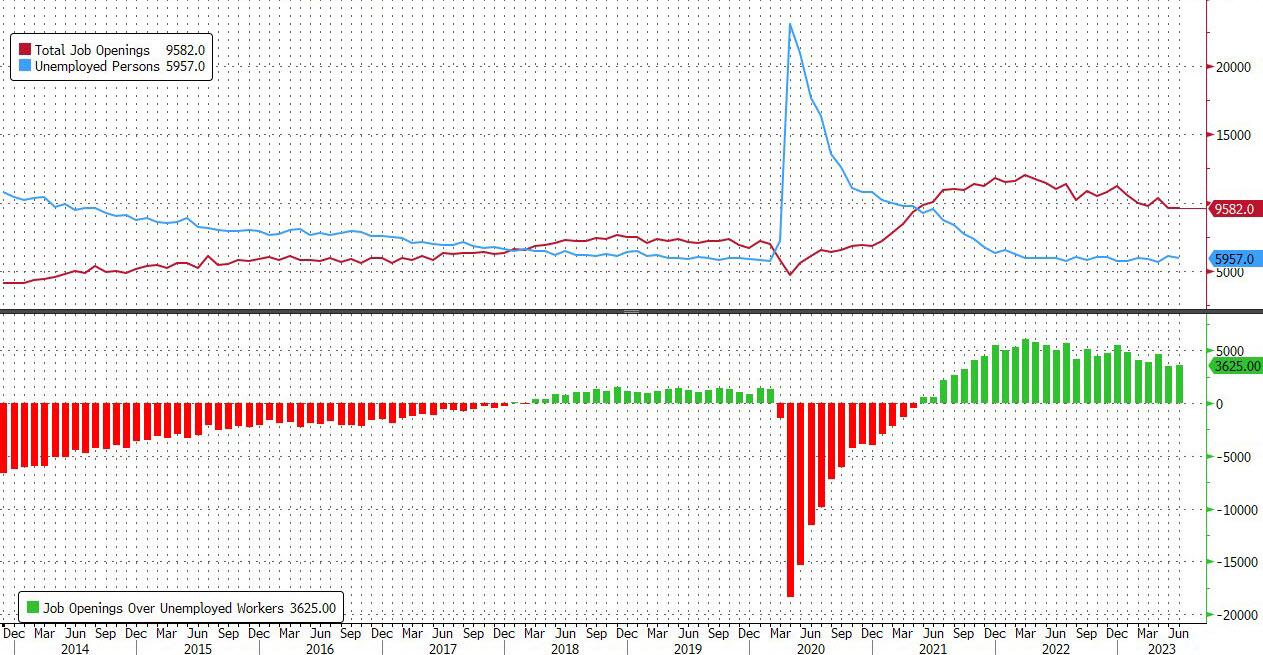
For those enthralled by the narrative that AI will cause a margin-busting corporate revolution as millions of well-paid, middle-management employees are replaced by a cheap “bullshitting” AI algo, then today’s latest JOLTS report may come as a bigger shock than the big drop in job openings from one month ago. That’s because after unexpectedly dumping by 496K in May (a number which has been revised far worse of course), the BLS just reported that in June the number of job openings was practically unchanged, dropping by just 34K, to 9.582MM from a downward revised 9.616 million. And while the monthly change was modest after the downward revision of course, the total was dragged to the lowest level since April 2021.

The number was about 1.4 million below the 11 million from a year ago and below the consensus estimate of 9.6 million, a rare miss in a series which has been best known for decisively beating Wall Street’s expectations.

According to the BLS, the largest increases in job openings was in health care and social assistance (+136,000) and in state and local government, excluding education (+62,000). Job openings decreased in transportation, warehousing, and utilities (-78,000), state and local government education (-29,000), and federal government (-21,000)

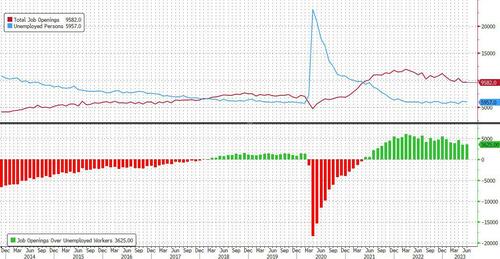
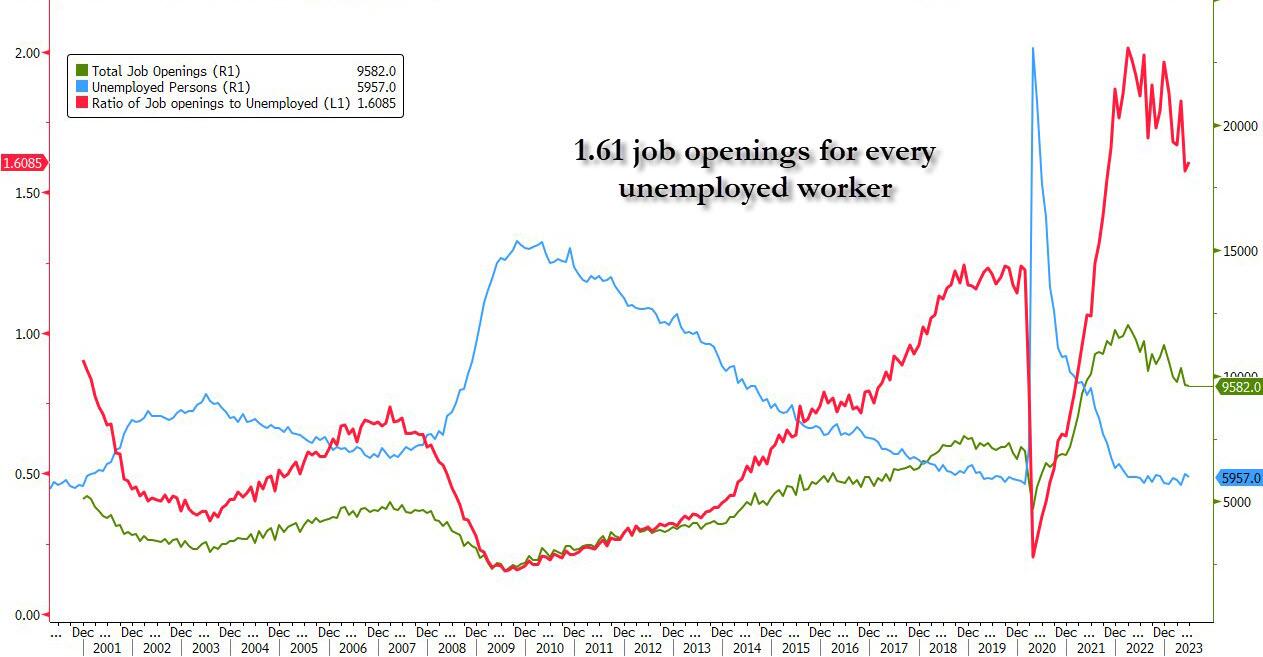
The slide in the number of job openings meant that after rising to the highest since January 2023 in April, in June the number of job openings was just 3.7625 million more than the number of unemployed workers, the lowest since Sept 2021.

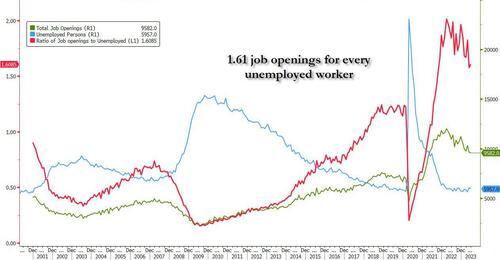
Said otherwise, after rising to 1.82 openings for every worker in April, in June the number dropped to just 1.61, which would have been the lowest level since Oct 2021 if it weren’t for last month’s sharp downward revision.

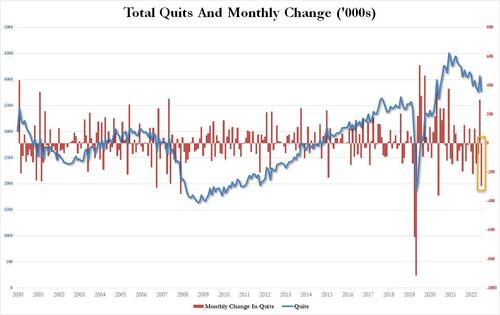
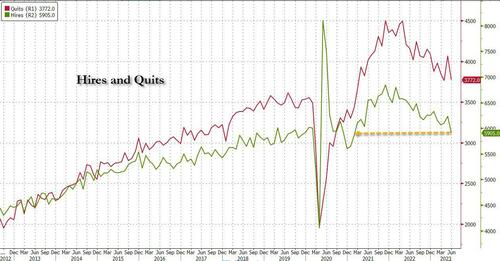
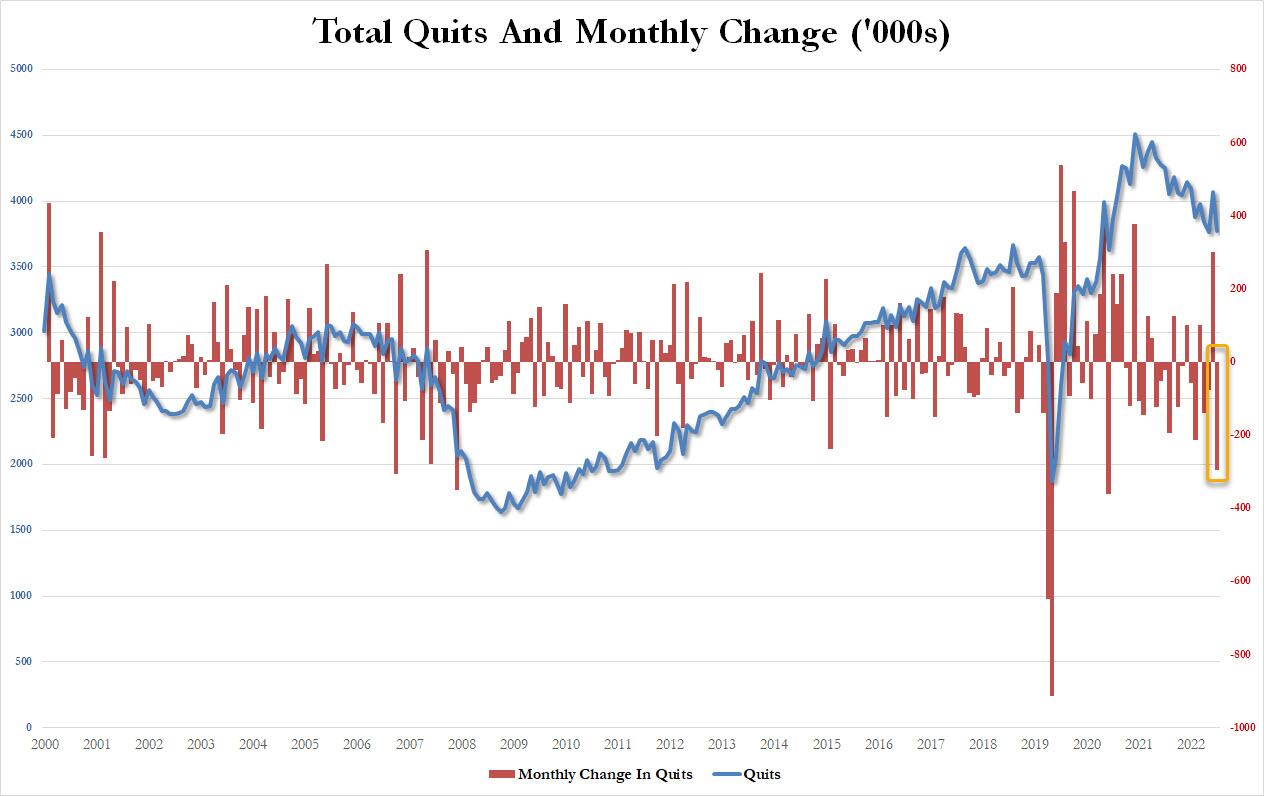
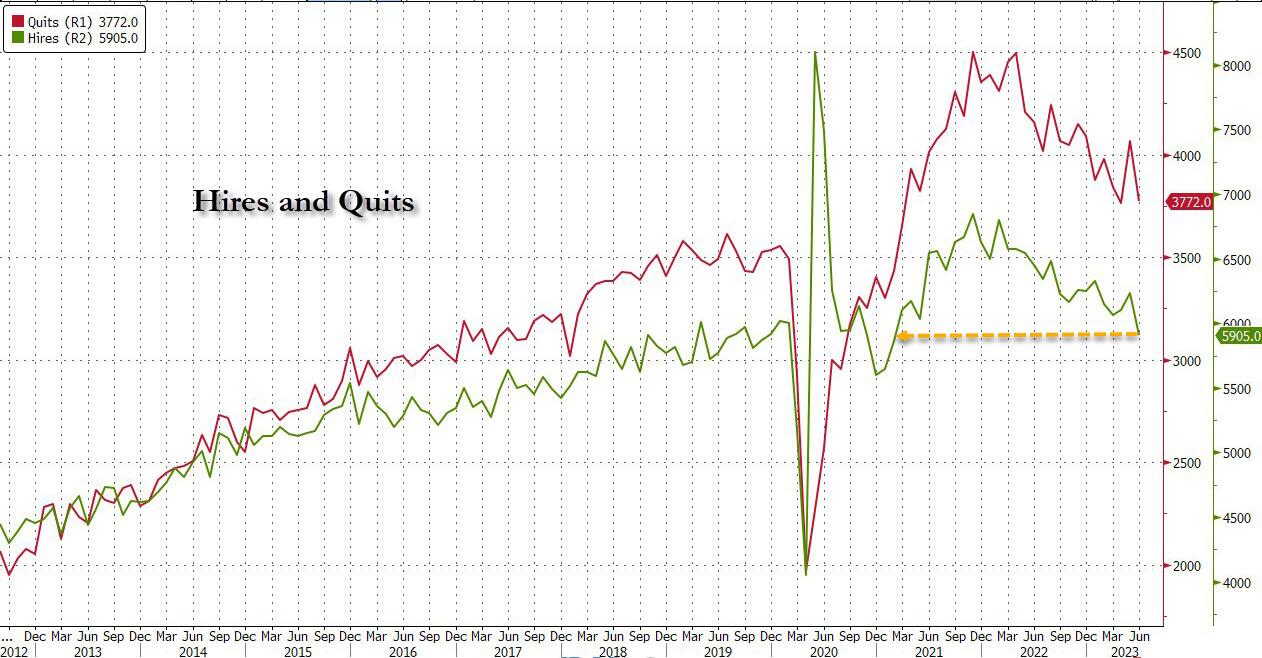
Yet even as the number of job openings dropped only modestly from the (sharply) downward revised print for May (because under Biden, no number is ever revised stronger), conflicting data remained and in June, the number of people quitting their jobs – an indicator traditionally associated with labor market strength as it shows workers are confident they can find a better wage elsewhere – unexpectedly tumbled by 295K to just 3.772MM, the biggest monthly drop since May 2021.

According to the BLS, the number of quits decreased in several industries, with the largest decreases in retail trade (-95,000), health care and social assistance (-75,000), and construction (-51,000). The number of quits increased in arts, entertainment, and recreation (+20,000).

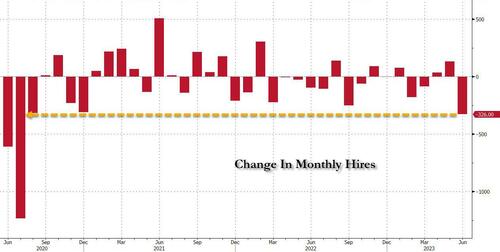
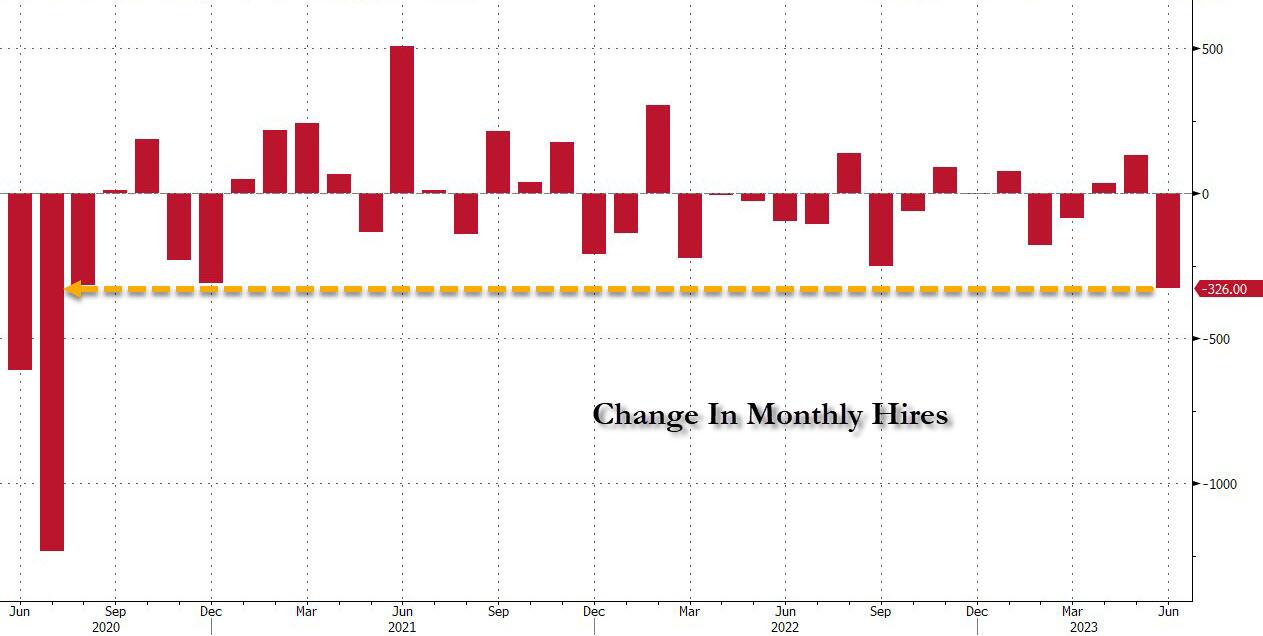
And just in case some still believe Biden’s strong jobs lie, the number of hires also tumbled in June, crashing by 326K – the biggest monthly drop since July 2020…

… to 5.905MM, the lowest since February 2021.

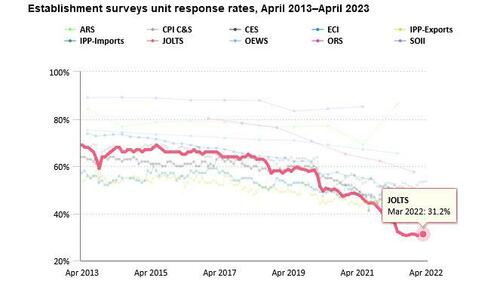
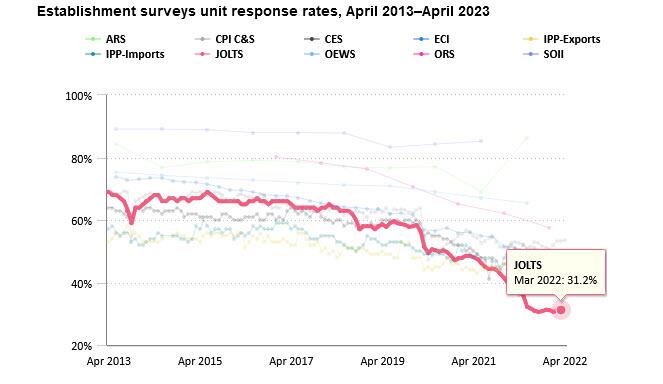
Of course, as we have explained on multiple occasions previously, none of the above data actually matters or is credible for the simple reason that the response rate of the JOLTS survey is stuck at a record low 31.2%. Which means that only those who actually have job openings to report do so, while two-thirds of employers are either non-responsive or their mail is quietly lost in the mail.

Wheels. Of massive corruption and debauchery.

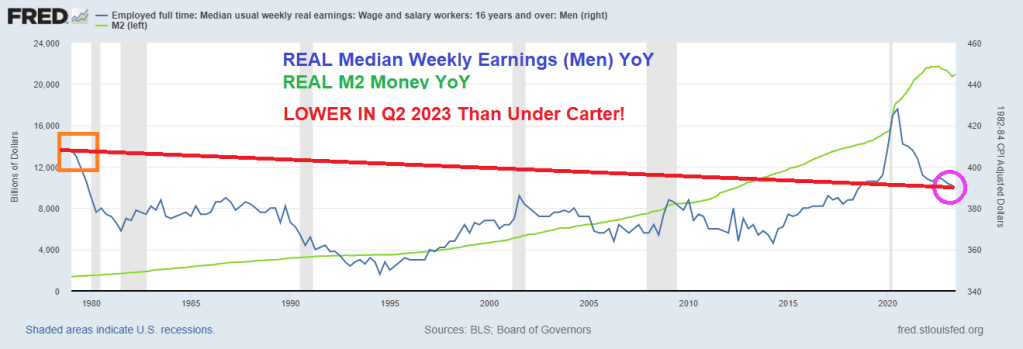
Bidenomics (Or Yellenomics)! Real Weekly Earnings For Men LOWER Under Biden Than Jimmy Carter! (Men’s Real Weekly Earnings DOWN -9% Since Q2 2021 While M2 Money UP 31%)

President Jimmy Carter is usually the bar for terrible Presidents. Under Carter, the US experienced economic stagnation and soaring inflation. At least it led to the election of Ronald Regan!

So, Biden’s much mentioned Bidenomics have produced REAL MEDIAN WEEKLY EARNINGS FOR MEN that is currently below 1979 levels under Jimmy Carter.

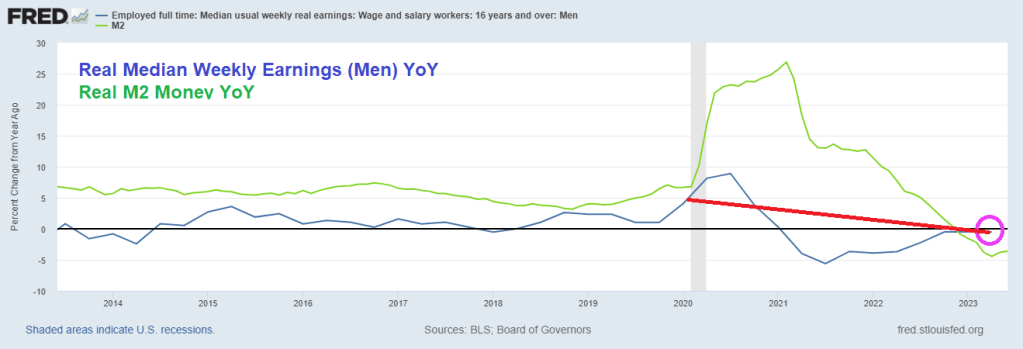
Even worse for Bidenomics, REAL MEDIAN WEEKLY EARNINGS GROWTH FOR MEN was -4.45% In April 2023, while the last reading prior to Covid under Trump was 6.674% YoY in February 2020. So, Bidenomics isn’t even back to Trump levels for men.

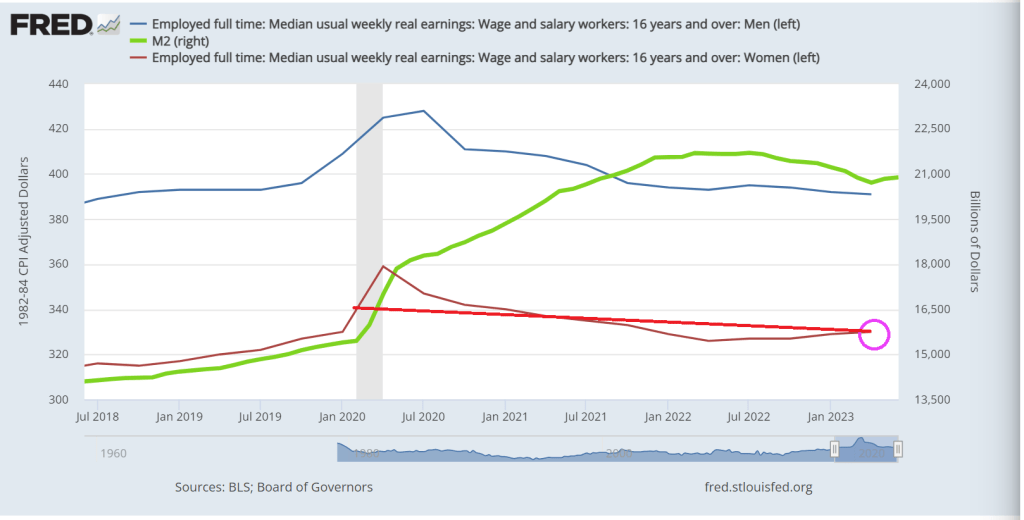
I like this chart which I call “Yellenomics” because it illustrates The Fed’s Folly of money printing and its impact on real earnings. After the Trump wage growth boom, real median weekly earnings for men has been steadily declining.

Women, on the other hand, did show a gain since Carter, but still lower than the last month before Covid struck. Women’s real median weekly earnings growth YoY since Q2 2021 are down -5%. So, Bidenomics has been less sucky for women than men.

Reminds me of The Yardbird’s classic “I’m A Man.” Worse off under Biden than under Jimmy Carter. Although The Yardbird’s “Over Under Sideways DOWN” is more emblematic of Bidenomics.

Bidenomics should be renamed Corruptionomics given Biden’s habit of selling government influence to anyone willing to waive a few million.

Bidenomics? C&I Lending Growth Crashes Along With Bank Credit Growth (WTI Crude Oil UP 1% This Morning) 30-year Mortgage Rates At 7.27%

Bidenomics, aka the Federal government takeover of the US economy with Soviet-style economic central planning, is highly dependent on loose Federal Reserve monetary policy (Janet Yellen and Powell’s wild overreaction to the massively inappropriate Covid shutdowns),

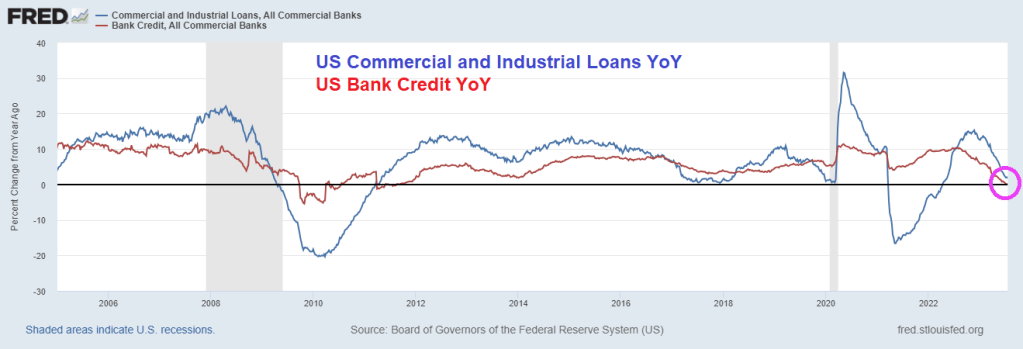
So, how is Bidenomics working out? On the bank lending front, commercial and industrial (C&I) lending growth is crashing along with bank credit growth YoY.

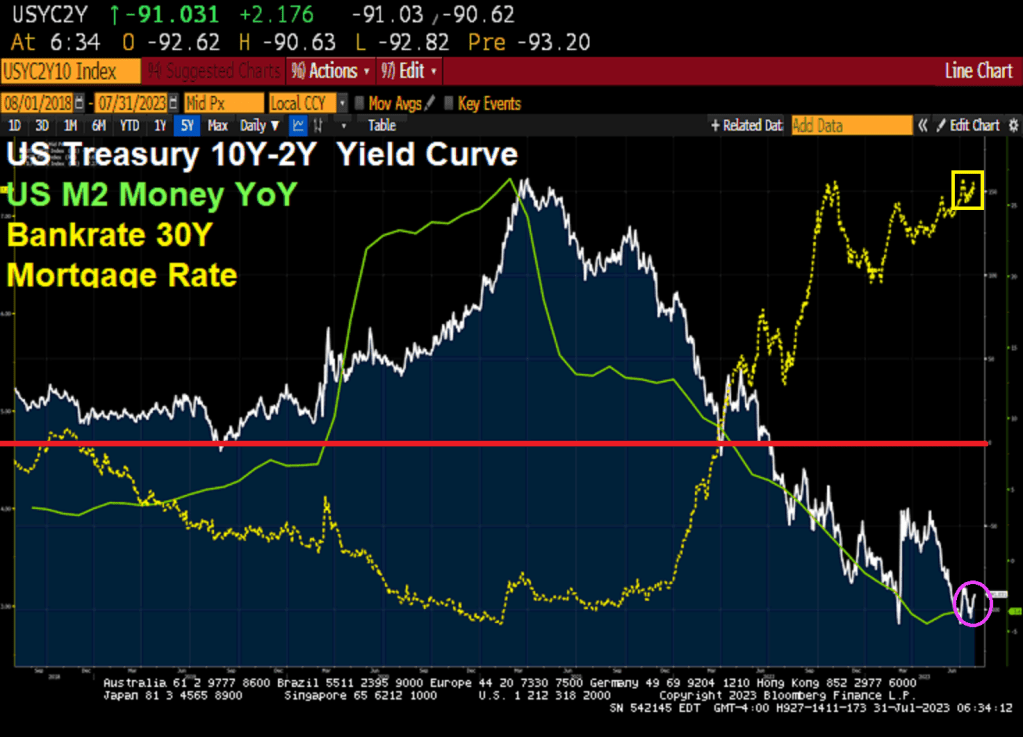
The US Treasury 10Y-2Y yield curve remains deeply inverted at -91.031 basis points and M2 Money growth has crashed. The 30 year mortgage rate is hovering around 7.27%.

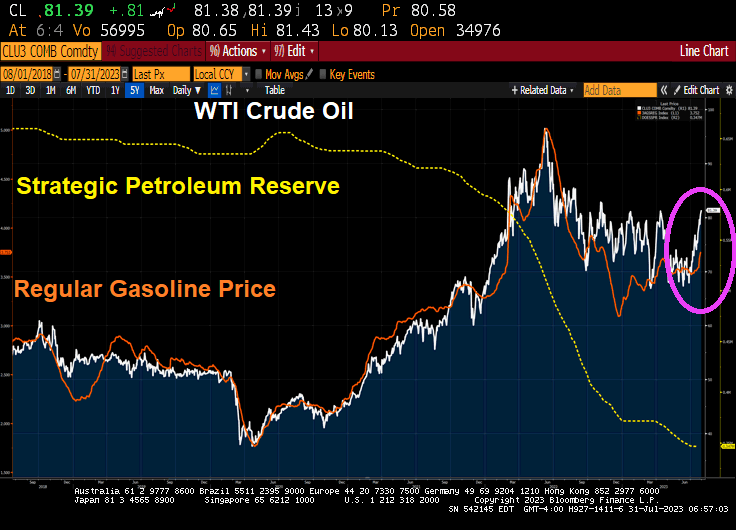
And WTI Crude oil futures are up 1% this morning.

The body of Bidenomics.

Here is a pic of Biden sniffing Idaho.

Republicans Little Red Book! New York, California Tax Revenue Tumbles Amid Exodus To Blue States (Red States FLA, TX Show Incredible Gains In Tax Revenue)

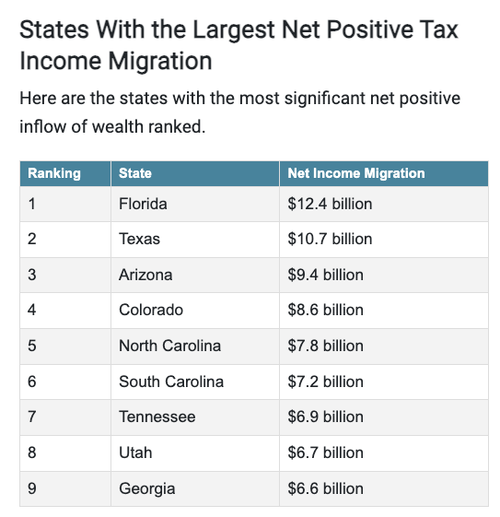
The Republicans’ little red book is showing people escaping big crime and tax states like New York and California for lower tax, lower crime states like Florida and Texas. But to Democrats who are really bad at math, 7+7 = 0?

Most people are already familiar with the mass migration from the Democratic strongholds of California and New York, known for high crime and tax rates. We have delved into this in our article, “Americans Continue To Flee High-Tax New York And California,” highlighting Texas and Florida as preferred destinations.

California and New York have sustained population declines during Covid and after, that have long-term implications for local economies. The exodus means workers with six-figure salaries in technology, finance, real estate, and entertainment are going elsewhere, which will reduce tax revenue for the state. 

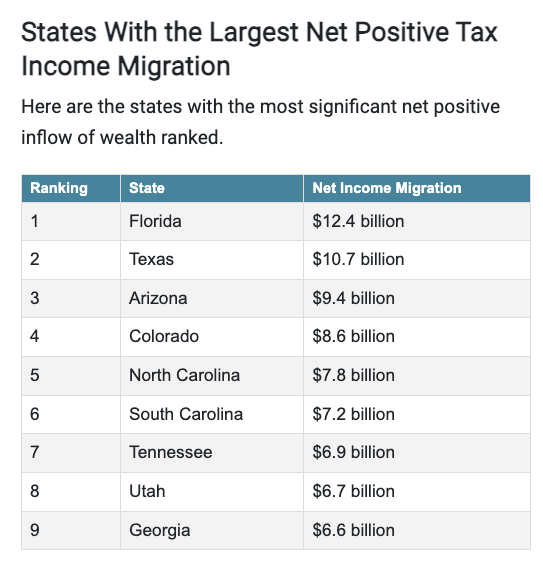
MyEListing.com, an online real estate portal, used IRS migration data to reveal California and New York lost $343 million and $299 million in 2021, respectively, due to the surge in migration outflows. 

The beneficiaries of the outflow are Florida and Texas, which took in $12.4 billion and $10.7 billion, respectively. 

“Despite its numerous attractions, from the booming tech industry and world-class universities to beautiful landscapes and cultural richness, California’s high personal income tax rates seem discouraging for many high-wealth individuals. This, coupled with the state’s high cost of living, will likely fuel a wealth migration out of California,” MyEListing wrote in the report. 

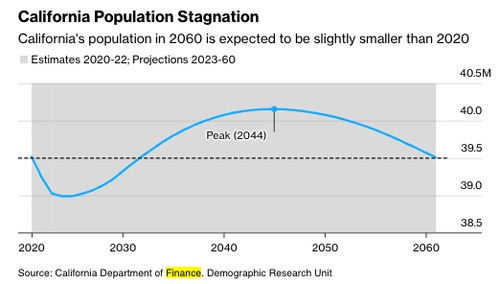
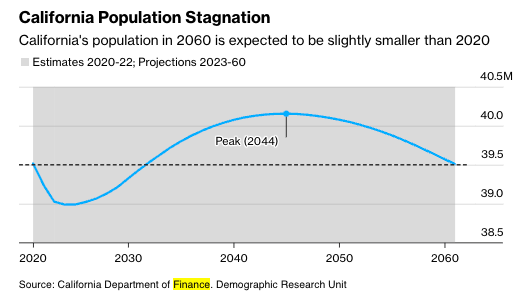
The exodus from California is so severe that state demographers forecasted the total population will be the same today as in 2060. 

If left unchecked, the largest outflows of residents from specific metro areas could experience a fiscal crisis. Such a development would be tragic for Democrat-controlled cities already plunging into crisis as progressive politicians fail to enforce law and order. 

Hey Joe (Biden)! Open up the US to energy independence!!!

Why US Inflation Will Start Rising Again (WTI Crude Futures UP Above $80 Again As Gasoline Futures UP 91.5% Under Bidenomics)

Joe Biden said that Republicans will impeach him in the House of Representatives since inflation is coming down. Huh? No Joe, it is because your are the most corrupt President in history, a compulsive liar and your economic policies are pure World Economic Forum mandates (open borders, Central Bank Digital currency, green energy, etc). Biden started off his Presidency by declaring war on fossil fuels that helped drive prices through the roof. And the middle class are paying the price.

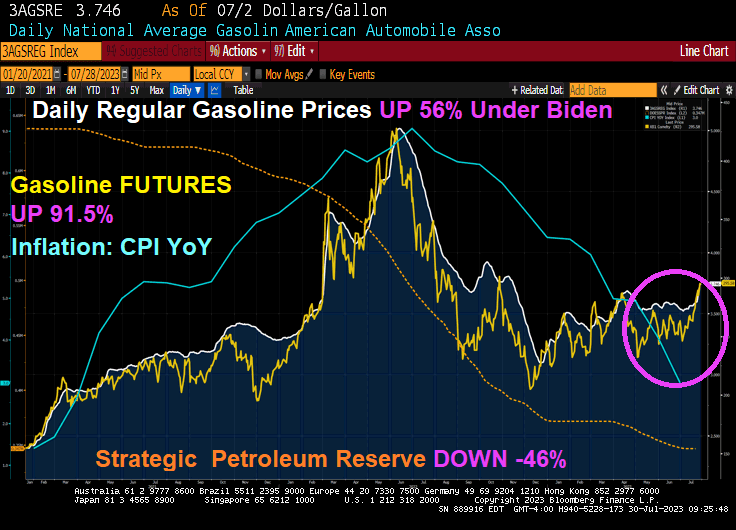
But as inflation cools (blue line) thanks in part to Biden draining the Strategic Petroleum Reserve (orange line), Biden can gloat. But remember, gasoline prices remain 56% higher under Biden’s Reign of Error. Even worse, gasoline FUTURES are up 91.5% under Biden. Yikes!

But look at how gasoline prices and gasoline futures have risen in July (pink circle). The last inflation report showed that inflation has declined to 3% (still higher than The Fed’s 2% target), gasoline prices are up almost 5% since July 19, 2023.

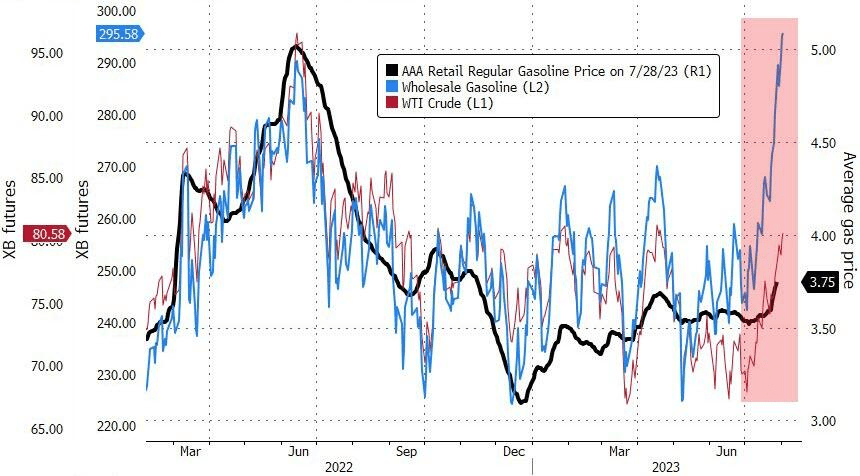
Gasoline, meanwhile, started the year at less than $2.50 per gallon. This week, gasoline topped $2.90 per gallon and may yet reach $3.

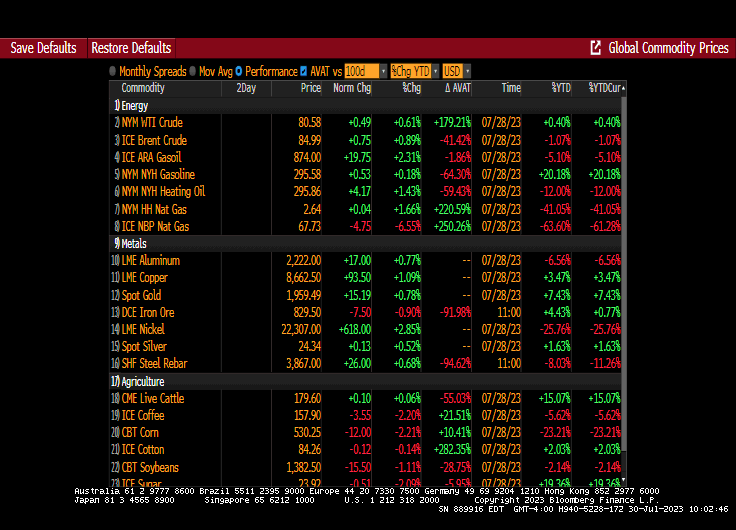
WTI Crude Oil futures have broken through the $80 barrier … again. Heating oil futures are up 1.43% today with WTI Crude futures up 0.61%.

So as energy prices keep rising (and Biden’s EPA keeps issuing green energy edicts and fails to recognize that our power grid can’t support all the electric cars and trucks envisioned by the Obama/Biden green dreamers). As such, energy prices will keep rising and with it … inflation.

US New Home Sales Fall -2.5% MoM In June To 697k Units Sold (Thank The Fed For 23.8% YoY Growth!)

New home sales in June fell -2.5% from May to June to 697k units sold. But on a year-over-year (YoY) basis, new home sales are up 23.8%. Thanks largely to The Federal Reserve slow walking the shrinking of their massive balance sheet.

Too much monetary stimulus and The Fed’s failure to remove the Covid stimulus is now hitting new home sales.

KJP “Hurts So Good” Presser: Prices UP 16.6% And Real Wages Down -3% Since Biden Took Office (Food UP 56%, Gasoline UP 52%, Mortgage Rates UP 153%) Hurt So Good???

Biden Press Secretary KARINE JEAN-PIERRE: “The American people are beginning to feel Bidenomics”

Prices are up 16.6% and real wages are down 3% since Biden took office.

Well, at least Jean-Pierre didn’t claim like her boss Joe Biden claimed that he “ended cancer as we know it.”

But getting back to Jean-Pierre’s claim that “The American people are beginning to feel Bidenomics.” She is right (for once). Americans are REALLY feeling Bidenomics. And it hurts SO BAD!!!

What hurts so bad? Food (CRB Foodstuffs) are up 56% under Bidenomics. Real weekly wage growth is down -90% since Biden assumed office. Regular gas prices are up 52%. And the 30Y mortgage rate is up a staggering 153%. Yes, Karine, this hurts so bad!
While real wages are down -3% under Biden and the real average weekly wage growth is down -90%. That REALLY hurts so good.

But Biden and KJP think that Bidenomics “hurts so good.”

A video of Bidenomics.

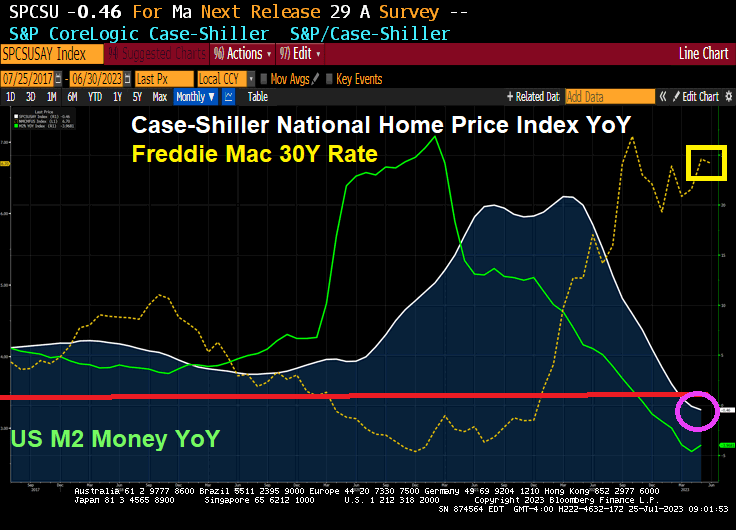
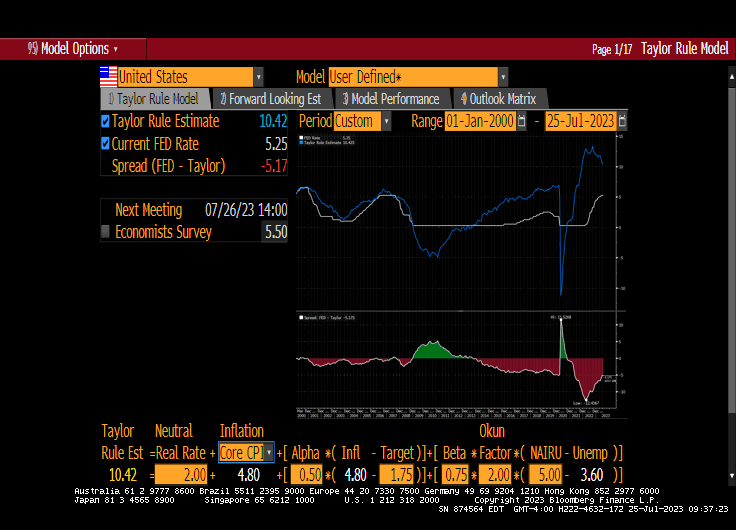
Case-Shiller National Home Price Index Slows To -0.46% YoY As Fed Withdraws Covid Stimulus SLOWLY (Mortgage Rates UP 151% Under Bidenomics, Taylor Rule Suggests Fed Rate Of 10.42%)

The Case-Shiller home price numbers are out for May. The national home price index is down -0.46% YoY as The Fed slows M2 Money growth into negative growth territory. No doubt Biden (and Karine Jean-Pierre) will take credit for slowing home price growth, although The Federal Reserve slowing monetary stimulus is mostly responsible.

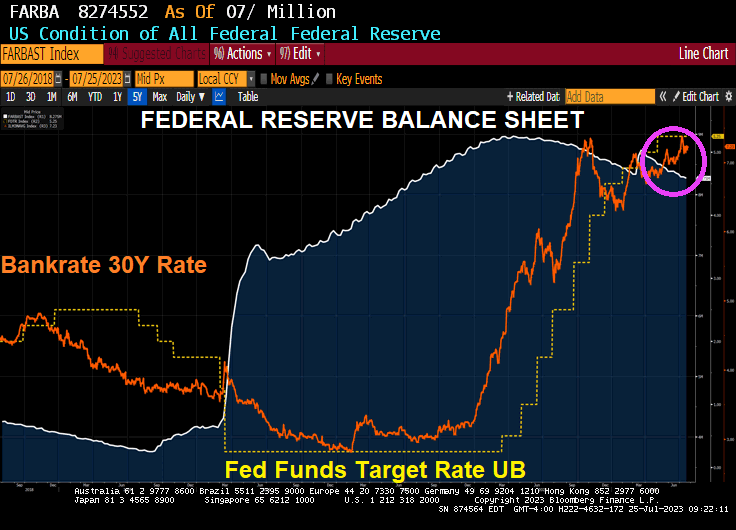
The Fed is still slow walking shrinking its enormous balance sheet. Although The Fed is cranking up their target rate.

The Taylor Rule suggests a 10.42 target rate to cool inflation. They are only half way there!!!