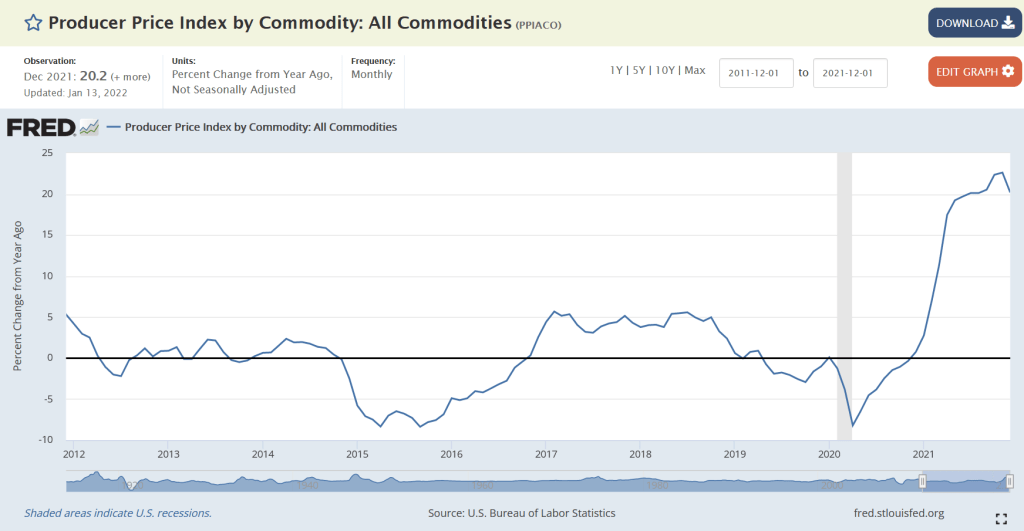
I thought the last inflation report of 7.5% inflation was bad. But then the Atlanta Fed updated their inflation measure for flexible prices. Flexible inflation, less food and energy, is roaring at 19% YoY!
Flexible prices are those prices that adjust rapidly. Along with commodity prices.
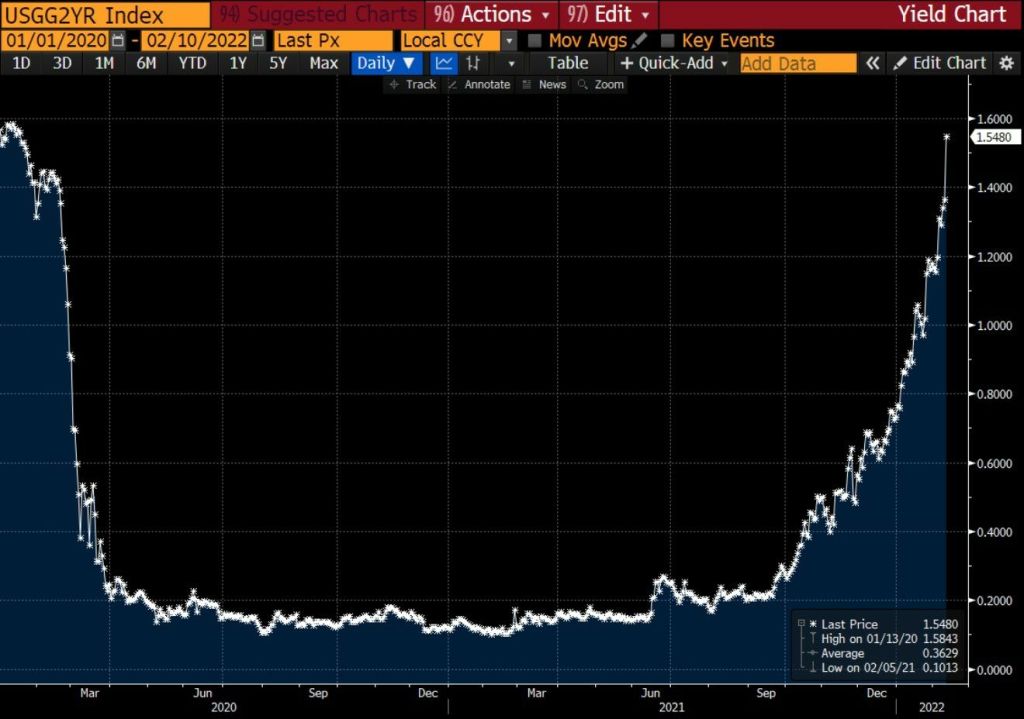
Speaking of rapid rises, take a look at the 2-year US Treasury yield since COVID struck in early 2020.
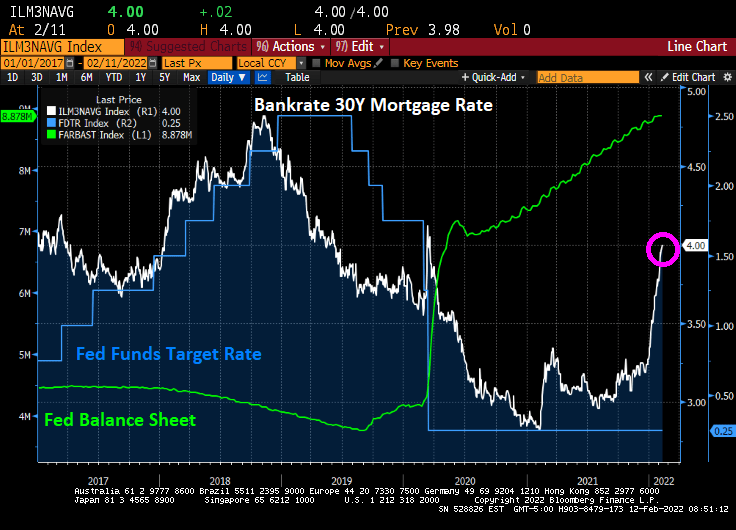
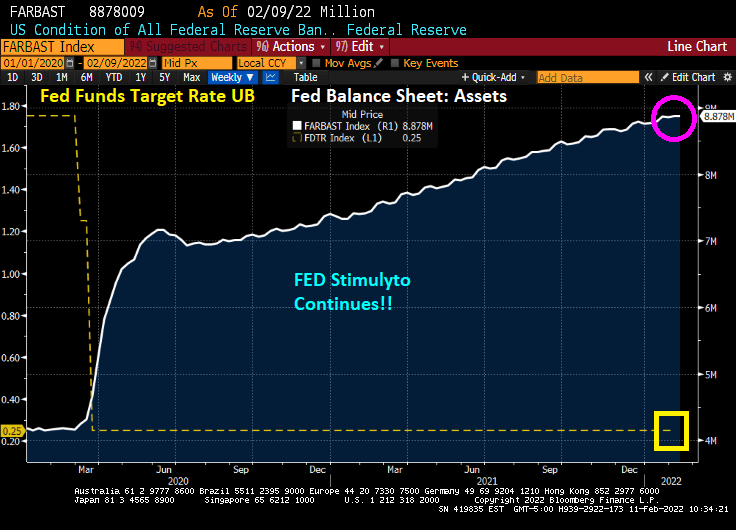
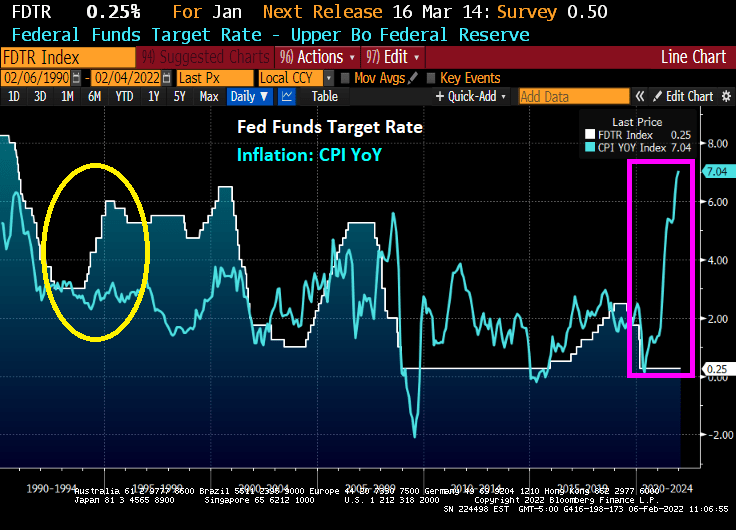
We did see 2-year Treasury yields generally correlated with The Fed Funds Target Rate … at least until COVID struck. Since mid-2020, The Fed Funds Target Rate remains at 0.25% while the 2-year Treasury yield is roaring back with fuzzy expectations from The Fed’s leadership.
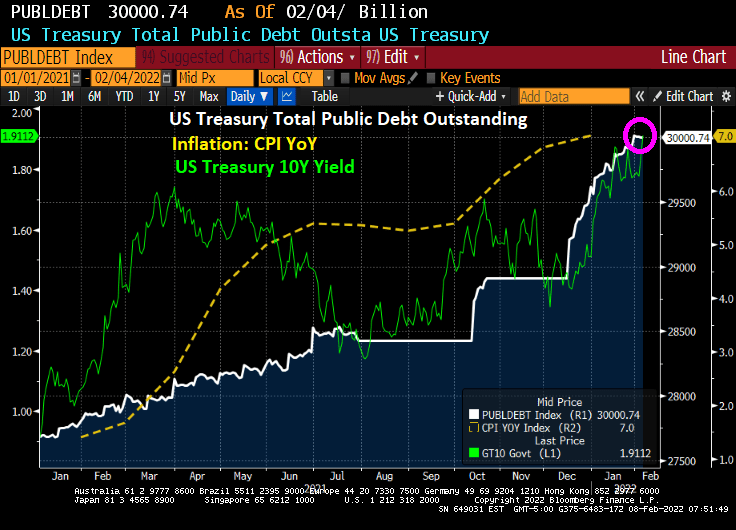
The 10-year Treasury yield is not rising as rapidly as the 2-year Treasury yield, but it is hovering around 2%.
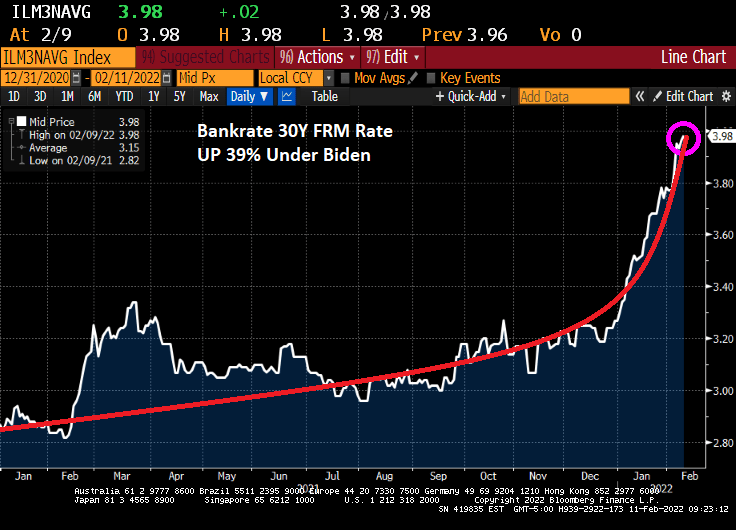
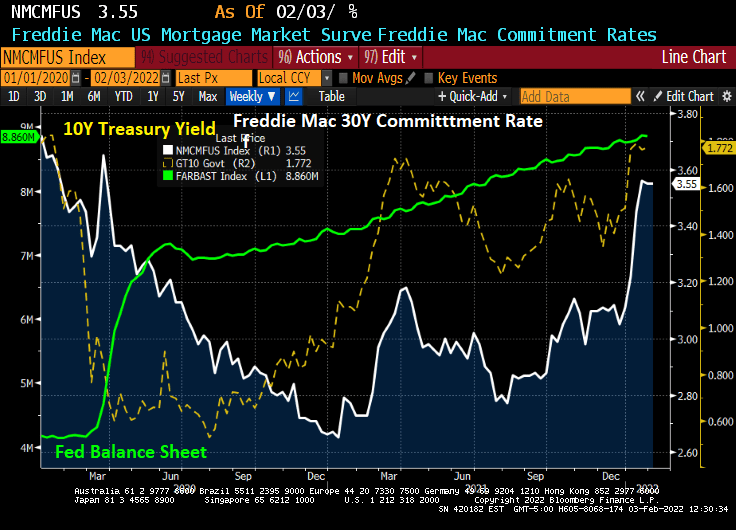
But Bankrate’s 30-year mortgage rate is rising like a comet, similar to the 2-year Treasury yield.
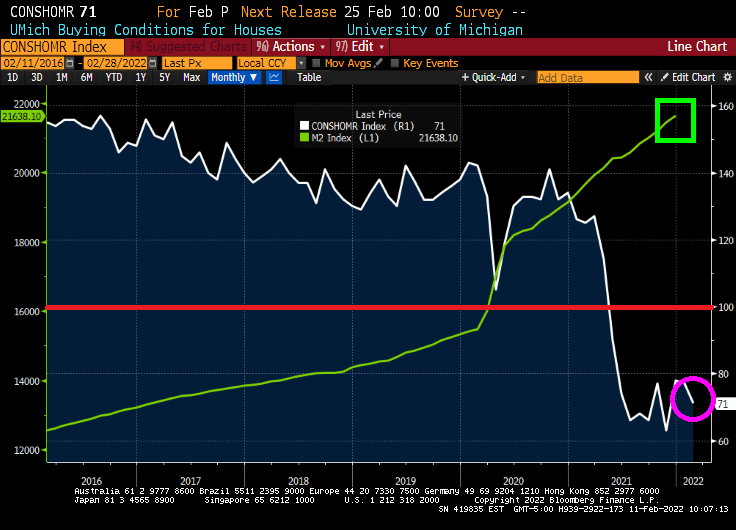
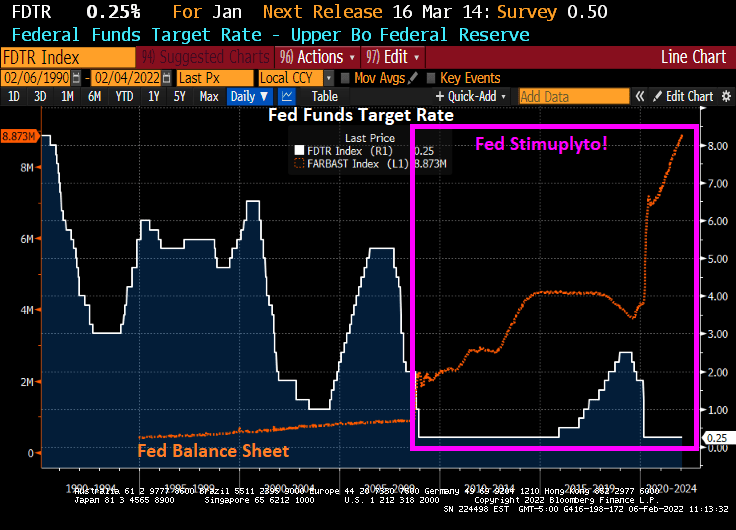
The University of Michigan consumer survey is out for February. And an ugly survey is it! Buying conditions for housing fell to 71 as The Federal Reserve continues it monetary stimulypto!
Despite 7.5% inflation, The Fed continues its “Stimulytpo” monetary policy.
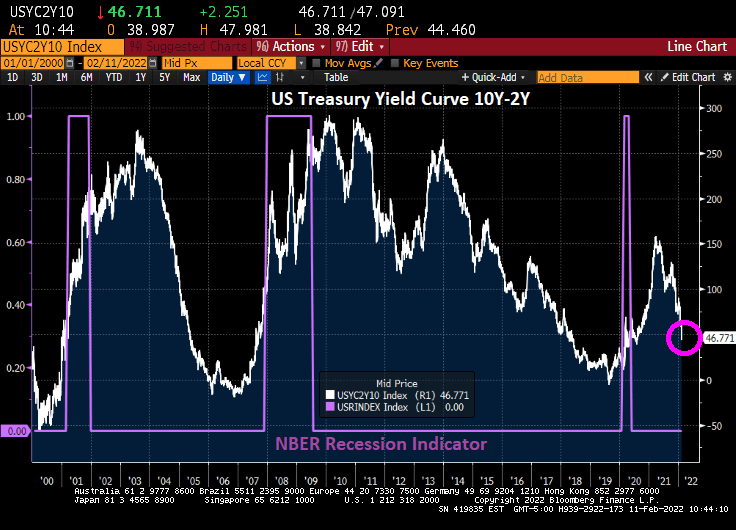
US consumer confidence is the lowest in 10 years as the yield curve crashes.
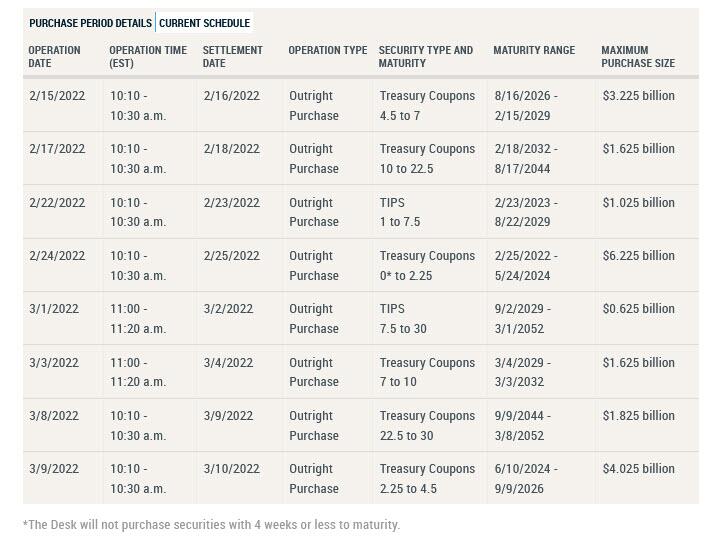
Here is the POMO schedule just released by The Fed.
I am reminded of my roommate at University of Wyoming who played James Brown over and over and over again. Much like The Fed doing nothing to curb inflation. Until they finally do something with a crashing yield curve.
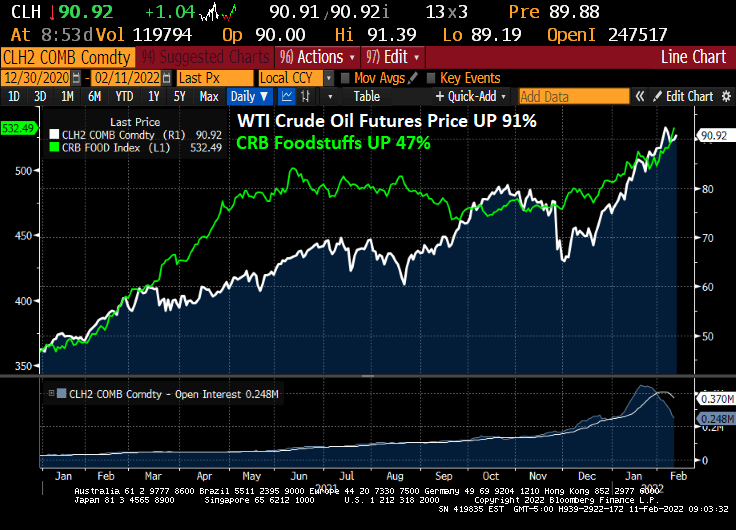
Well, it has been a cringe-worthy year+ under President Biden. West Texas Intermediate Crude futures price is up 91% and the Commodity Research Bureau Foodstuffs index is up 47%. Talk about Biden’s energy folicies being passed through to American households in the form of higher food costs and energy prices!
And then we have mortgage rates. Bankrate’s 30Y mortgage rate is up to almost 4%, up 39% since the beginning of 2021.
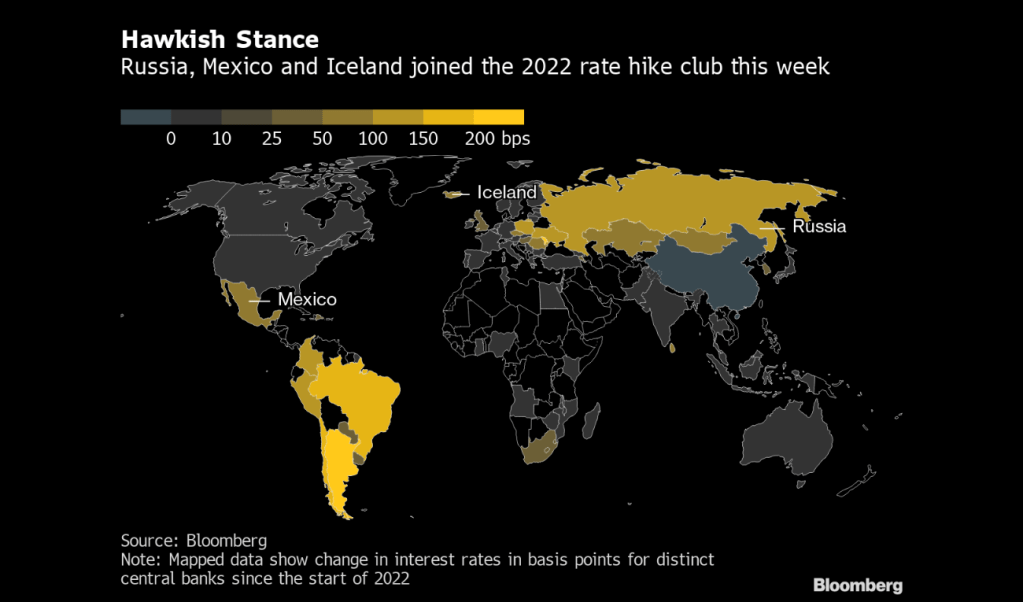
Other central banks are raising rates like banshees on the moor, while The Federal Reserve continues to send conflicting signals about possible March rate hikes.
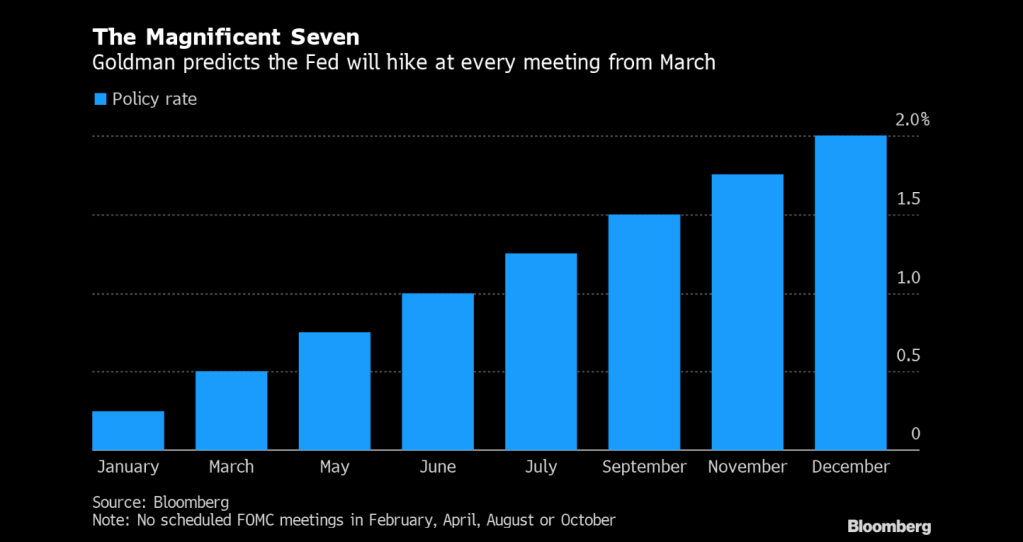
Goldman Sachs sees 7 rate hikes in 2022, culminating in an eventual 2% rate in December.
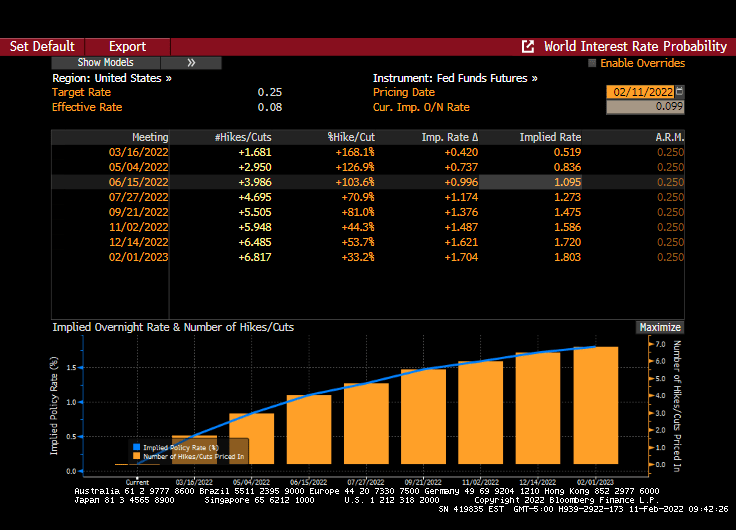
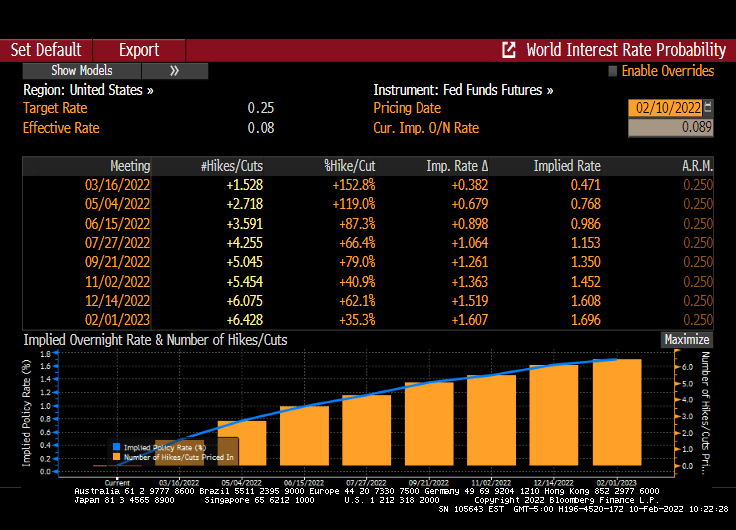
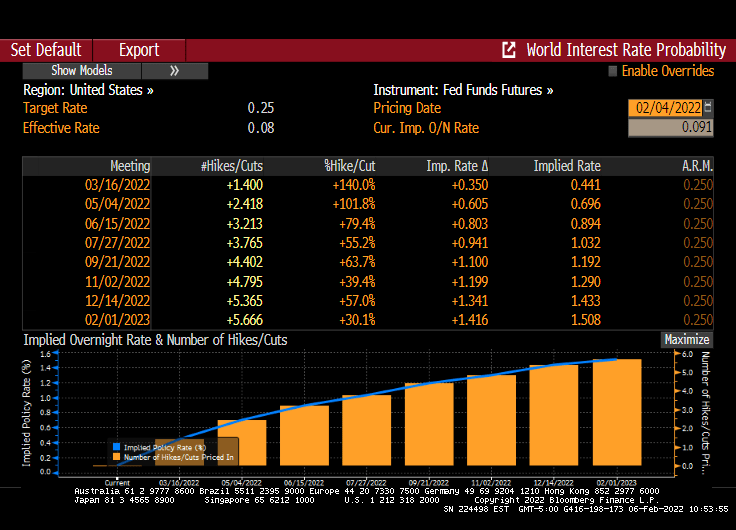
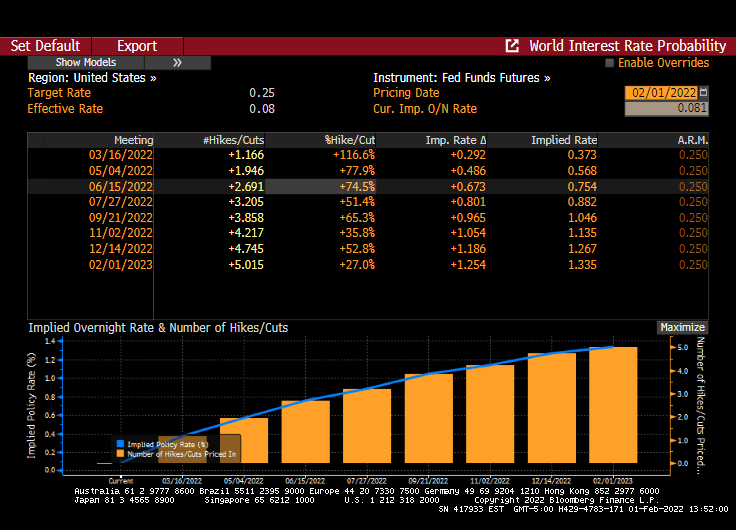
Fed Funds Futures are signalling 7 rates increases by the February 1, 2023 meeting.
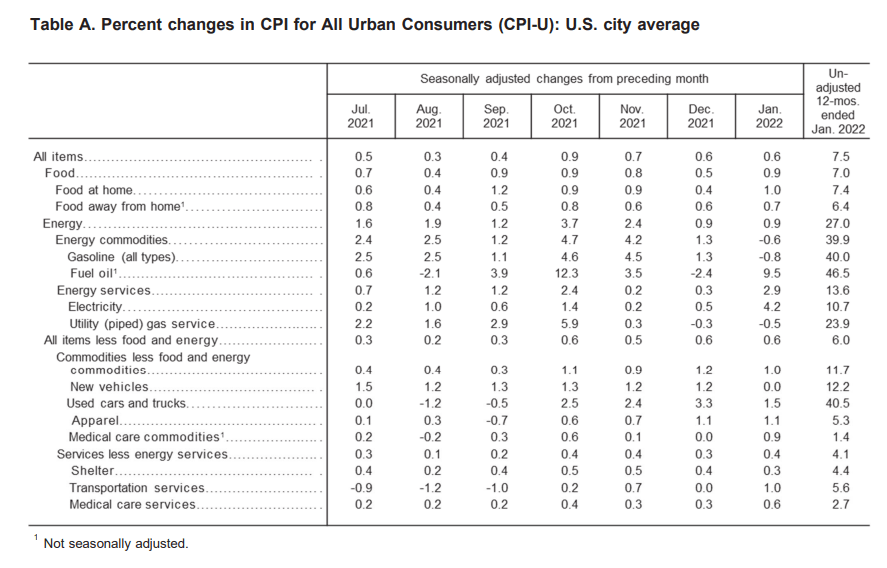
As expected, US inflation surged from 7.0% in December to 7.5% in January.
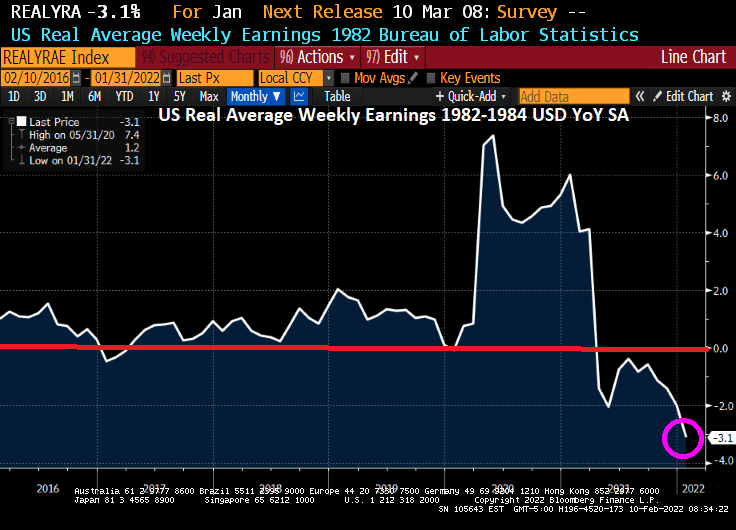
REAL average weekly earnings growth YoY fell to -3.1%.
Energy prices YoY lead the wage (fuel oil UP 46.5% YoY). Used cars and trucks UP 40.5%. At least food is up “only” 7%.
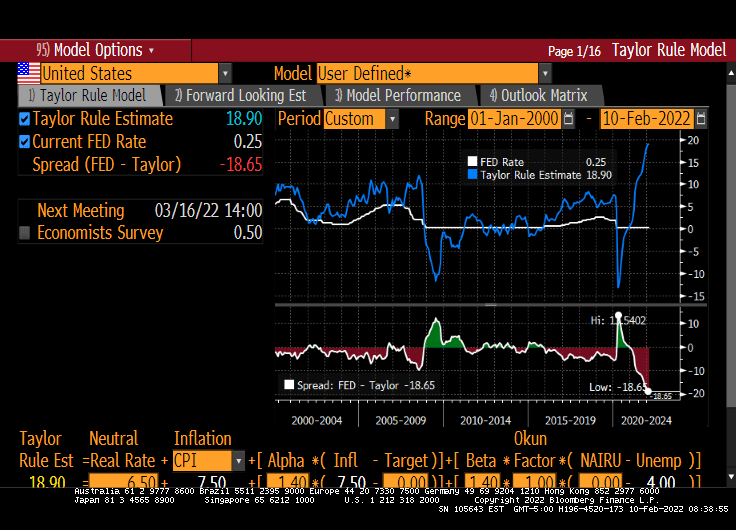
At 7.5% CPI, the Taylor Rule suggests that The Federal Reserve should have their target rate be 18.90%.
At least CORE inflation is “only” 6% YoY.
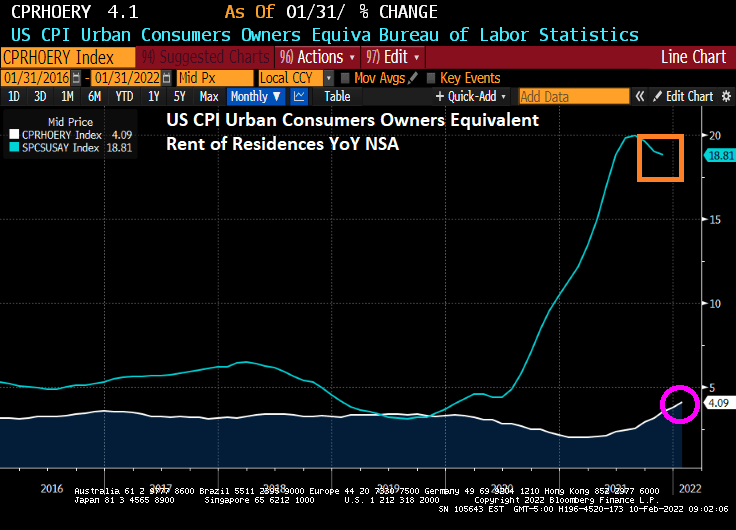
How about rent CPI? The owner’s equivalent rent of residences rose to 4.09% YoY. Seems a little misleading since home prices nationally are growing at 18.81% YoY.
Fed Funds Futures data points to 6-7 rate HIKES over the coming year. BRACE FOR IMPACT!!
Yes, this is Powell’s famous chili recipe if The Fed actually starts to raise rates and pare back the balance sheet stimulus.
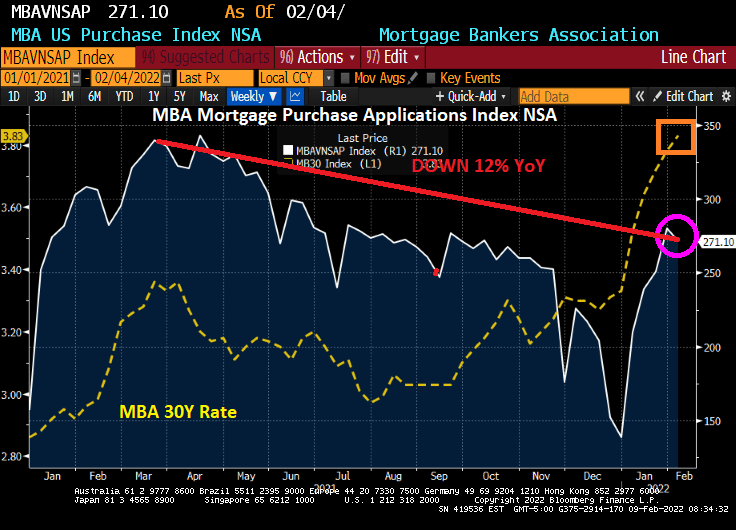
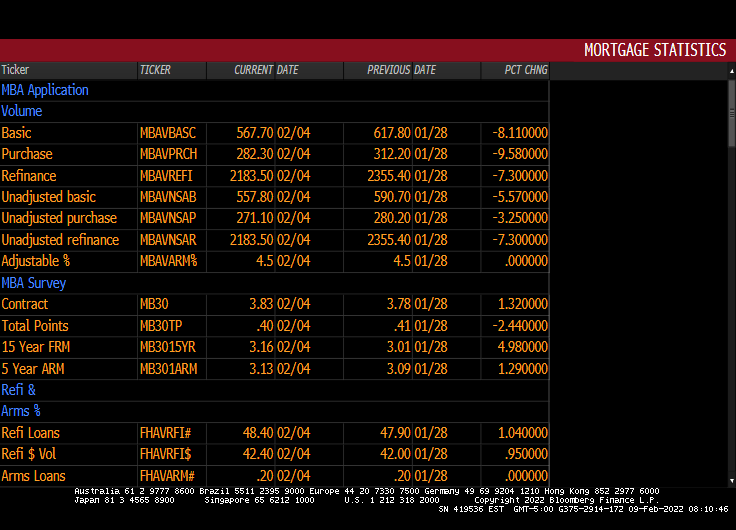
The Mortgage Bankers Association (MBA) released their weekly mortgage application survey this morning. Mortgage applications decreased 8.1 percent from one week earlier, for the week ending February 4, 2022.
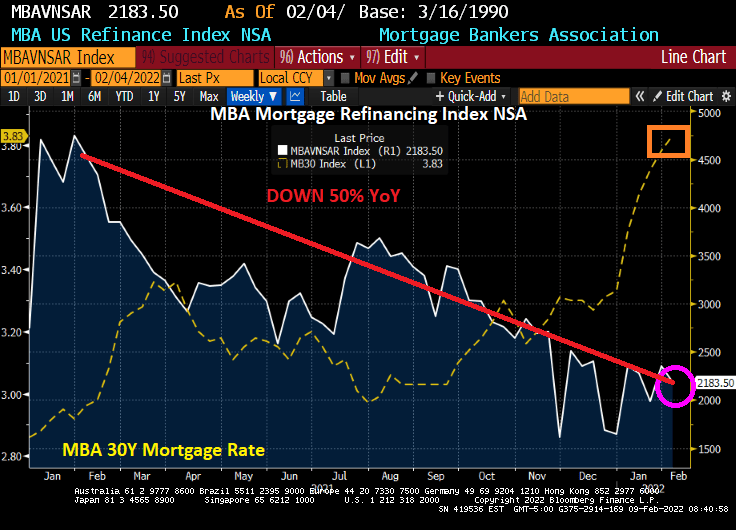
The Refinance Index decreased 7 percent from the previous week and was 52 percent lower than the same week one year ago. The seasonally adjusted Purchase Index decreased 10 percent from one week earlier. The unadjusted Purchase Index decreased 3 percent compared with the previous week and was 12 percent lower than the same week one year ago.
And mortgage refinancing applications are down 50% since the same week last week.
Here are the stats. Pretty much down across the board.
Once upon a time, European PIGS (Portugal, Italy, Greece and Spain) saw incredible spikes in their sovereign yields related to Greek credit default contagion. But the European Central Bank (ECB), World Bank (WB), International Money Fund (IMF) rose to the rescue.
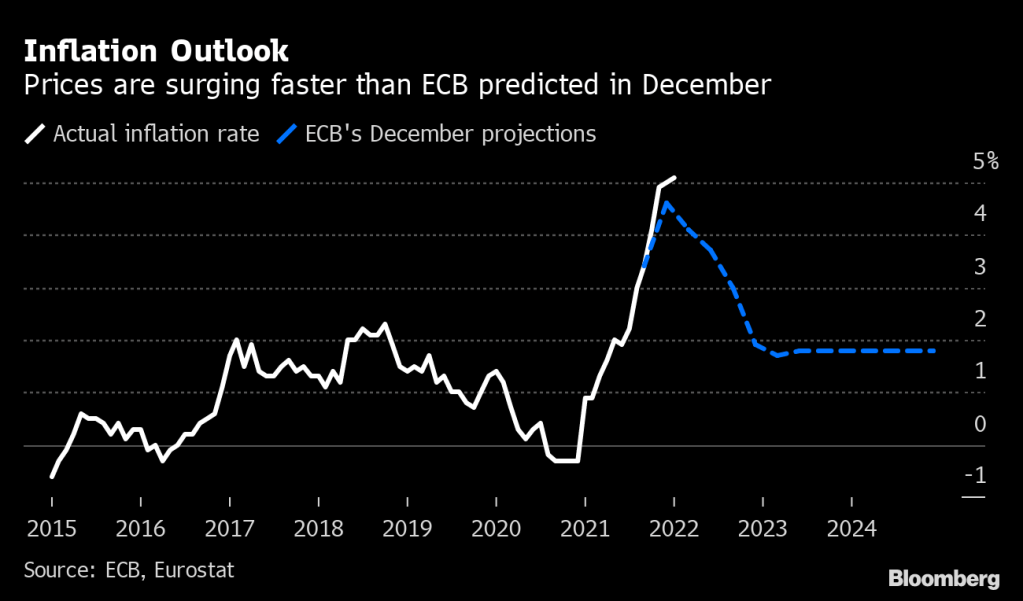
But here we go again! Thanks to rising inflation, the ECB is threatening to remove the massive monetary stimulus. Sound familiar??
Here are the Eurozone 10-year sovereign yields as of this morning. Greece is up a whopping 27.4 basis points, Italy is up 11.7 BPS, Portugal is up 9.3 BPS and Spain is up 9.2 BPS. The core of the Eurozone, France and Germany, are up 4.3 and 3.0 BPS, respectively.
Germany has REAL 10Y Bunds yields of -4.7%.
Like the USA, the Eurozone Taylor Rule is much higher than the ECB’s Main Refinancing rate of 0%..
Here is ECB’s Christine Lagarde saying “What, me worry??”
(Bloomberg) What a difference 25 years makes. Worried that inflation was about to turn higher, the Federal Reserve in February 1994 began raising interest rates, taking the federal funds rate from 3% to 6% a year later. As it turned out, those worries were unfounded: The U.S. consumer price index barely budged, finishing the year at 2.7%, right where it had started.
Although inflation in many developed-world countries is now well above those levels — 7% in the U.S. alone — of the major central banks only the Bank of England has started to raise short-term rates. They are now, um, 0.25%. Across the developed world, short rates are still either barely above zero or negative. What’s more astonishing is that even though they have cut their purchases, the Federal Reserve and European Central Bank continue to buy about $140 billion of longer-maturity bonds every month, suppressing long-term yields even as inflation rages.
Some central banks say that rate hikes are coming, but their extraordinary reluctance to deal with actual inflation means it will become entrenched. Not only will policy makers have to raise rates more than they envision, but they will have to cut the size of their massive balance-sheet assets, too. Don’t expect that the process will be anything other than awful for risky assets of all stripes.
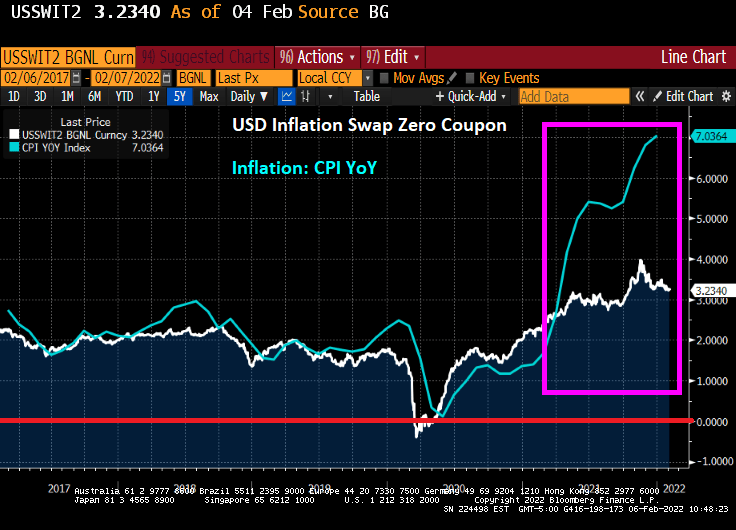
Over the last year and a half, inflation has not only accelerated but also broadened. It started with goods prices and has now expanded to services, even in the moribund euro zone. Central bankers and markets still believe inflation rates will come down a lot. The part of the swaps market that in essence predicts inflation in the future is pricing in a drop in the U.S. CPI to 3.6% by the spring of 2023 and to 3.25% the year after. Alas, like central bankers, the inflation swap market’s record is dreadful. In late spring of 2020, markets predicted a CPI of minus 1.35% a year later and staying below zero by the spring of 2022.
The US DollarInflation Swap is a poor predictor of inflation, at least under President Biden.
I’m not suggesting inflation will remain at current nosebleed levels. More likely is that having had a couple of decades of headline inflation that was on the low side — for central bankers, but not for anyone else — we are in for a few years when it remains above their targets.
Short rates will of course need to rise. That is problem enough for markets, but the bigger problem comes from the trillions of dollars of assets that central banks have accumulated on their balance sheets. Taken together, the Fed, ECB, Bank of Japan, Bank of England and Swiss National Bank have some $27 trillion of assets. In 2007, before the global financial crisis, the combined total was a little more than $4 trillion. Central bank assets will stop growing this year, undermining a major source of support for all types of bonds. But if inflation remains persistently high, central banks won’t simply be able to let their assets roll off as they mature, as most assume. They will have to start selling them. That is the big problem.
Central banks resorted to buying bonds and other financial assets (so-called quantitative easing) for a few reasons. The main one was to drive up inflation and inflation expectations from uncomfortably low levels by injecting more liquidity into the financial system and driving down longer-dated yields. Now that central banks have got much more inflation than they wanted, they will, by the equal and opposite token, need to sell the assets they bought. The longer inflation remains at current levels, the greater the pressure to sell. And they will probably need to do so sooner and faster than most expect and at prices a lot lower than they fetch today. The Fed alone owns about 30% of all the notes and bonds issued by the U.S. Treasury Department.
To say that central bank purchases have had a large effect on yields would be an understatement. One way of seeing this is to split the yield of a longer-dated bond into the part that reflects the expected path of interest rates over the life of the security from everything else. That “everything else” is the term premium. This should compensate investors for, say, sudden surges in inflation. Clearly, this is no longer true. Depending on what model you use, the term premium on 10-year Treasury reached a high of 450 basis points to 500 basis points in the early 1980s. At the nadir of the pandemic, it was minus 100 points and is now about minus 10 points. To be clear, this means that you get less buying a 10-year Treasury than would be suggested by the expected path of rates over the life of the bond — expectations that are almost certainly too low.
Term premiums below zero suggest bond investors are no longer compensated for things like inflation.
The driving down of government bond yields also compressed yields and spreads on investment-grade and junk bonds. That was the intent. Junk spreads reached their narrowest level ever in June of last year. With so little yield available in fixed income and central banks seemingly always on hand to bail them out, investors flooded into equities. As a result, many developed-world equity indexes are either very expensive or, in the case of the U.S., not far off their most expensive levels ever based on valuation measures that are a decent guide to future returns. That is what a decade and a half of market manipulation by central banks has done.
The policies of zero or negative rates and seemingly infinite QE looked idiotic (and were) when they were adopted, and time has not been kind. Paradoxically, they could only be sustained if central banks were wrong, and their policies failed to spark inflation. Now that inflation has taken hold, rates will go up substantially and balances sheets will need to shrink.
What would you pay for fixed-income assets now if you knew that central banks will become, in effect, forced sellers later? I can’t see how any financial asset will escape the damage from the likely lurch higher yields. The way out of these policies will be as nasty as the way in was nice.
Particularly since Fed Funds Futures are pointing toward 6 rate increases over the next year.
At least Treasury Secretary Janet Yellen is wearing her Mao jacket.
(Bloomberg) — European Central Bank President Christine Lagarde is no longer ruling out an interest-rate hike this year, a pivot toward the tightening stance of global peers that officials privately see materializing with a shift in policy guidance as soon as next month.
Investors brought forward bets on ECB action as the monetary chief delivered surprisingly hawkish comments citing unexpected record inflation data, contrasting with an earlier statement on Thursday that kept intact its formal view that price increases will ease.
She spoke after policy makers agreed that it’s sensible no longer to exclude a rate move in 2022, and that bond buying could end in the third quarter, according to officials familiar with their thinking who asked not to be identified because such discussions are confidential. An ECB spokesman declined to comment.
The result of Lagarde’s jaw boning?
US mortgage rates are rising in anticipation of the US following Largarde’s lead. Powell and the Gang continue to lag.
(Bloomberg) — The White House is lowering expectations for this week’s U.S. jobs report, saying that brief absences of workers due to omicron could overstate the number of unemployed people for last month.
Several White House officials have teed up Friday’s report with warnings, saying that the week when surveys were taken for the January payroll numbers was the height of illness absences in the aftermath of the holidays.
Brian Deese, the director of President Joe Biden’s National Economic Council, said the numbers could be “confusing” as Covid illnesses are recorded as job losses.
“We expect that that will have an impact on the numbers,” Deese told MSNBC on Tuesday. “We never put too much weight on any individual month; this will particularly be true in this month, because of the likely effect of the short-term absences from omicron.”
Biden has repeatedly touted employment data as an indicator of a robust economic rebound, and highlighted the tumbling jobless rate to blunt criticisms about overheated inflation. Friday’s report may still show historically low unemployment, which is based on a separate survey from the one for payrolls and counts temporary, unpaid sick leave differently.
LaborSecretary Marty Walsh and White House Press Secretary Jen Psaki have also delivered warnings that the official January jobs gain may be poor.
If a worker was out “and did not receive paid leave, they are counted as having lost their job,” Psaki said Monday. Nearly 9 million people missed work due to illness in January, when the data were being collected, she said.
“So we just wanted to kind of prepare, you know, people to understand how the data is taken,” she said. “As a result, the month’s jobs report may show job losses in large part because workers were out sick from omicron.”
Economists expect nonfarm payrolls to rise by 150,000 for January — the weakest reading since the end of 2020. The U.S. unemployment rate is seen remaining unchanged, at 3.9%, according to the median estimate of forecasts compiled by Bloomberg.
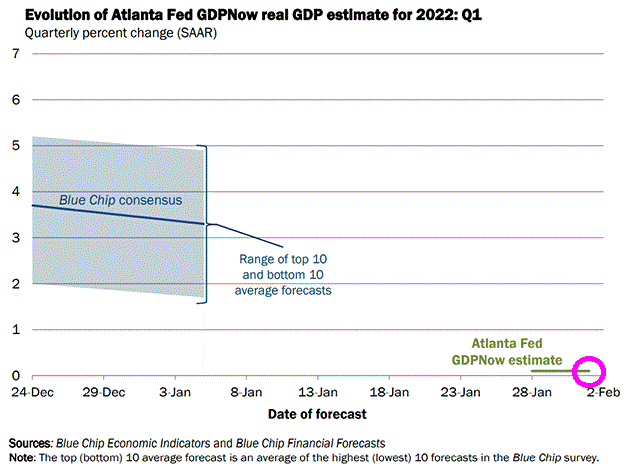
So, are Dreese and Psaki saying that US GDP will roar back … from 0.1% … if Omicron fades away? And that all the fiscal and monetary stimulypto are going to cease creating problems??
Despite the fear of Omicron in the upcoming jobs report, there are still 5 rate hikes on the horizon to combat inflation … created by the Biden Administration and Federal Reserve as they combated COVID with massive fiscal and monetary stimulus.
But don’t worry, the Biden Administration ordered rapid test kits from China … and they have arrived!
















 Confounded Interest - Anthony B. Sanders

You must be logged in to post a comment.