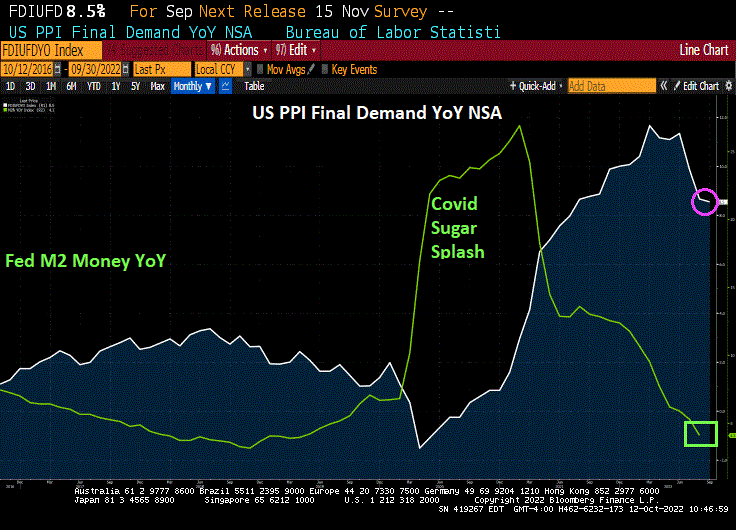
The US Producer Price Index (Final Demand) printed at a higher than expected 8.5% YoY, throwing cold water on the notion that inflation is “transitory.”
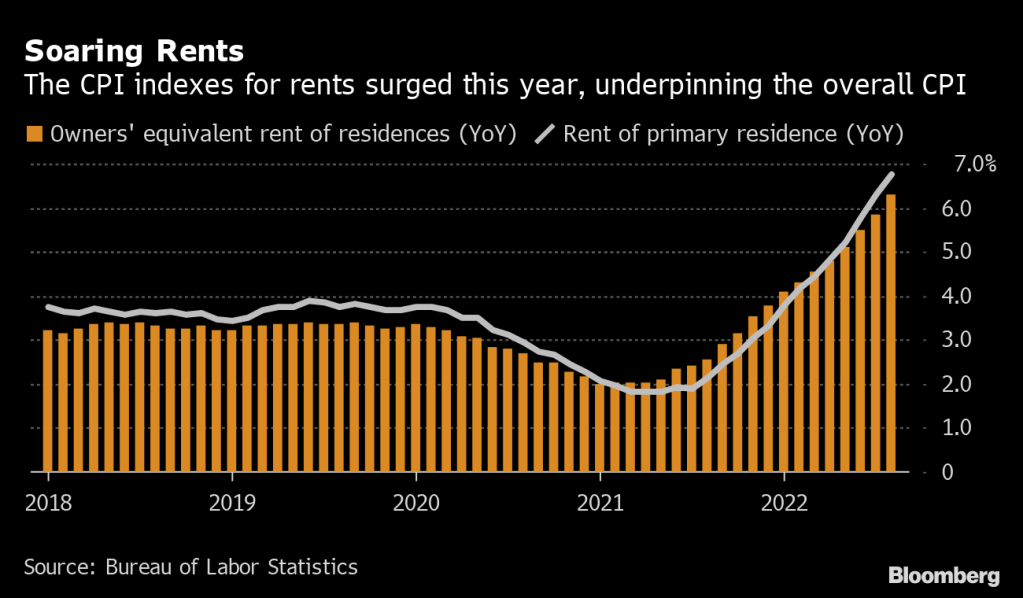
A key US inflation measure due Thursday is set to return to a four-decade high, underscoring broad and elevated price pressures that are pushing the Federal Reserve toward yet another large interest-rate hike next month.
The so-called core consumer price index that excludes food and energy is projected to rise 0.4% in September from the prior month and 6.5% from a year earlier, matching the rate seen in March that was the highest since 1982.
The overall CPI, however, is expected to decelerate to a still-rapid 8.1% annual pace, restrained by a decline in gasoline prices, based on the median estimate.
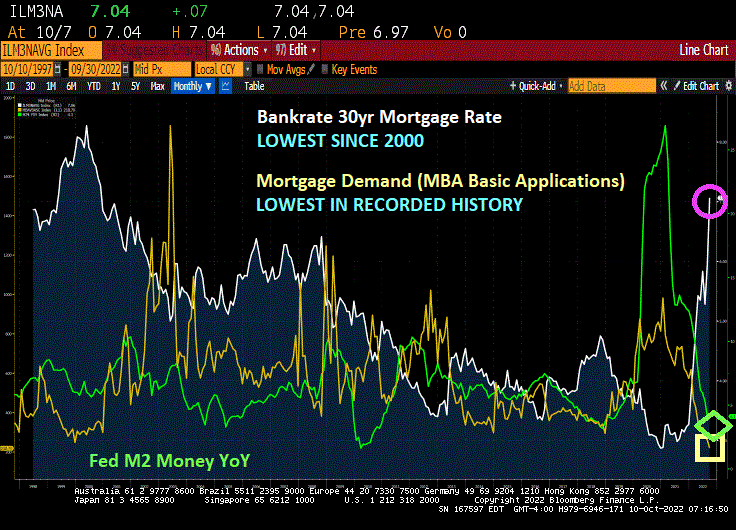
Another casualty of The Fed’s tightening and reduction in M2 Money supply are … the mortgage and housing markets. The US mortgage rate has soared to 7.04% (highest since 2000) and mortgage DEMAND has fallen to the lowest level in recorded history.
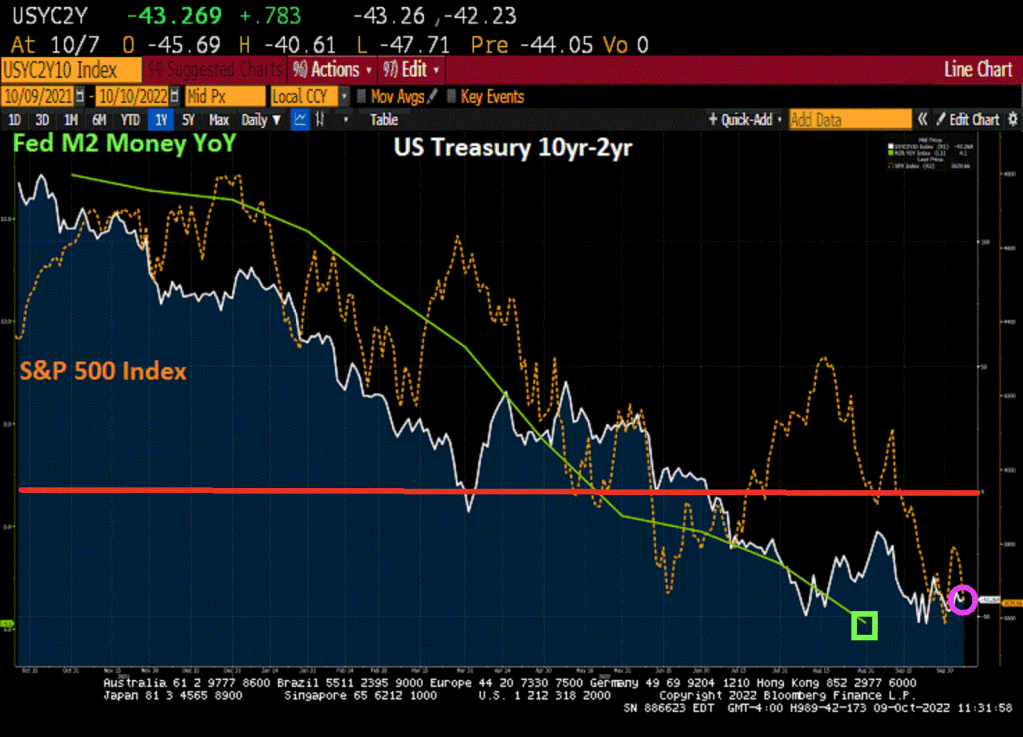
Here is my chart from yesterday showing the inversion of the US Treasury 10yr-2yr curve and decline in the S&P 500 index as The Fed tightens.
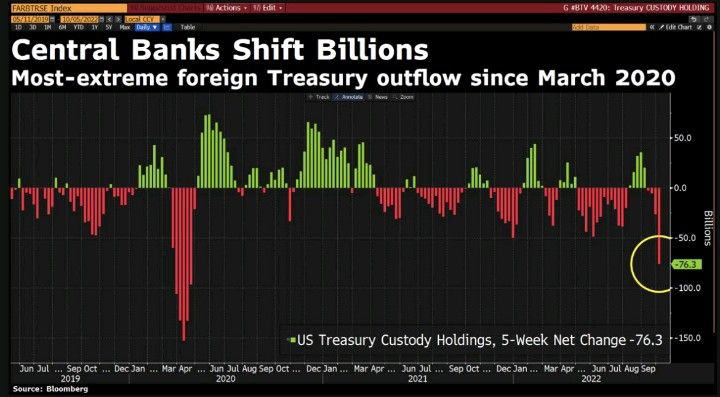
And then we have this chart showing the most-extreme foreign Treasury outflow since March 2020.
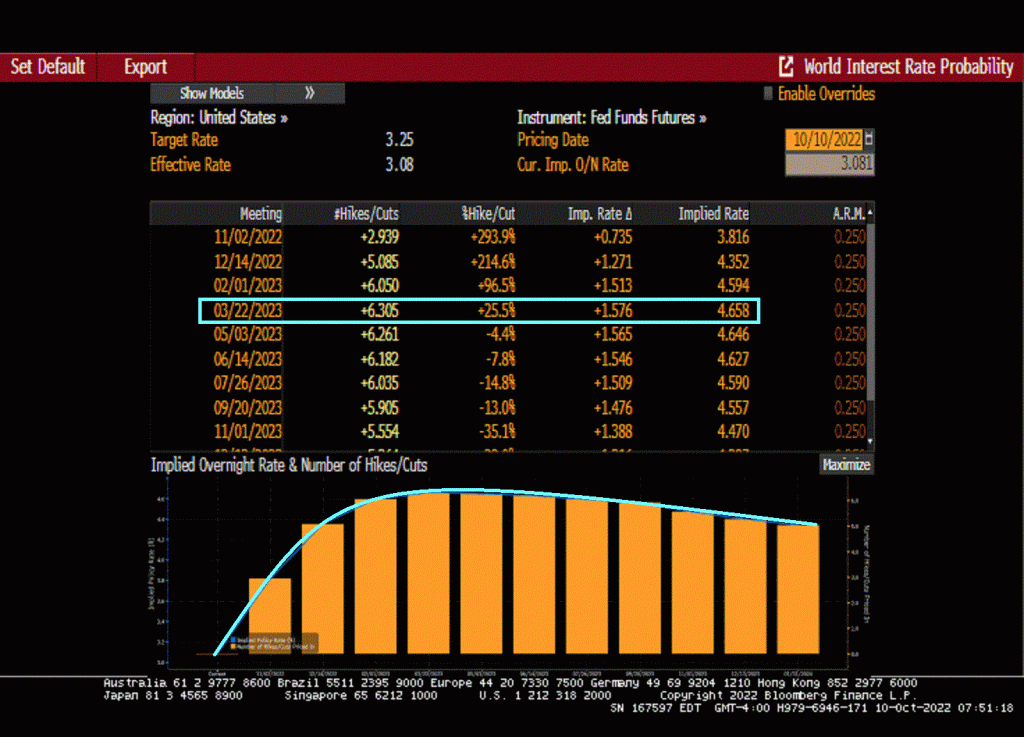
At least The Fed is predicted to start cutting rates again in March 2020.
Yes, Biden and Powell have reenacted Kevin’s famous chili spill. And Ben Bernanke, the creator of QE from late 2008 was just award the Nobel Prize in economics for distorting financial markets.
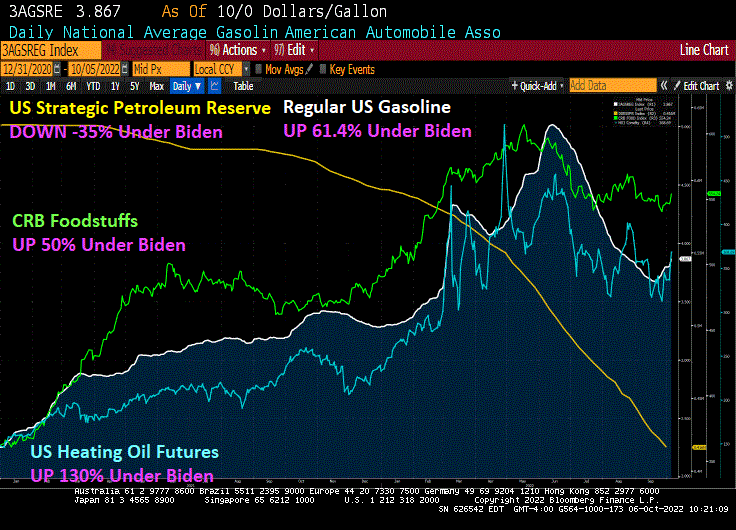
What do we have? Regular gasoline prices are UP 61.4% under Biden, the strategic petroleum reserve is DOWN -35% before Biden’s latest release of another 10 million barrels. Foodstuffs are UP 50% under Clueless Joe, and heating oil futures are UP 130% under dementia Joe.
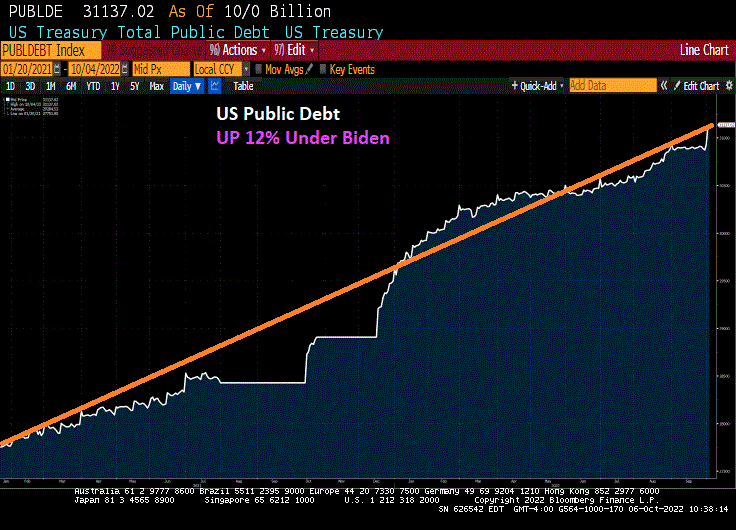
And thanks to free-spending Joe, Nancy and Chuckie, US public debt is at $31.1 TRILLION. That is ANOTHER 12% in national debt under the 4 Horsemen of the Economic Apocalypse.
For an additional 12% in national debt (to be paid by our children and grandchildren), we have crippling inflation.
New CEO Koerner sought to reassure employees in Friday memo
Shares fall to a fresh record low, gauge of credit risk rises
It is like the Lehman Brothers debacle in 2008 all over again.
(Bloomberg) — Credit Suisse Group AG was plunged into fresh market turmoil after Chief Executive Officer Ulrich Koerner’s attempts to reassure employees and investors backfired, adding to uncertainty surrounding the bank.
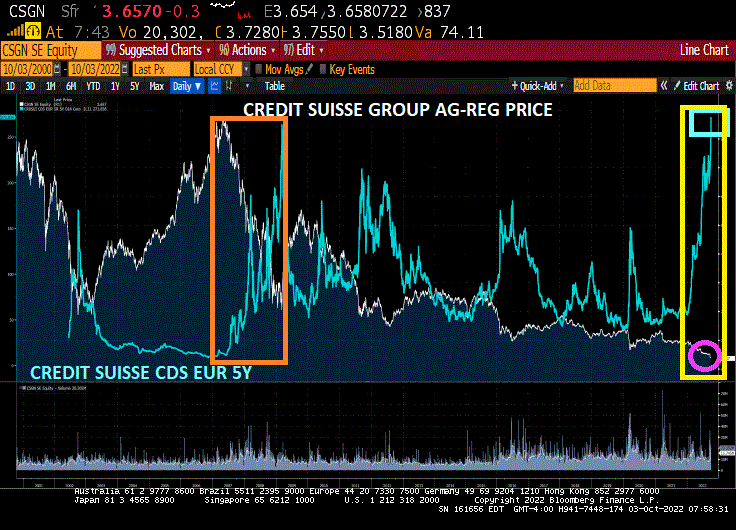
The stock, which had already more than halved this year before Monday’s sell-off, fell as much as 12% in Zurich trading to a record low that values the firm at less than $10 billion. That was accompanied by a spike in the cost to insure the bank’s debt against default, which jumped to its highest ever.
Koerner, for the second time in as many weeks, had sought to calm employees and the markets with a memo late Friday stressing the bank’s liquidity and capital strength. Instead, it focused attention on the dramatic recent moves in the firm’s stock price and credit spreads, and investors rushed for the exit when trading reopened after the weekend.
One notable difference between 2008 and today is that Credit Suisse’s equity was flying high in June 2007 then crashed a the global banking crisis went into full motion. We then saw Credit Suisse’s credit default swaps soar in early 2009. But today Credit Suisse’s equity is a pale imitation of its former self, but its credit default swap is now higher than it was at its peak in early 2009.
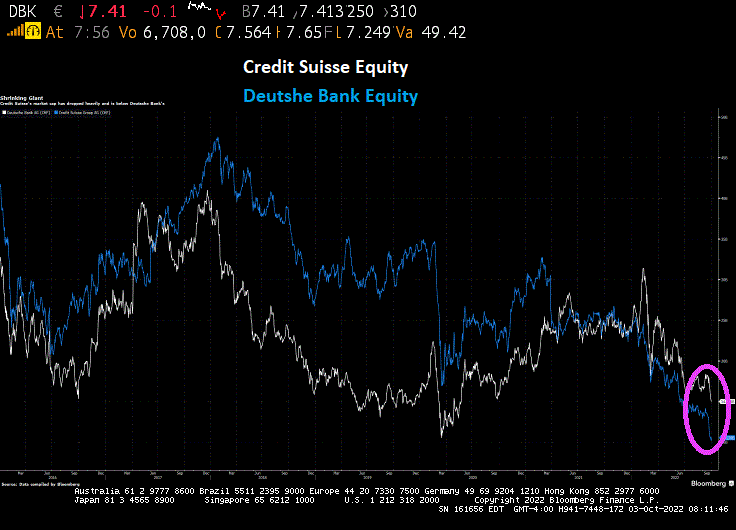
Credit Suisse is now trading lower than its European rival Deutsche Bank (aka, The Teutonic Titanic).
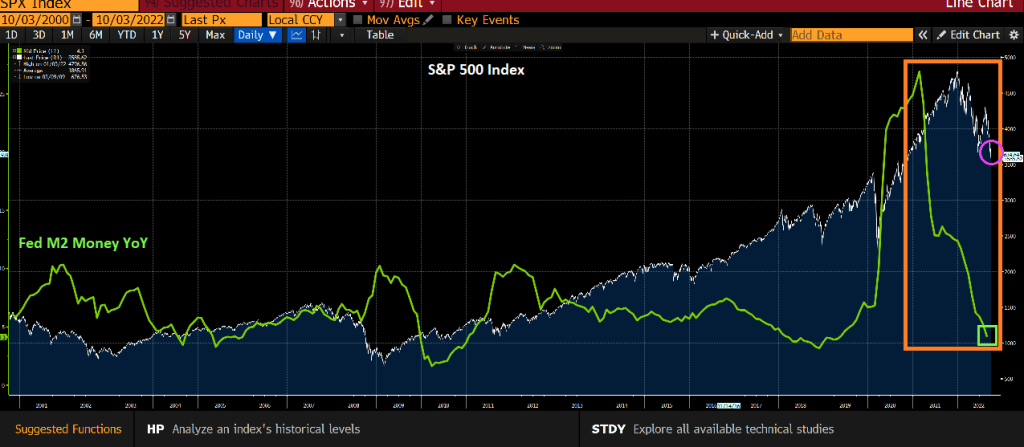
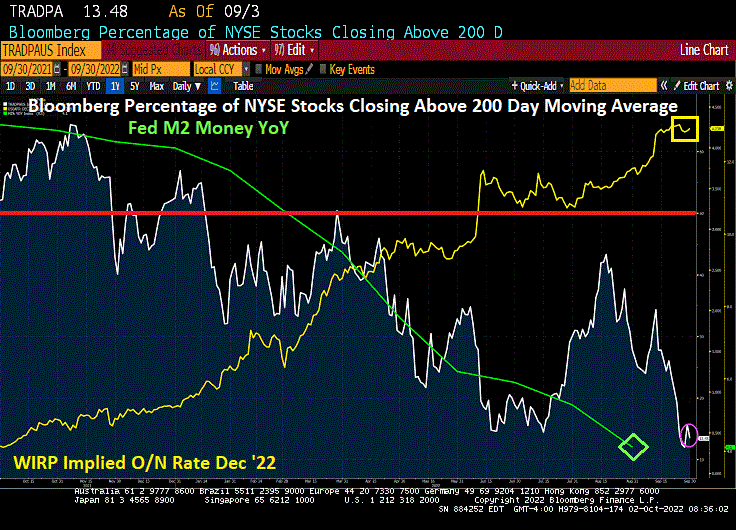
Yes, this brings back sickening memories of the 2008-2009 global financial crisis. Let’s see how The Federal Reserve, ECB and Bank of Switzerland handle this debacle, particularly with M2 Money growth so low.
It appears that we are in another Lehman debacle. Or should I say “Lemur Bros.”
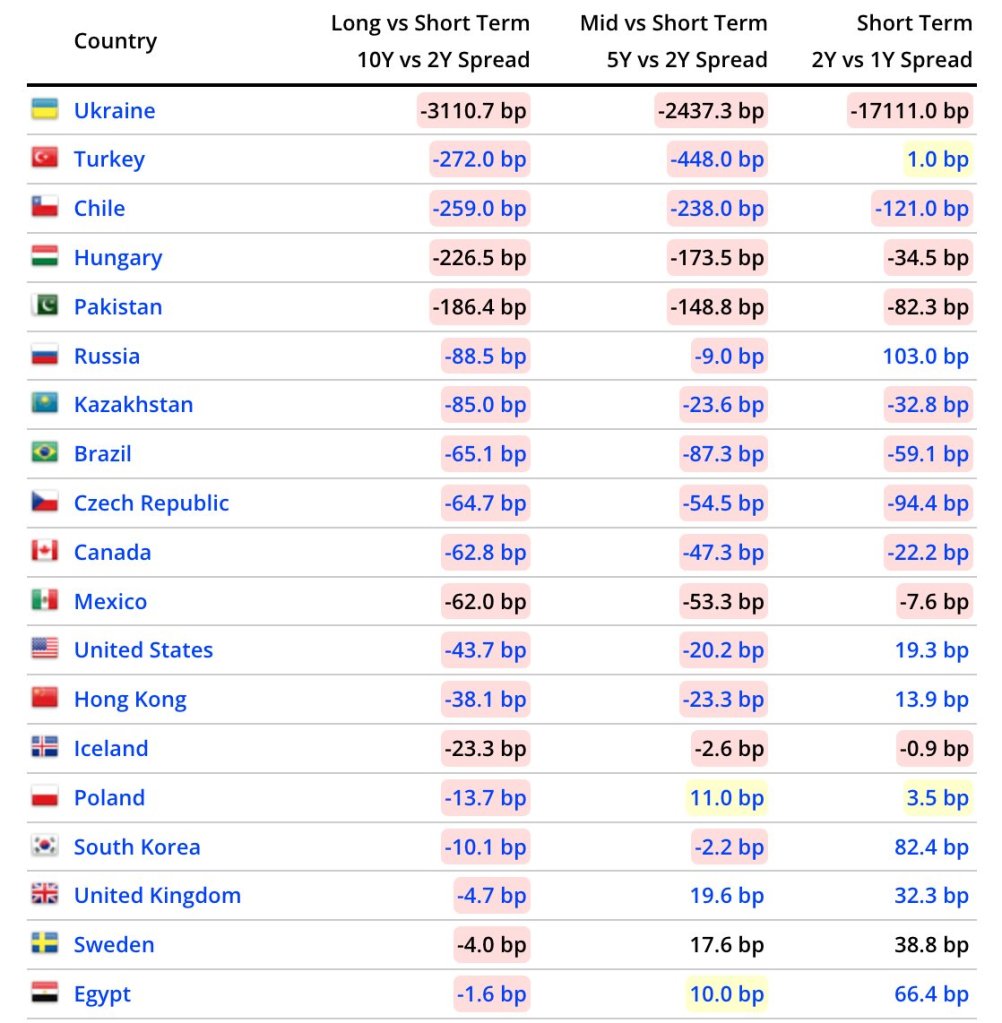
19 nations now have inverted 10yr-2yr yield curves.
And housing inventory for sale growth is soaring out West and in Tennessee?
At least Ohio is seeing a modest increase in housing inventory for sale.
On a parting note (before I watch the Ohio State Buckeyes annihilate the Rutgers Scarlet Knights tomorrow at 3pm EST, reverse repos parked overnight at The Fed just hit an all-time high. Apparently, banks don’t believe Janet Yellen’s inflation is transitory mumbo-jumbo.
$32 TRILLION of global stock value has been wiped out since December 2021.
Today’s core PCE deflator reading of 4.9% YoY shows that the inflation surge is not over. With a core PCE deflator of 4.9%, the Taylor Rule suggests that The Fed Funds Target Rate should be at 9.65%, far below its current level of 3.25%. So, IFF The Fed is following any sort of rule, rates should continue to soar.
And if we use headline inflation of 8.30% YoY, the Taylor Rule suggests hiking the target rate to 14.75%.
Fire! European stock valuations have dropped to lowest since 2012.
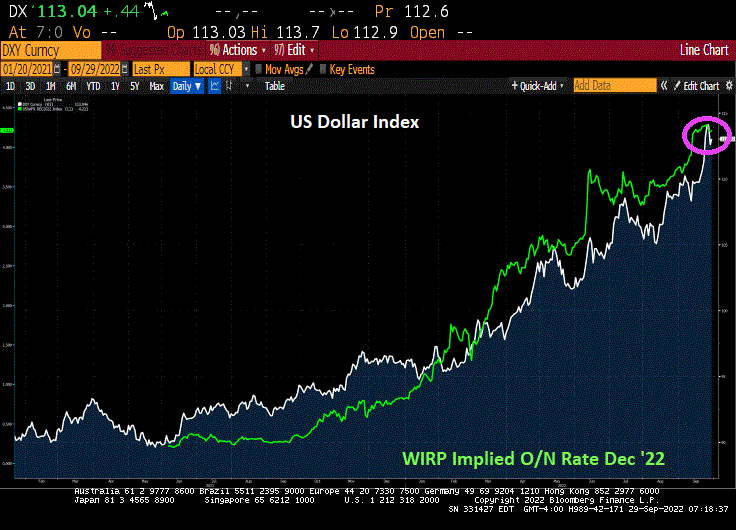
The US Dollar index is soaring (not helping Europe) as The Federal Reserve tightens monetary policy to combat the inflation fire.
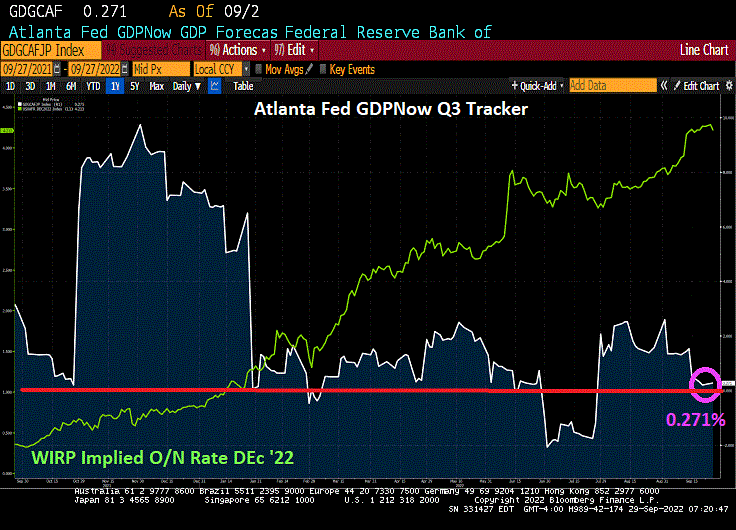
Meanwhile, the Atlanta Fed’s GDPNow real-time forecast for Q3 is at least above zero (barely) at 0.271%.
Fed officials continued to hammer home the central bank’s hawkish outlook, with Atlanta President Raphael Bostic saying he backs raising rates by a further 1.25 percentage points by the end of this year. Meanwhile, the People’s Bank of China said it will accelerate usage of targeted loans.
Bond volatility is increasing.
The US Treasury 10-year yield was down -20 basis points yesterday and is up +10 basis points today. This is the Fed’s Rollercoaster effect.
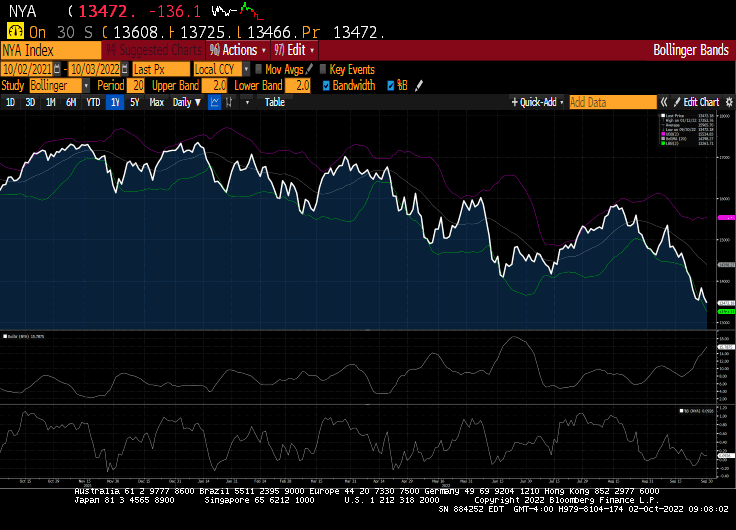
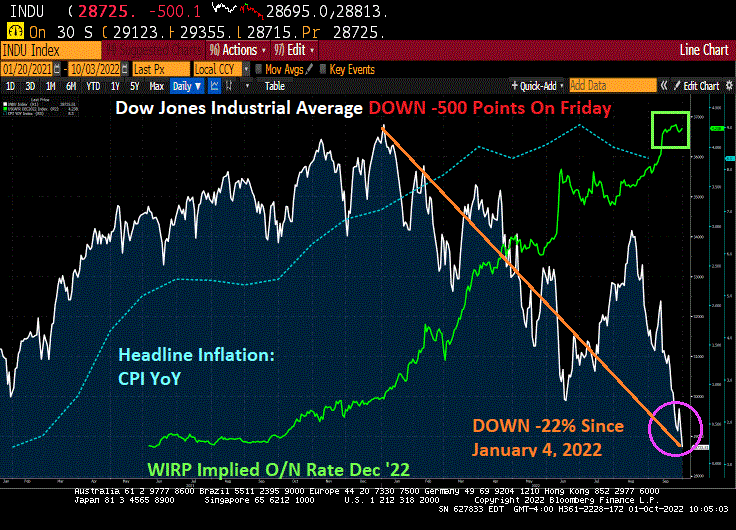
The Dow is down another 400 points today as The Fed’s Sugar Rush is ending. Perhaps The Federal Reserve main building in Washington DC should be renamed “The Sugar Shack.”
In related news, apparently the Biden Administration is going to replace Treasury Secretary Janet Yellen with … anybody else??
Meanwhile I will have a bottle of wine to kill the pain of inflation and Fed tightening.










 Confounded Interest - Anthony B. Sanders

You must be logged in to post a comment.