Household Essentials Cost Far More Under Bidenomics! Gasoline Prices Up 72%, Rent Of Primary Residence Up 16%, Food At Home Up 20% Under Biden! (30Y Mortgage Rate UP 163% Under “Middle Class Joe”)

Middle class Joe my ^%&!

Joe Biden will always be remembered for lying about never raising taxes on households making under $400,000. Inflation is a permanent tax, mostly on those making under $400,000 per year. And household essentials are up substantially under Biden: gasoline prices are up 72%, rent CPI of Primary Residence is up 16%, and food at home CPI is up 20%! That is a HUGE tax on the middle class.

When mainstream economists and politicians cite “improvements” to the inflation problem in the US in recent months, what they are commonly referencing are changes to the Consumer Price Index (CPI).  However, the CPI is not a measure of total inflation, rather, it is a median snapshot of prices at a particular point and time.  True inflation is cumulative – A 10% increase one year and a 5% increase the next year is not a win, it means that you are now paying 15% more on average for everything you buy in the span of only two years.   

When CPI falls this does not mean that prices on goods and services are going down, it only indicates that prices are rising slower than they were the month or the year before.

Another misconception about CPI is that it measures the inflation rate accurately for regular consumers on common purchases.  In reality, the CPI represents mean average price rate increase for a vast basket of goods; over 94,000 items and services with over 200 separate categories.  Most of these items and services you will never use or rarely purchase in the span of a year.  In other words, inflation declines in uncommon goods can dilute the numbers, making it seem like inflation is dropping while prices on daily necessities continue to spike.  

The CPI is weighted according to consumer spending patterns, which is where the calculations can be “adjusted” to a certain extent in an arbitrary manner.  Then there is outright government manipulation through various means.  As we witnessed recently with the Biden Administration’s claims that “Bidenomics” has defeated the inflation threat, what these reports don’t mention is that Biden has been dumping US strategic oil reserves on the market for the past year.  And since energy prices effect the inflation of so many other categories, Biden has artificially manipulated the CPI down using one key resource.  

Now that his ability to dump oil reserves has ended, CPI will rise once again along with energy prices.

The point is, it’s impossible to get a sense of the real damage from inflation without looking at the cumulative inflation in necessities (the goods and services that people are required to purchase on a regular basis to live day to day).  If we throw out the CPI distraction and look at common necessities since 2020, the economic picture is far more bleak.  

Overall food prices have soared by 25%-30% in only three years (again, this means that you are now paying 30% more this year for food than you were paying at the beginning of 2020). Chicken is up from $3 per pound to $4 per pound.  Beef is up from $3.50 to $6 per pound.  Corn is up from $3.50 per pound to $4.70 per pound.  Wheat is up from $5 per pound to $7 per pound.  In 2019 the average American household was spending $8100 on food annually; with a 30% increase, in 2023 Americans will be spending at least $10,500 per household.          

By the end of 2019, the average rental price of a single family home was around $1450 per month.  This year the price is around $2000 per month.  At the beginning of 2020, the median cost of a home was $320,000; by 2023 the price skyrocketed to an average of $416,000.  

For gasoline, the price in early 2020 was around $2.50 per gallon.  The price has fluctuated dramatically due to Biden’s manipulation of the market using strategic reserves, but still remains high today at $3.80 per gallon.  

The cost of electricity has risen swiftly, holding steady around .13 cents per kilowatt hour for a decade, then spiking to at least .17 cents per kilowatt hour by 2023.

Remember, most of these costs are static and are difficult to reduce through household spending cuts.  These are not items that are easily removed from a monthly budget and the expenditures add up to considerable pressure on consumer accounts.  This is probably why around 74% of the public in polls say that the economy is getting worse, not better.  It’s because government statistics are not highlighting the true inflationary crisis.

When we look at the cumulative climb of prices in necessities since before the inflation crisis officially began, the truth is that Americans now have to increase their wages by at least 25%-30% on average to maintain the same standard of living they had three years ago.  This is a disaster not seen since the stagflationary event of the 1970s and early 1980s.  If you have a strange feeling like your bank account is being rapidly drained in recent months, that’s because it is.    

And the 30-year mortgage rate is up 163% under Middle Class Joe.

Thrill Is Gone … From Bidenomics! US Durable Goods Orders Fall -15.23% From June To July While Fed M2 Money Grew 12.7% (Turning Back On The Money Machine!)

The Thrill Is Gone … from Bidenomics.

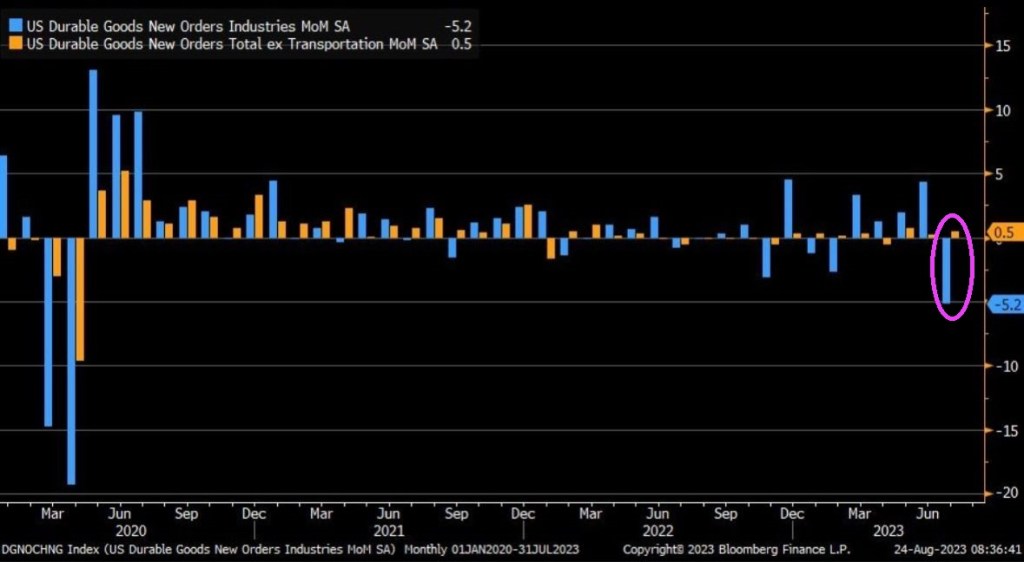
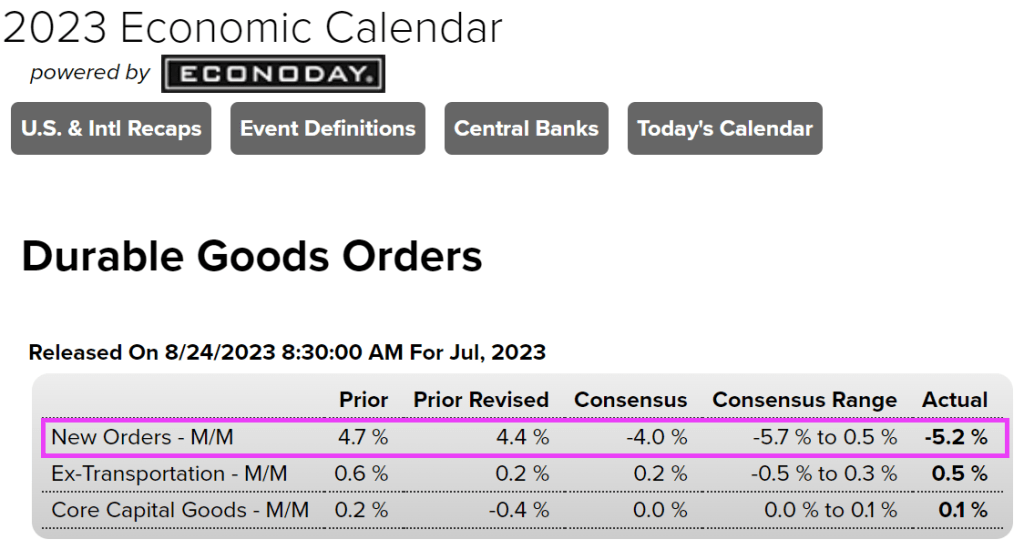
July durable goods [blue] new orders plummet, recording the worst month since C19 in April 2020. Durable goods fell on a MoM basis by -5.2%, versus -4% consensus estimate. Durable goods ex-transportation [orange] still rose on a MoM basis by +0.5%, perhaps highlighting the weakness in durable goods orders.
Ex-transportation, durable goods order rose slighlty in July by 0.5%.

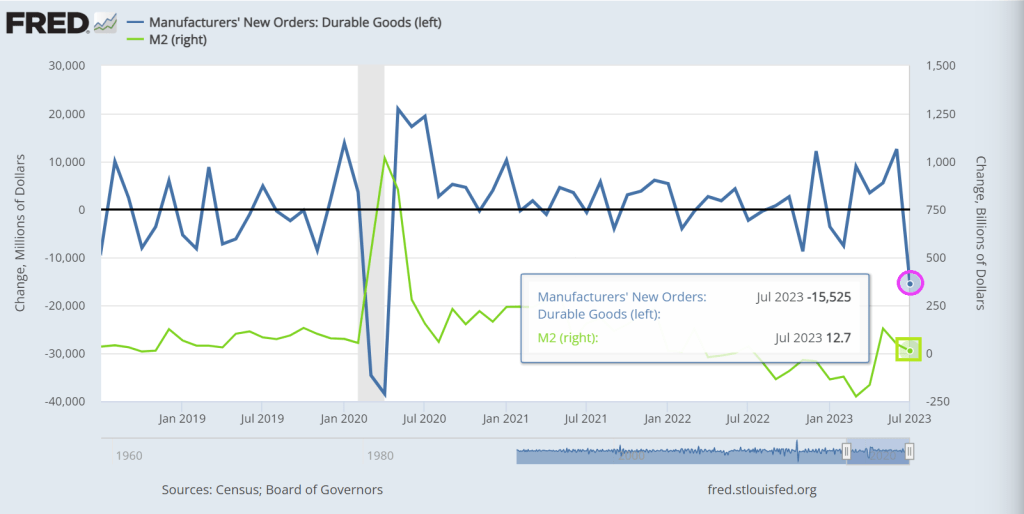
But according to The Fed of St Louis, durable goods new orders were down -15.525% from June to July (MoM) while M2 Money printing growth rose 12.7% MoM.

The KC Fed’s symosium in Jackson Hole WYO is underway and The Fed’s money machine is firingg up again. Here is the evil spirit of Statism speaking at Jackson Hole.

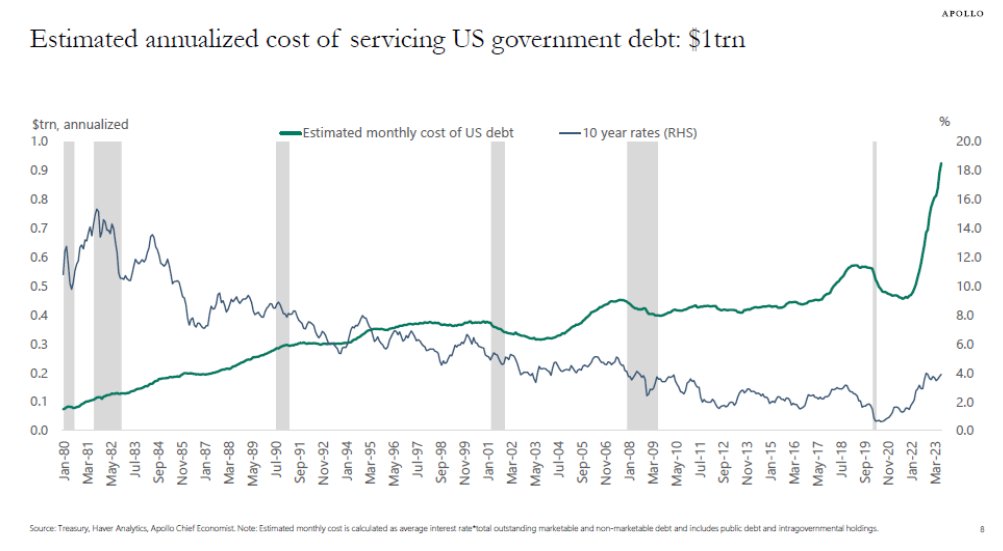
Bidenomics Crazy Train! US Corporate Bankruptcies Are On The Rise As US Federal Annualized Debt Payments Near $1 TRILLION

All aboard the Bidenomics Crazy Train!

Let’s see. We have inflation that is eroding wage growth so that REAL wage growth is negative. Meanwhile, the Biden Administration and Congress are spending like they can print infinite amounts of cash with no consequences. The result? The Federal government is paying nearly $1 trillion in interest on an annualized basis.

On the corporate side, we are seeing a surge in bankruptcies.

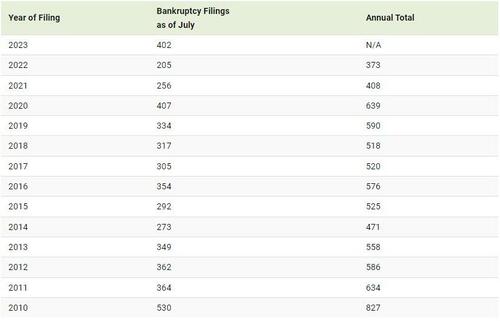
As Visual Capitalist’s Dorothy Neufeld and Sabrina Fortin show in the graphic below, based on data from S&P Globalcorporate bankruptcies in 2023 are surging…

U.S. Corporate Bankruptcies Grow

So far in 2023, over 400 corporations have gone under. Corporate bankruptcies are rising at the fastest pace since 2010 (barring the pandemic), and are double the level seen this time last year.

Below, we show trends in corporate casualties with data as of July 31, 2023:

Represents public or private companies with public debt where either assets or liabilities are greater than or equal to $2 million, or private companies where assets or liabilities are greater than or equal to $10 million at time of bankruptcy.

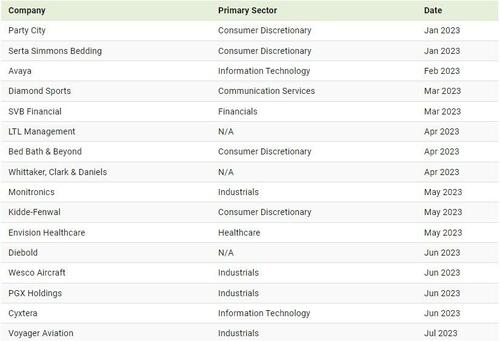
Firms in the consumer discretionary and industrial sectors have seen the most bankruptcies, based on available data. Historically, both sectors carry significant debt on their balance sheets compared to other sectors, putting them at higher risk in a rising rate environment.

Overall, U.S. corporate interest costs have increased 22% annually compared to the first quarter of 2021. These additional costs, combined with higher wages, energy, and materials, among others, mean that companies may be under greater pressure to cut costs, restructure their debt, or in the worst case, fold.

Billion-Dollar Bankruptcies

This year, 16 companies with over $1 billion in liabilities have filed for bankruptcy. Among the most notable are retail chain Bed Bath & Beyond and the parent company of Silicon Valley Bank.

Mattress giant Serta Simmons filed for bankruptcy early this year. It once made up nearly 20% of bedding sales in America. With a vast share of debt coming due this year, the company was unable to make payments due to higher borrowing costs.

What Comes Next?

In many ways, U.S. corporations have been resilient despite the sharp rise in borrowing costs and economic uncertainty.

This can be explained in part by stronger than anticipated profits seen in 2022. While some companies have cut costs, others have hiked prices in an inflationary environment, creating buffers for rising interest payments. Still, S&P 500 earnings have begun to slow this year, falling over 5% in the second quarter compared to last year.

Secondly, the structure of corporate debt is much different than before the global financial crash. Many companies locked in fixed-rate debt over longer periods after the crisis. Today, roughly 72% of rated U.S. corporate debt has fixed rates.

At the same time, banks are getting more creative with their lending structures when companies get into trouble. There has been a record “extend and amend” activity for certain types of corporate bonds. This debt restructuring is enabling companies to keep operating.

The bad news is that corporate debt swelled during the pandemic, and eventually this debt will come due likely at much higher costs and with more severe consequences.

The face of Bidenomics: the top 1% are gleefull (like Billions Biden), the bottom 99% are mournful.

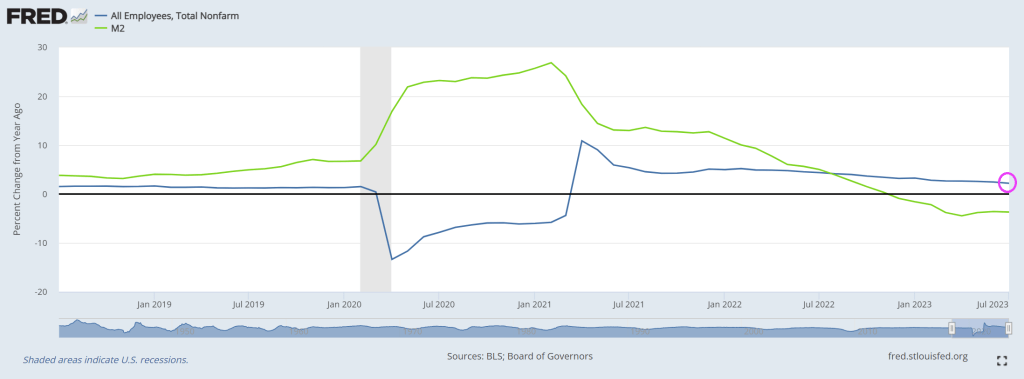
Bidenomics! US Payrolls Were Likely 306,000 Lower Than Previously Estimated (July Jobs Growth Slowed To 2.2% YoY As M2 Money Growth Slowed To -3.7% YoY)

  • Preliminary benchmark revision smaller than some had projected
  • Biggest payrolls adjustment in transportation and warehousing

Are you surprised that the Biden Administration has been lying about job creation?? Not really since Biden compulsively lies about everything. Including his corruption.

US job growth was probably less robust in the year through March than previously reported, according to government data released Wednesday.

The number of workers on payrolls will likely be revised down by 306,000 for March of this year, according to the Bureau of Labor Statistics’ preliminary benchmark revision.

Even without the revision, job growth has slowed to 2.2% YoY in July as M2 Money growth slowed to -3.7% YoY.

Let see what our Overlords say at the Jackson Hole Fed symposium.

Burning Down The Housing Market! Mortgage Demand Decreased in Weekly Survey Purchase Applications “Lowest Level Since April 1995”

The Talking Heads said it best. Bidenomics is burning down the housing market. Bidenomincs (or trying to recover from Yellenomics) is responisble for interest rates rising to flight inflation and the collapse of mortgage lending. And she was … Janet Yellen.

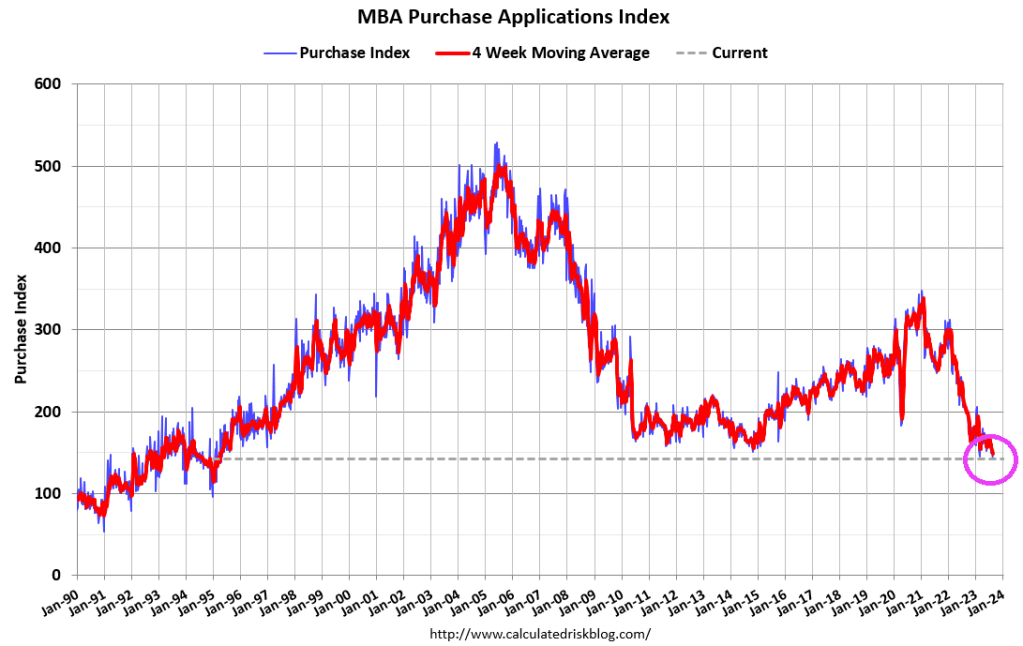
Mortgage demand (applications) decreased 4.2 percent from one week earlier, according to data from the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey for the week ending August 18, 2023.

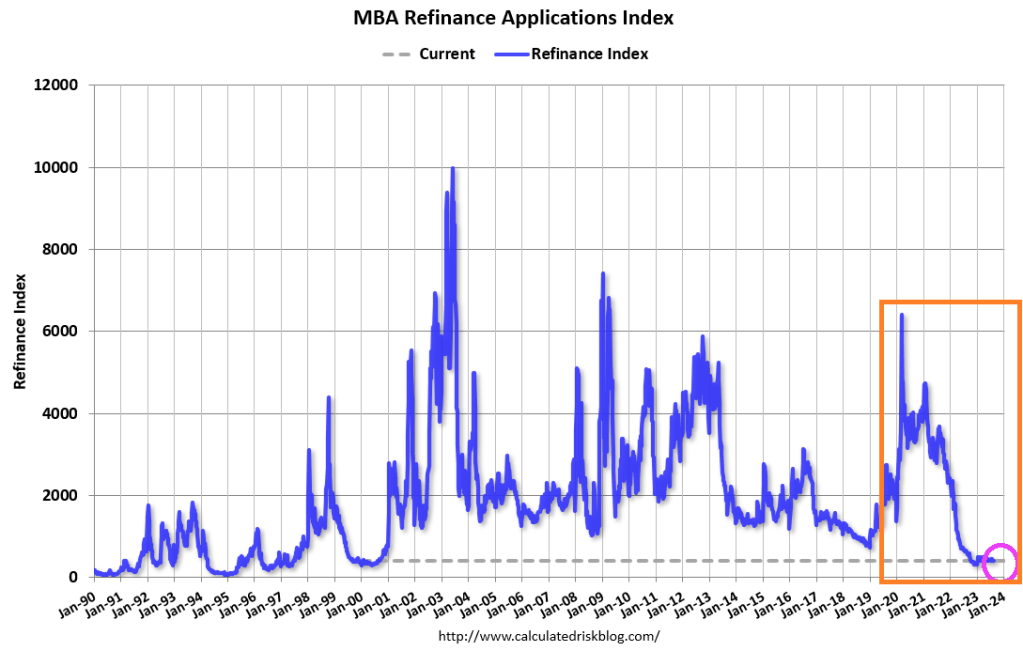
The Market Composite Index, a measure of mortgage loan application volume, decreased 4.2 percent on a seasonally adjusted basis from one week earlier. On an unadjusted basis, the Index decreased 6 percent compared with the previous week. The Refinance Index decreased 3 percent from the previous week and was 35 percent lower than the same week one year ago. The seasonally adjusted Purchase Index decreased 5 percent from one week earlier. The unadjusted Purchase Index decreased 7 percent compared with the previous week and was 30 percent lower than the same week one year ago.

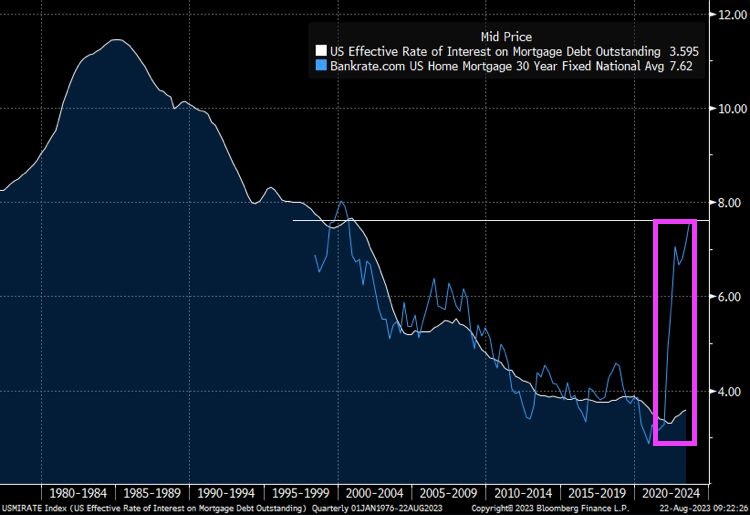
The spread betweenn Bankrate’s 30 year rate at 7.62% and the effective rate on mortgage debt outstanding at 3.595% has exploded as mortgage rates jump.

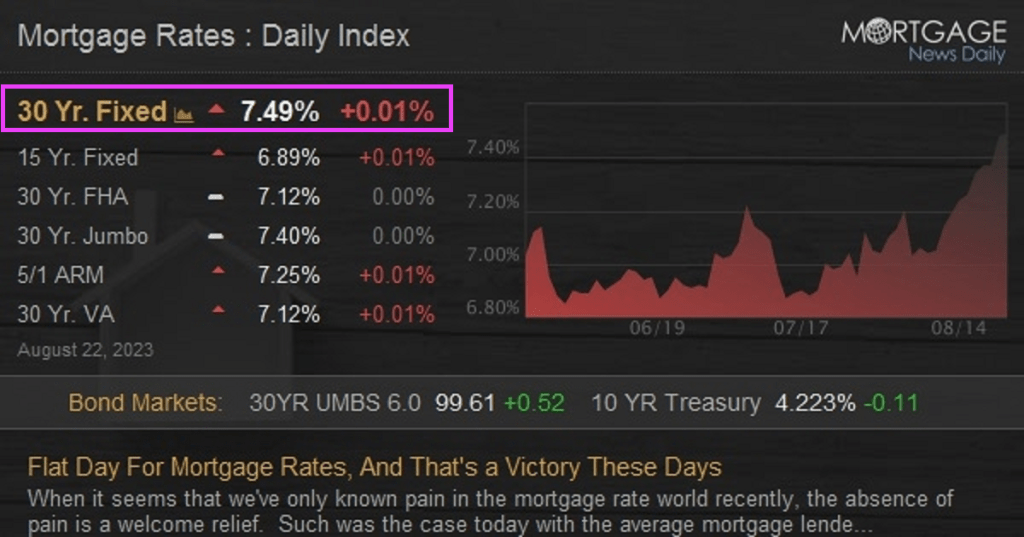
Today’s mortgage rates are up to 7.49%. OMG!

Bidenomics (code for making large donors wealthier and the middle class getting the boot) and catch-up for Yellenomics (rates too low for too long), and Powell are helping to burn down the housing market.

Bidenomics Mortgage Market! Mortgage Rates Now 7.2%, UP 159% Under Maui Joe! (10Y-2Y Yield Curve Collapsed From +100 BPS To -63 BPS)

Maui Joe Biden received a lot of help from his friends at The Federal Reserve!

Thanks to the crippling effects of Bidenomics (Fed easing then tightening to combat inflation caused by insane green spending and a war in Ukraine), US mortgage rates (conforming 30-year) has increased 159%.

On the yield curve side, the US Treasury curve 10Y-2Y CMT fell from 99 basis points the day after Maui Joe was sworn-in as El Presidente to the inverted curve we see today (-63 basis points).

Dynamic Maui Joe looking less than happy trying to visit Maui while he could be partying with mega-donor Tom Steyer (a big green energy con artist).

At least Biden didn’t wear his aviator sunglasses or down an ice cream in a show of “empathy.” But, of course, he did find time to assault a child! Watch the hands Maui Joe!!!!

Not Always Sunny! Philly Fed Non-Manufacturing Survey SCREAMS Stagflation (Powell And Fed Acholytes Descend On Jackson Hole Wyoming)

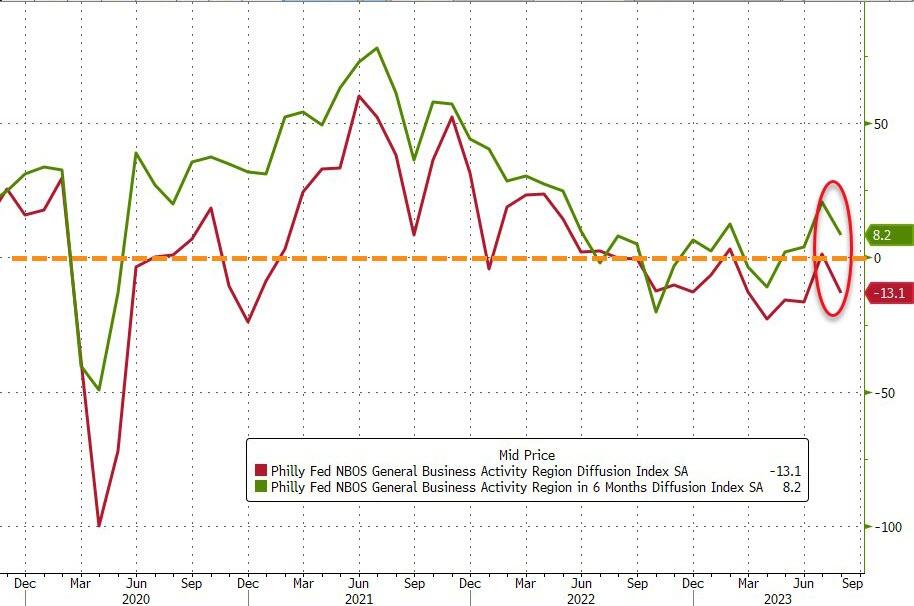
It’s NOT always sunny in Philadelphia. Particularly when the Philly Fed non-manufacturing survey screams stagflation (a nauseating combination of economic slowdown and inflation).

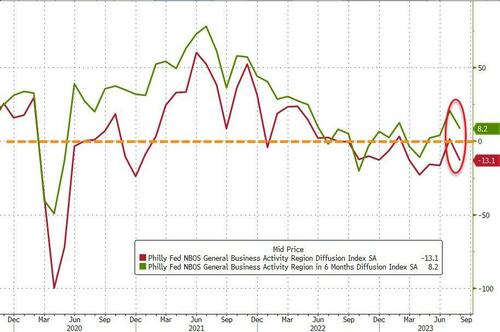
After a positive surprise in July, Philly Fed’s non-manufacturing survey slumped back into contraction in August (from +1.4 to -13.1). Additionally, while respondents continue to expect a growth over the next 6 months, that optimism is fading rapidly

Source: Bloomberg

On a non-seasonally-adjusted basis, the Philly Fed Services survey plunged to -20.0 – practically its lowest level since the COVID lockdowns…

Source: Bloomberg

Under the hood it’s even uglier with stagflationary impulses rearing their ugly heads.

Price indicator readings suggest continued increases in prices for inputs and the firms’ own goods and services.

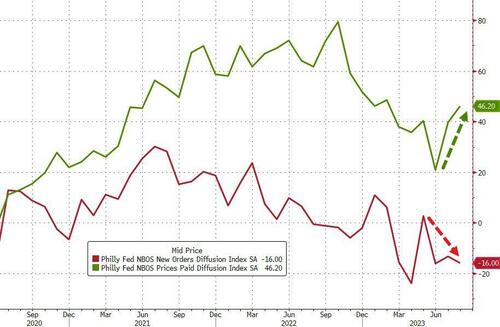
The prices paid index increased 7 points to 46.2 this month. More than 50 percent of the firms reported increases in input prices. Regarding prices for the firms’ own goods and services, the prices received index rose from 7.8 to 14.6.

At the same time the indexes for sales/revenues and new orders both recorded negative readings this month

Source: Bloomberg

Is the ‘Services’ side of the economy finally catching down to the reality of the ‘Manufacturing’ side as savings run dry?

Now that The Fed and Fed Chair Powell are meeting at Jackson Hole WYO for the annual symposium, here is a video of Powell (Green Man) dancing with symposium attendees.

Preview Of Jackson Hole Fed Conference! Will The Fed Continue To Strangle The Economy In Their Zeal To Cool Inflation To 2%? (One Word, YES!)

What is the difference between a porcupine and the KC Fed Jackson Hole conference? At the annual Jackson Hole Federal Reserve retreat, the pricks are on the inside! (Source: Clive Owen from “Shoot ‘Em Up” about drivers of BMW cars).

Yes, the elites of The Federal Reserve System will gather at Grand Teton National Park in Wyoming to discuss “Structural Shifts in the Global Economy,” and will be held on Aug. 24-26.

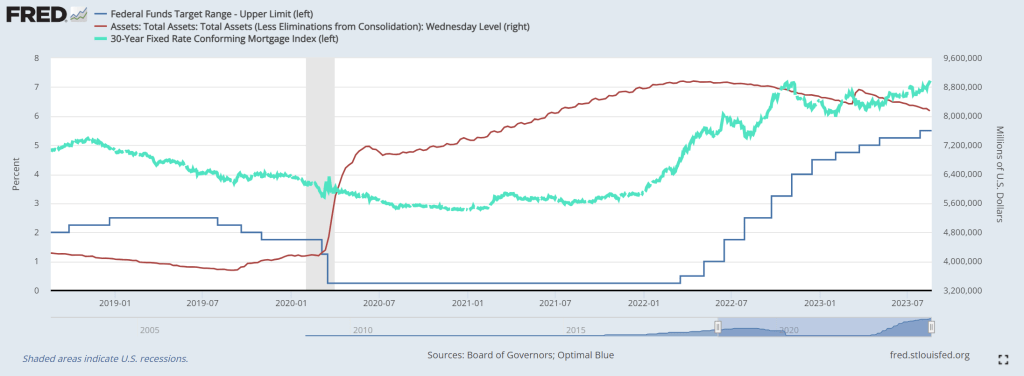
Here is where we sit on Sunday. The 30-year conforming mortgage rate (blue-green line) is over 7% and up 154% under Biden. The Fed’s target rate is now 5.50% (dark blue line) and The Fed still has over $8 TRILLION on its balance sheet. So they haven’t really done all they can do to fight inflation.

Here is a Message From Michael (Snyder). No, not Dionne Warwick’s Message TO Michael.

Do you remember what happened in 2008?  Many people believe that another historic financial disaster is coming and that it will absolutely devastate the U.S. economy.  Earlier this week, I wrote about an investor named Michael Burry that has actually bet 1.6 billion dollars that the stock market is going to crash.  He made all the right moves in 2008, and he fully intends to be proven right once again in 2023.  Of course current conditions definitely resemble 2008 in so many ways.  The residential housing market is so dead right now, and commercial real estate prices are plummeting at a very frightening pace.  Unfortunately, officials at the Federal Reserve are making it quite clear that they are not done strangling the economy.

This week, mortgage rates jumped above the 7 percent mark to the highest level that we have seen in more than 20 years

Mortgage rates surpassed 7% this week, hitting the highest level in more than two decades.

The average rate on the popular 30-year fixed mortgage increased to 7.09% this week, up from 6.96% the week prior, according to Freddie Mac’s release on Thursday. That’s the highest point since the first week of April 2002 and marks just the third time rates have exceeded 7% since then. The last times were in October and November of last year, when the rate reached 7.08%.

Needless to say, high mortgage rates have been crippling the housing market in recent months.

At the midpoint of this year, existing home sales were down a whopping 18.9 percent from the same time in 2022…

Total existing-home sales1 – completed transactions that include single-family homes, townhomes, condominiums and co-ops – receded 3.3% from May to a seasonally adjusted annual rate of 4.16 million in June. Year-over-year, sales fell 18.9% (down from 5.13 million in June 2022).

There are certainly lots of people out there that would like to buy homes, but thanks to how high mortgage rates have become they simply cannot afford to do so.

Housing has become extremely unaffordable in this country.  According to Redfin, the percentage of teachers that can afford to buy a home close to the school where they work has fallen to just 12 percent

The number of teachers who can afford a reasonably priced home in their school district nationwide has collapsed to just 12%, down from 17% last summer and 30% in 2019, amid the worst housing affordability crisis in a generation, according to data from Redfin.

Redfin’s analysis of median teacher salaries for 2022 across 50 major cities for over 70,000 PreK-12 public and private schools revealed no teacher in San Jose and San Diego could afford homes within “commuting distances” to their respective school, which means home and work are 20 minutes during typical rush hour conditions.

So much damage has already been done.

But apparently officials at the Federal Reserve believe that even more carnage is necessary, because they are indicating that more rate hikes are on the table

Most Federal Reserve officials signaled during their July policy-setting meeting that high inflation still poses an ongoing threat that could necessitate additional interest rate hikes this year.

Minutes from the U.S. central bank’s July 25-26 meeting released Wednesday showed that central bank officials observed that inflation remains well above the Fed’s 2% target — and that policymakers need to see “further signs that aggregate demand and aggregate supply were moving into better balance to be confident that inflation pressures were abating.”

No.

Don’t do it.

Even if rates stay at current levels, we are headed for extreme pain.

Raising rates even higher would just be suicidal.

But it looks like they are going to do it anyway, and that could push mortgage rates up to the 8 percent level

Economists have predicted mortgage rates could go above 8 percent if the economy continues to show signs of strength and the US Federal Reserve decides to raise interest rates again.

Mortgage Rates have not hit such levels since 2000, according to data compiled by Freddie Mac.

Do officials at the Fed actually believe that our system can handle such high rates?

Unless the Fed changes course, the housing market is going to absolutely implode.

And of course the commercial real estate market is already imploding.

The chaos that is already transpiring is putting an enormous amount of strain on our financial institutions, and Fitch is warning that we could soon see sweeping rating downgrades in the banking industry…

A Fitch Ratings analyst warned that the U.S. banking industry has inched closer to another source of turbulence — the risk of sweeping rating downgrades on dozens of U.S. banks that could even include the likes of JPMorgan Chase
.
The ratings agency cut its assessment of the industry’s health in June, a move that analyst Chris Wolfe said went largely unnoticed because it didn’t trigger downgrades on banks.

In many ways, I feel like I am watching a repeat of 2008.

Officials at the Fed can clearly see everything that is happening, but they just keep insisting on making things even worse.

So I hope that you have been preparing for turbulent times, because things are going to get crazy.

Sadly, the truth is that most Americans are not prepared for tougher times.  In fact, one recent survey discovered that 72 percent of Americans are not financially secure…

For many Americans, payday can’t come soon enough. As of June, 61% of adults are living paycheck to paycheck, according to a LendingClub report. In other words, they rely on those regular paychecks to meet essential living expenses, with little to no money left over.

Almost three-quarters, 72%, of Americans say they aren’t financially secure given their current financial standing, and more than a quarter said they will likely never be financially secure, according to a survey by Bankrate.

Many of those people will lose their jobs during this new economic crisis, and because they don’t have any sort of a financial cushion to fall back on many of them will also end up losing their homes.

Delinquency rates are already starting to move higher, and that should deeply alarm all of us.

But what we have experienced so far is just the tip of the iceberg.

So brace yourselves for what is ahead, because this ride is only going to get bumpier from here.

Here is a photo of The DC Economic Strangler, Fed Chair Jerome Powell, riding a wild jackalope in Jackson Home Wyoming.

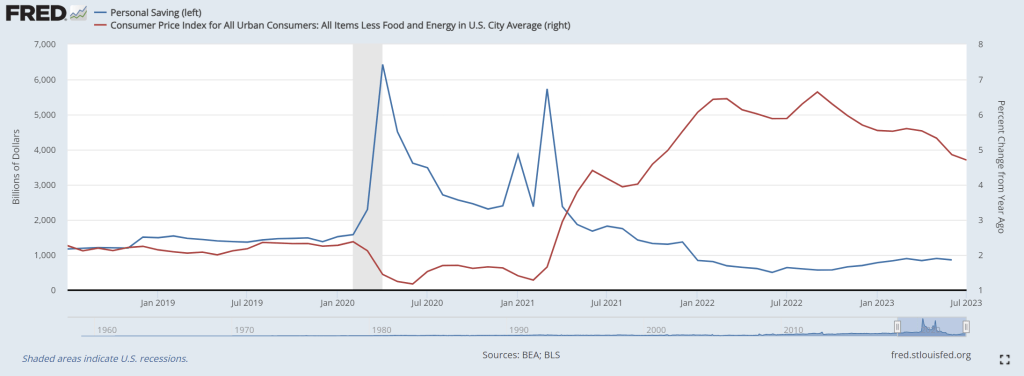
Lowriding! US Personal Savings Lower Than Pre-Covid As Core Inflation Still Hurts At 4.70% YoY (Large Bank Loan Volumes Shrank Last Week As Deposit Outflows Re-Accelerated)

US personal savings are being exhausted as The Fed raises rates to fight inflation. I call this phenomenon “low riding” where consumers are being punished by The Federal Reserve and Biden Administration.

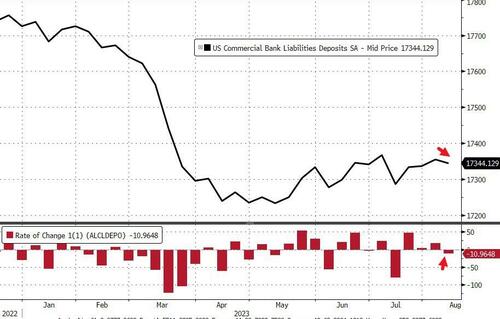
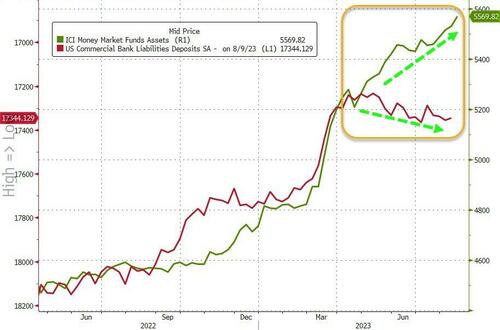
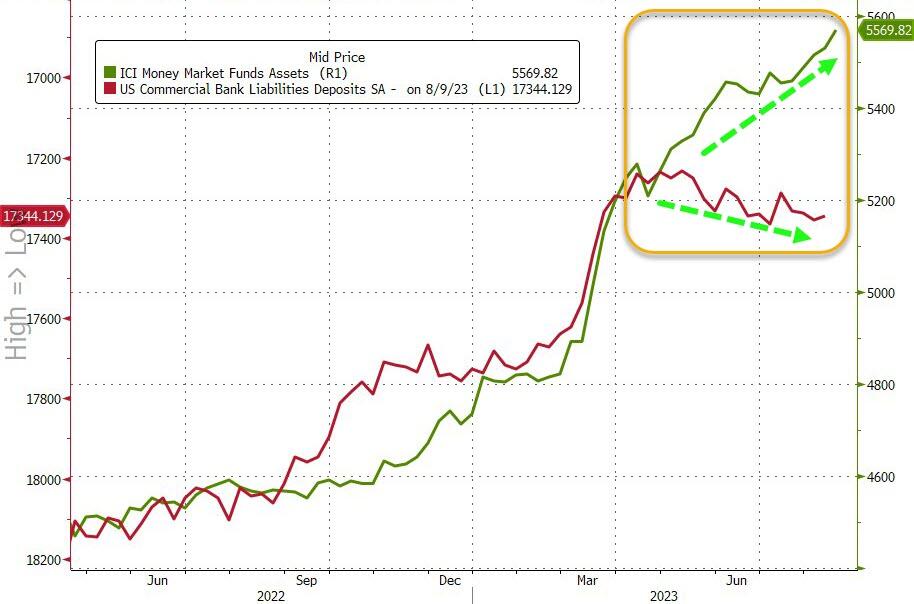
Meanwhile, large bank loan volumes are shrinking. With money-market fund assets hitting new highs, and banks’ usage of The Fed’s emergency funds facility at record highs, we wonder how much longer The Fed can keep the dream of rising deposits alive (after last week’s massive NSA inflows).

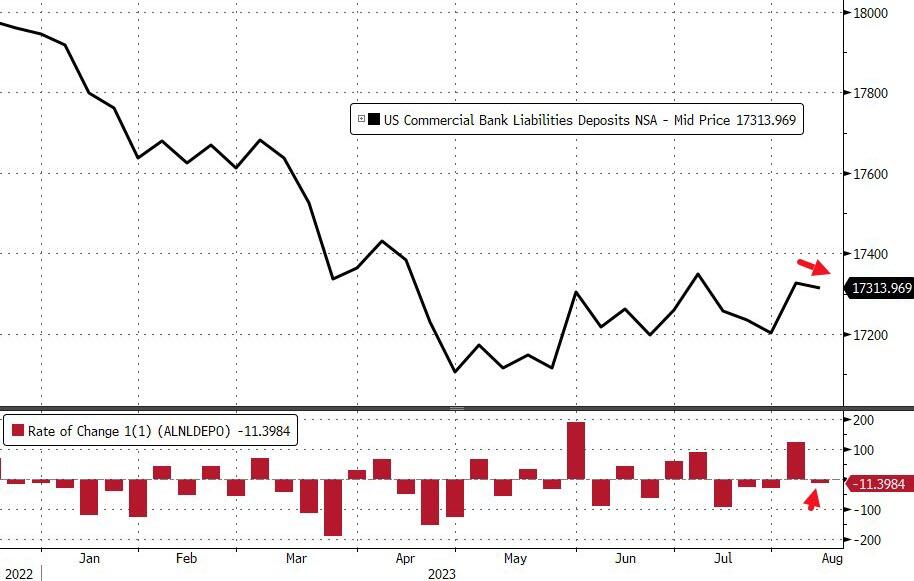
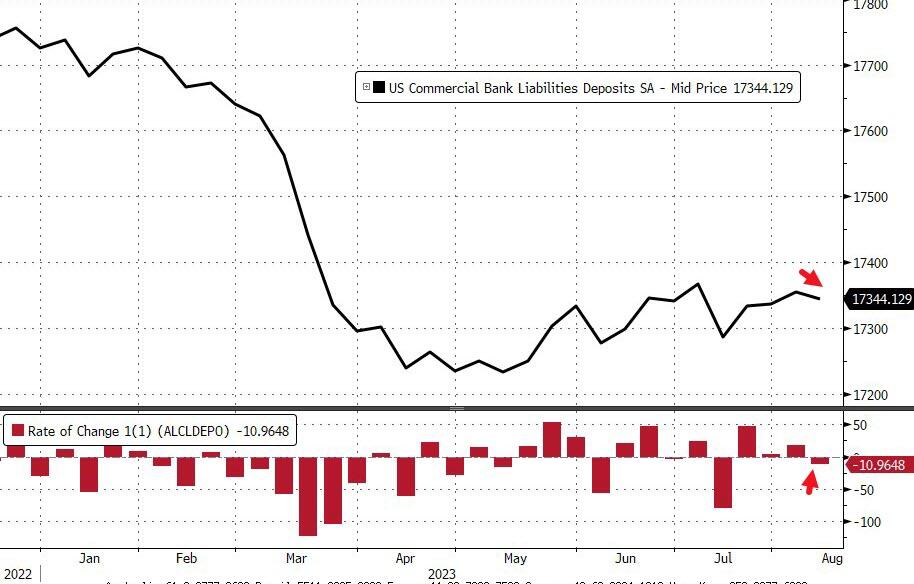
On a seasonally-adjusted basis, The Fed says that total deposits dropped $11BN last week (the first decline in 4 weeks). We also note that the prior week’s inflow was revised higher…

Source: Bloomberg

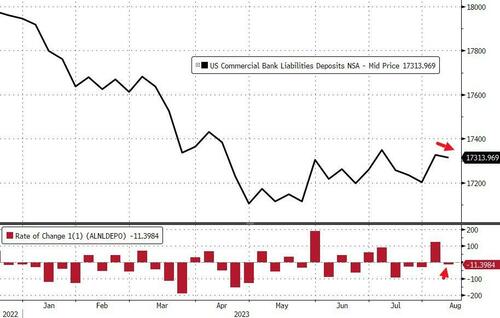
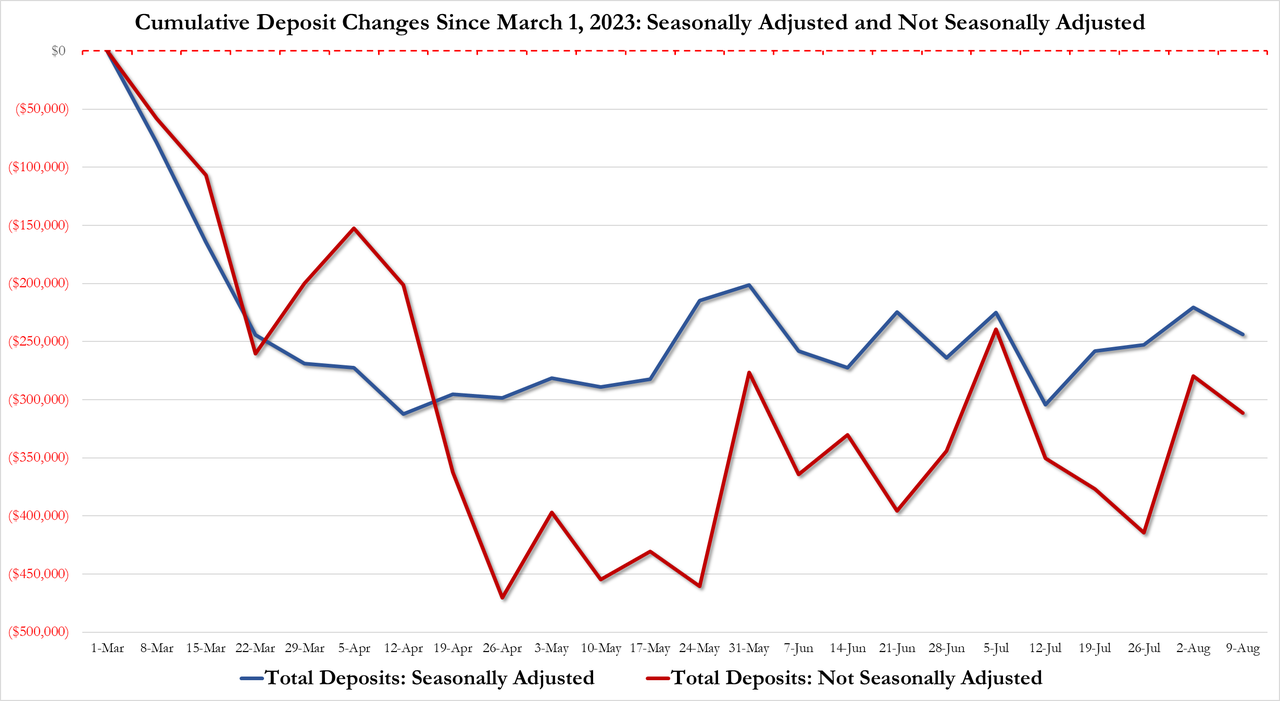
After last week’s enormous $121BN NSA deposits inflow, last week saw an $11BN outflow (on a non-seasonally-adjusted basis)…

Source: Bloomberg

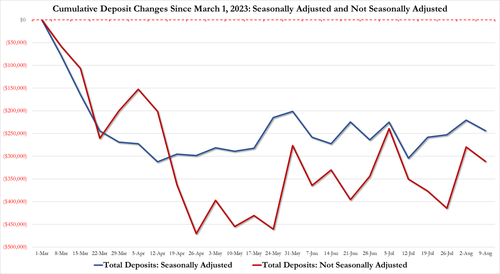
The gap between SA deposits and NSA deposits remains more manageable (until the next time The Fed decides to fiddle)…

The divergence between money-market fund assets and bank deposits remains extreme…

Source: Bloomberg

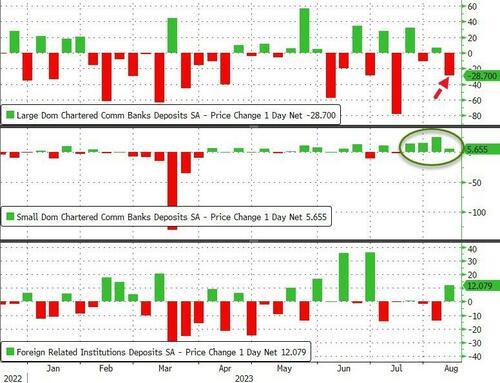
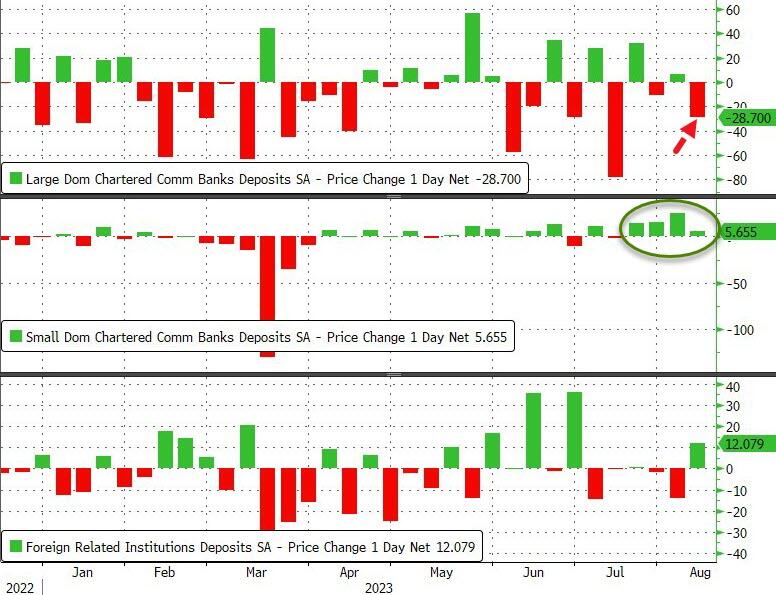
On a seasonally-adjusted basis, Small Banks saw $5.6BN deposit inflows last week while Large Banks suffered $28.7BN outflows (with foreign bank inflows of $12BN making up the difference)…

Source: Bloomberg

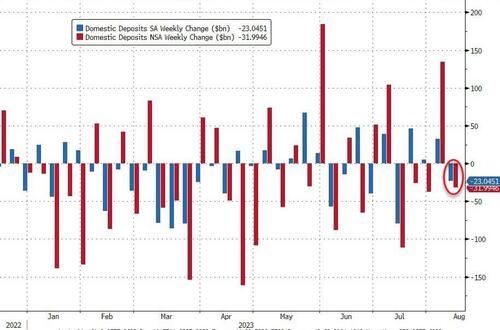
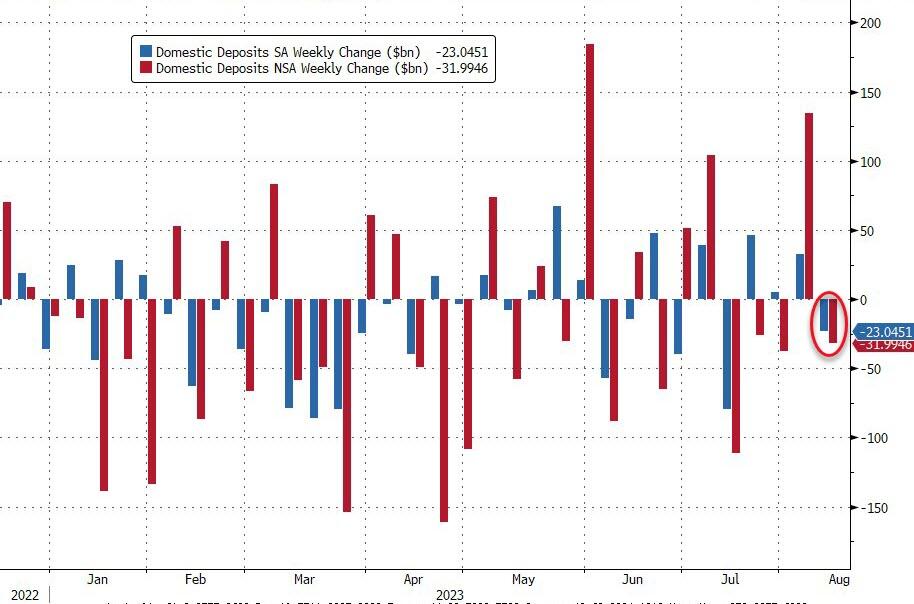
And so, for a nice change, everything is tidy with domestic US banks seeing deposit outflows on an SA and NSA basis…

Source: Bloomberg

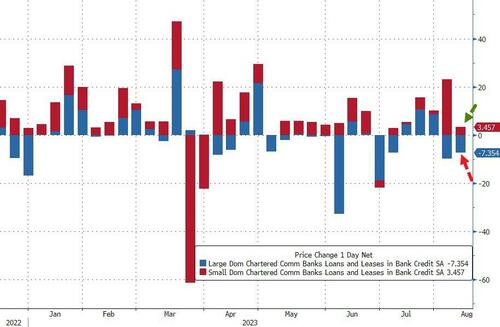
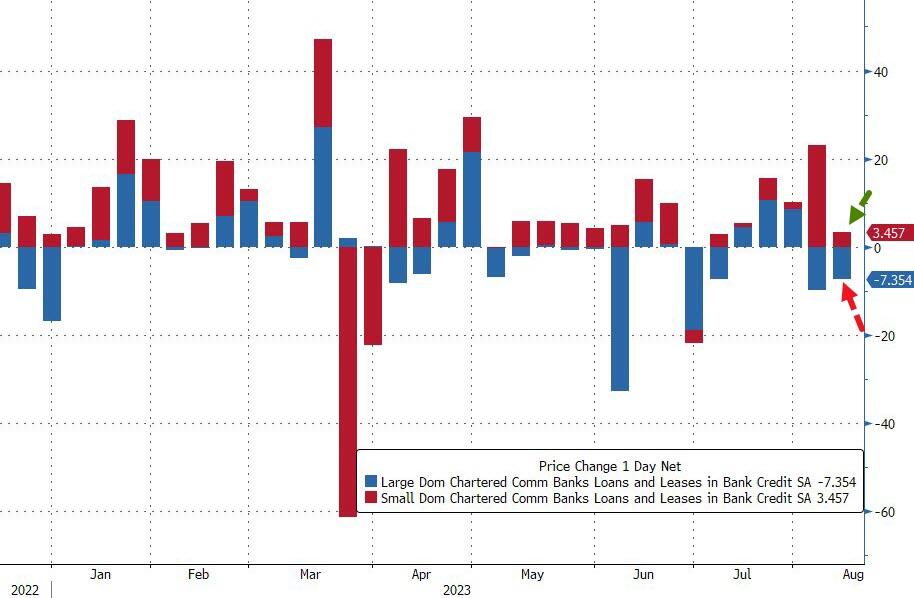
On the other side of the ledger, small banks continued to pump out loans (+$3.56BN, sixth straight week of increases), while large banks saw a $7.4BN contraction in loan volumes

Source: Bloomberg

So, if The Fed’s data is to be believed, Small banks are ‘winning’ – deposit inflows and making loans; while large banks are leaking – deposit outflows and shrinking loans. All while Treasury prices tumble, stressing small bank balance sheets.

Just remember, the sitting US President Joe Biden goes under several psuedonyms like Robert Peters, Robin Ware, and JRB Ware in his email conversations about Ukraine with his son Hunter. But don’t forget another pseudonym: The Reverend Kane from Poltergeist 2!

Hellzapoppin Under Bidenomics! Conforming 30-year Mortgage Rate UP 163.5% (Federal Debt UP 19% Or >$5 Trillion Under Biden While Unfunded Liabilities Are Now At $193 TRILLION)

Hellzapoppin under Bidenomics! And it isn’t a musical, but a tragedy.

Between The Federal Reserve’s outrageous overreaction to Covid (printing like there was no tomorrow), and Biden’s massive spending spree (lots of moldy (green) spending, we have see horrid inflation.

And The Fed trying (sort of) to combat inflation, we see that 30-year CONFORMING mortgage rate for 80% LTV or lower credit borrowers is up 163.5% under Bidenomics.

Under Bidenomics, public debt (owed by the US Treasury) is up 19% or greater than $5 triillion. Now wonder Biden throws are billions like it is water.

I seriously want the Biden Administration (and almost every member of Congress) why we are sending billions of dollars to Ukraine while barely giving Maui fire victims barely anything. The US is already $33 trillion in debt with >$193 trillion in unfunded liabilites. I want to ask Biden and Congress HOW the US is going to afford $193 trillion in unfunded liabilites?

Of course, NO ONE wants to face the reality of the disastrous fiscal poliicies of Washington DC politicians. Not McConnell, not McCarthy, not Schumer and especially not Billions Biden. Remember 10% for The Big Guy where Democrats argue that is meaningless. Or mini-me, Robert Reich (Clinton’s labor secretary) who claimed that the US economy is the best he has ever seen! Yes, Reich, for the top 1%. Of couse, no one will ask fools like Reich how we will pay for $33 trillion in debt and the $193 trillion in unfunded liabilies … and fund a war in Ukreiane in seeming perpetuity.

My good friend Jesse has an excellent write-up on the upcoming KC Federal Reserve annual retreat at Jackson Hole, WYO. This retreat is just the US banking version of The World Economic Forum and Klaus Schwab. Know-it-all unelected elitists controlling our lives.