Official estimates from the Congressional Budget Office (CBO) show that, since January 2021, legislation signed by President Biden has set in motion a record $3.37 trillion in new spending. And for all that spending, we get a pathetic 1.1% QoQ growth rate?
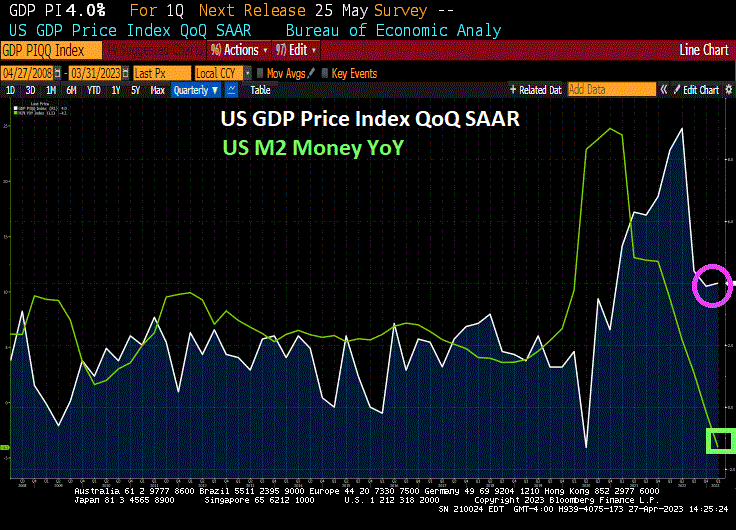
Inflation continues to be 4% QoQ despite M2 Money growth collapsing.
Gross private domestic investment crashed by -12.5% QoQ.
This is Biden’s idea of a strong economy? His lame campaign slogan is “Let’s finish the job!” Please don’t Joe!
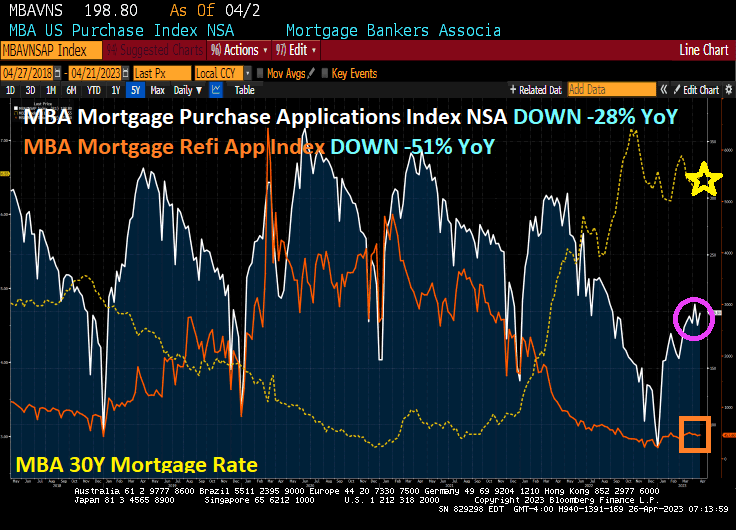
Mortgage applications increased 3.7 percent from one week earlier, according to data from the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey for the week ending April 21, 2023.
The Market Composite Index, a measure of mortgage loan application volume, increased 3.7 percent on a seasonally adjusted basis from one week earlier. On an unadjusted basis, the Index increased 5 percent compared with the previous week. The Refinance Index increased 2 percent from the previous week and was 51 percent lower than the same week one year ago. The seasonally adjusted Purchase Index increased 5 percent from one week earlier. The unadjusted Purchase Index increased 6 percent compared with the previous week and was 28 percent lower than the same week one year ago.
Here is a chart of US office vacancies nationally (yellow), New York (white), San Franciso (green) and Los Angeles (orange). Note the rapid decline in office vacancies just prior to the financial crisis (often mislabeled as the subprime mortgage crisis). Then look at office vacancies after The Fed’s massive monetary experiment of setting rates to near zero and buying a ton of Treasuries, Agency MBS. etc. While San Francisco returned to pre-financial crisis levels of office vacancy, in general the office market never fully recovered.
And then “the slammer” struck: the COVID economic shutdowns. After 2020 shutdowns, office vacancy rates rose dramatically. Two complicating factors: 1) the US moved to working at home rather than commuting to an office and largely remains that way. 2) crime is going bonkers in American cities, particularly New York, Los Angeles and San Francisco (don’t worry, I haven’t forgotten about other gang nests like Chicago and Detroit). I saw that California’s woke governor Gavin “Nancy Pelosi’s nephew” Newsom said the word “gang” then apologized and replaced it with “organized groups.” No wonder Newsom can’t fix anything, but he is running for President of the US! (insert Edvard Munch’s “The Scream” painting here,)
The Fed responded to the financial crisis by lower rates to 25 basis points and printing a boat load of money. Unfortunately, office vacancies rose to a peak in October 2010 then began falling again. Only to start rising again after Trump took office in 2017. Alas, Covid struck in 2020, The Fed and Federal government panicked. States and local governments (not to mention teacher’s unions) shut down economies and schools. Office vacancies are now higher than at peak of the Covid shutdowns!!!
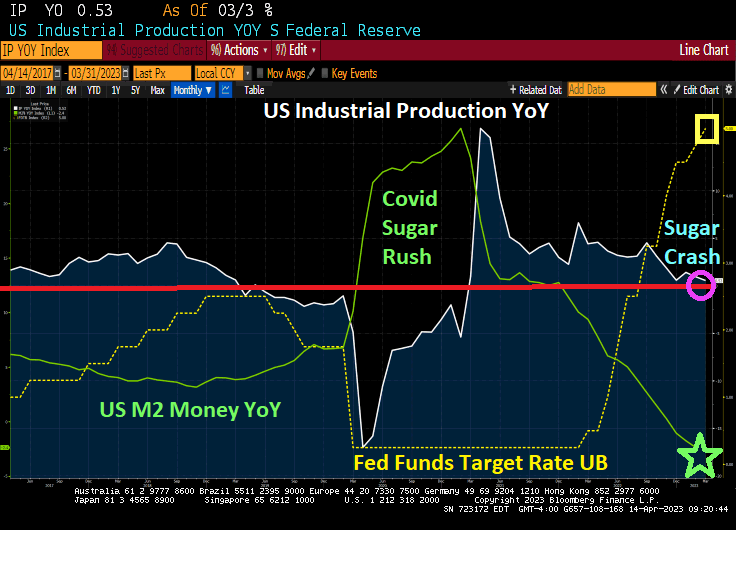
The US economy is barely chooglin along at a dismal 0.53% YoY (but 0.4% MoM in March). As the Covid “sugar rush” that caused a surge in Industrial Production in April 2021 of 16.56% has led to a “sugar crash” as M2 Money growth crashed and The Fed hiked rates to combat inflation. Known as a “sugar crash.”
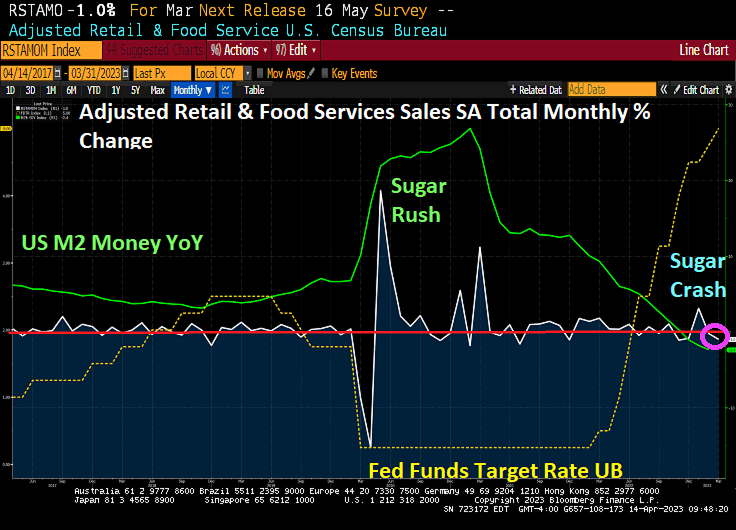
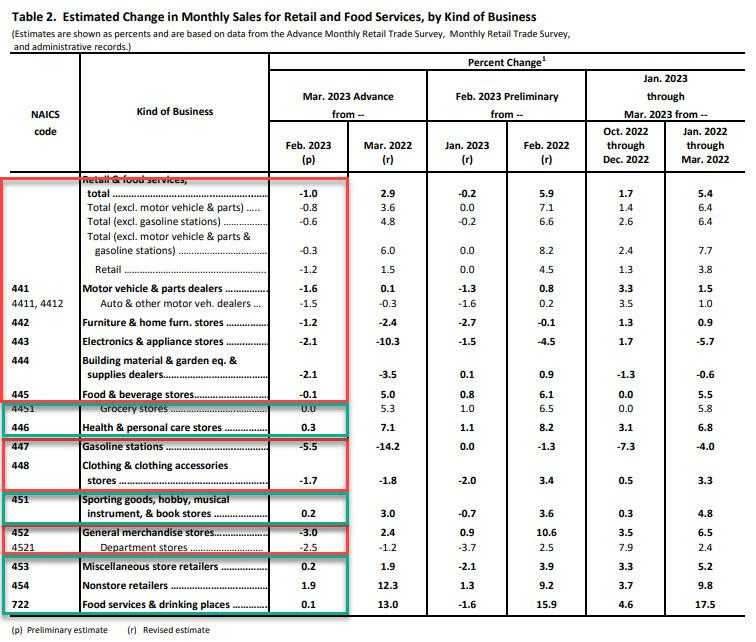
Also in today’s economic news is more Sugar Crash news. Advance retail sales dropped -1% in March. That is -155% lower than a year ago when it was +1.8%.
Here is the breakdown.
The Federal Reserve put a spell on us when Bernanke/Yellen kept rates too low for too long (TLFTL) and The Fed is now playing catch up. It is now creating havoc.
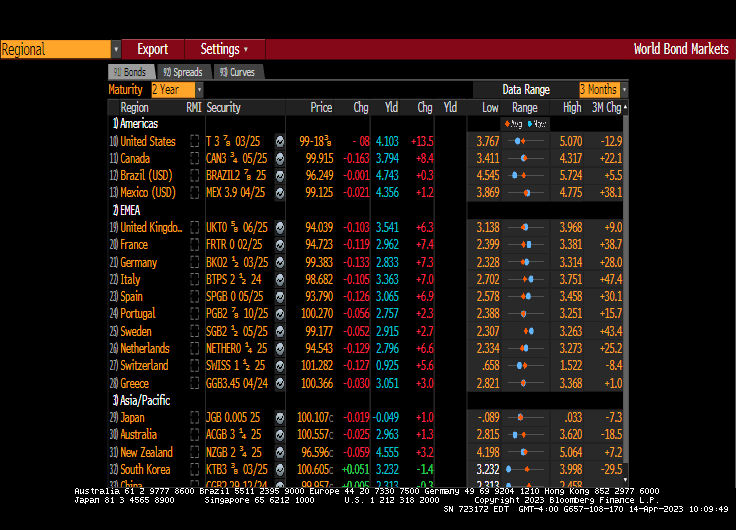
And on the Philly Fed’s Christopher “Fats” Waller saying that he favored more monetary policy tightening to reduce persistently high inflation, although he said he was prepared to adjust his stance if needed if credit tightens more than expected, we see that US Treasury 2-year yield jumping 13.5 basis points to 4.103%.
US Producer Price Index (PPI) final demand YoY fell to 2.7% in March as The Fed withdraws its massive monetary stimulus.
Final demand MoM fell -0.5% in March. But the interest number is CORE PPI ex food and energy actually down but at 3.6%. So, CORE PPI final demand growth is higher than the aggregate.
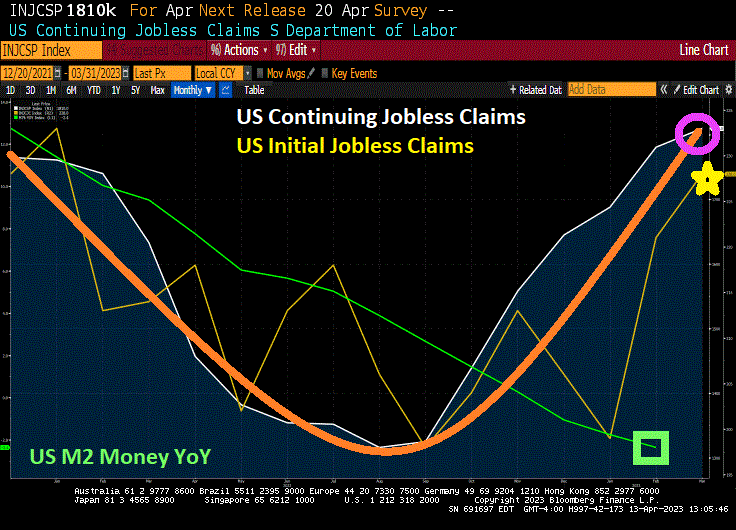
Do I detect a trend in US continuing jobless claims?
At least Biden is in Belfast Ireland making his usual gaffes, telling outrageous lies and looking totally lost. As usual. He can do less damage to the US by being in Ireland.
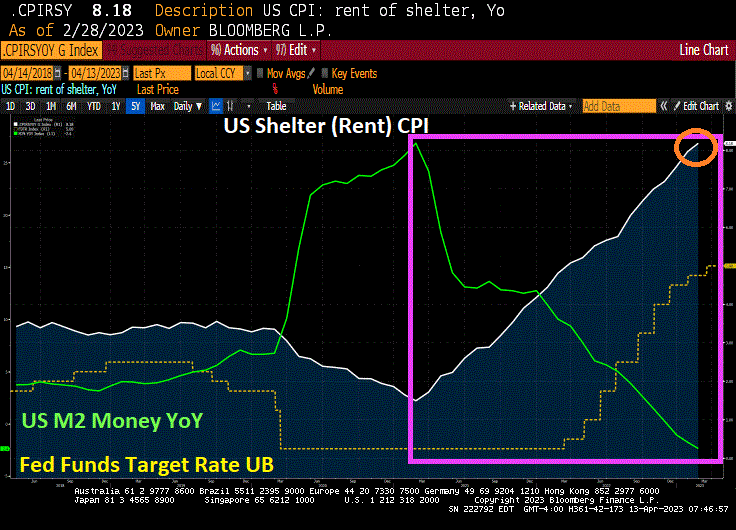
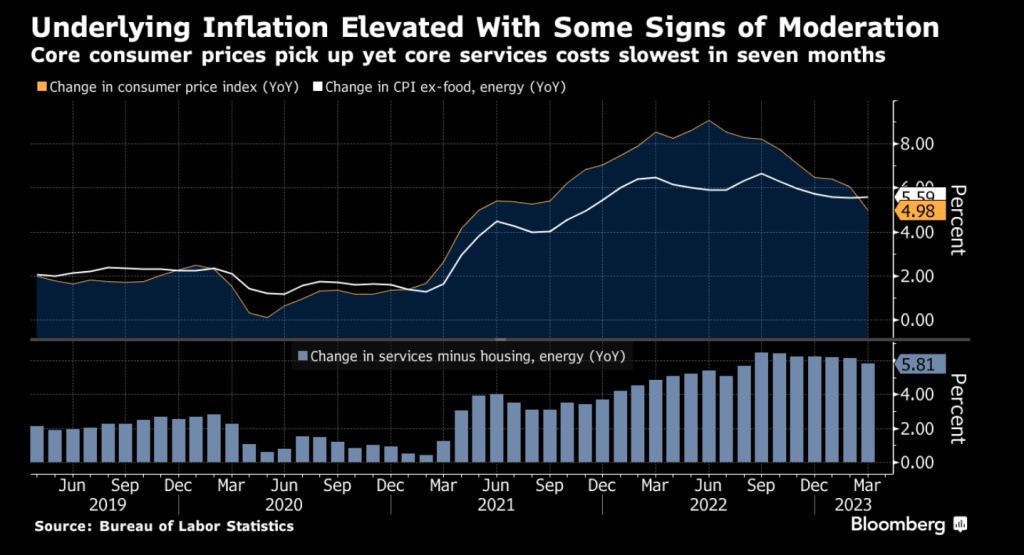
Two of the biggest items for consumer are housing and food. Shelter inflation (CPI) is still growing at 8.2% YoY and food is still growing at 8.5% YoY.
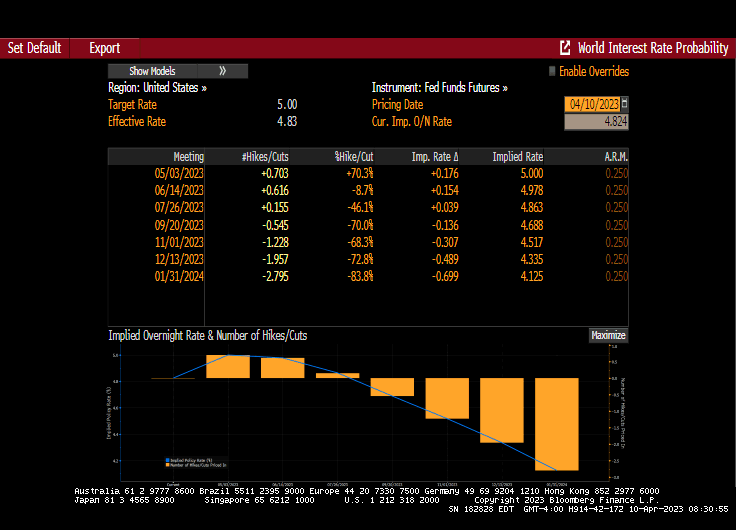
Federal Reserve officials appear on track to extend their run of interest-rate hikes when they meet next month, shrugging off their advisers’ warning of recession with a bet that they need to do a little more to curb inflation.
Minutes of last month’s policy meeting showed officials dialed back expectations of how high they’ll need to lift rates after a series of bank collapses roiled markets last month. Still, officials raised their benchmark lending rate a quarter point to a range of 4.75% to 5%, as they sought to balance the risk of a credit crunch with incoming data showing price pressures remained too high.
They did so even after hearing from Fed staff advisers that they were forecasting a “mild recession” later this year.
Officials agreed “some additional policy firming may be appropriate,” according to minutes of the Federal Open Market Committee gathering, a posture several Fed speakers have reiterated in recent days.
Policymakers “commented that recent developments in the banking sector were likely to result in tighter credit conditions for households and businesses and to weigh on economic activity, hiring and inflation,” the minutes said, though they agreed the extent of the effects was uncertain. “Against this background, participants continued to be highly attentive to inflation risks.”
I read over the weekend that the Biden Administration was planning to unleash its army of social influencers on us to hype Biden’s economic accomplishments before the Presidential election. I am not one of his preferred social influencers. In fact, the US economy is slippin’ into darkness under Biden.
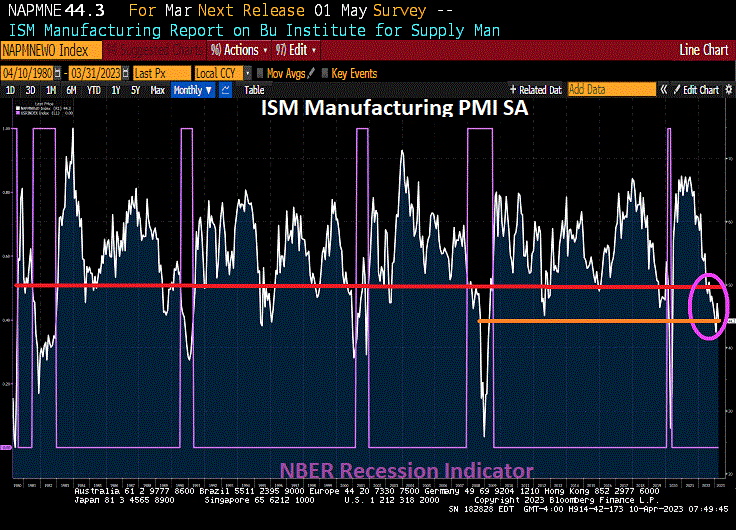
An example is ISM Manufacturing PMI which has declined to a level typically seen in prior recessions.
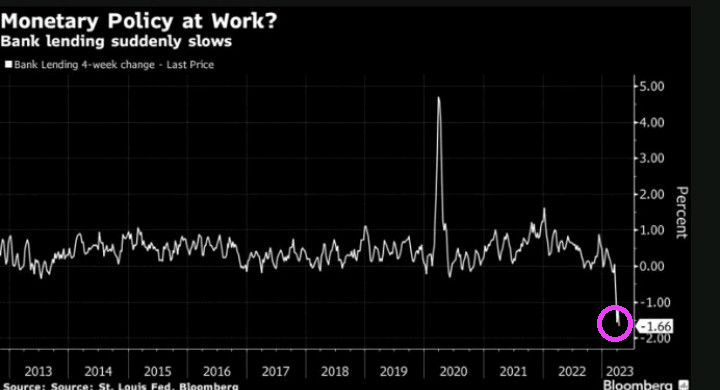
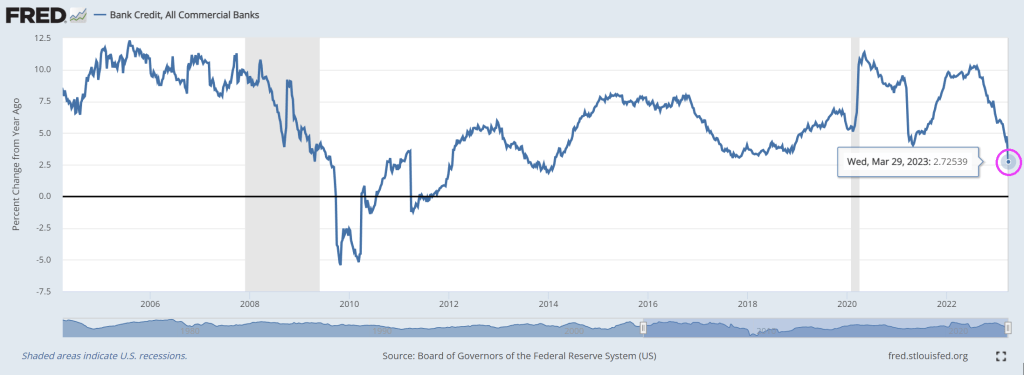
And then we have US bank credit growth which just crashed to the slowest growth rate since 2014.
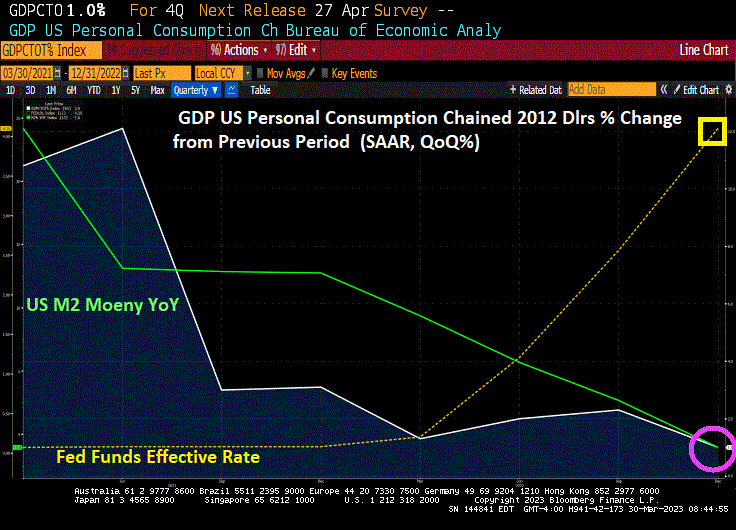
The Covid outbreak in early 2020 (from which I came close to dying) resulted in legendary Fed stimulus and Federal government spending. But as The Fed attempts to cool inflation by slowing M2 Money printing and raising The Fed’s target rate, we are seeing the lowest personal consumption expenditures print under Biden’s reign of error, a measly 1%.
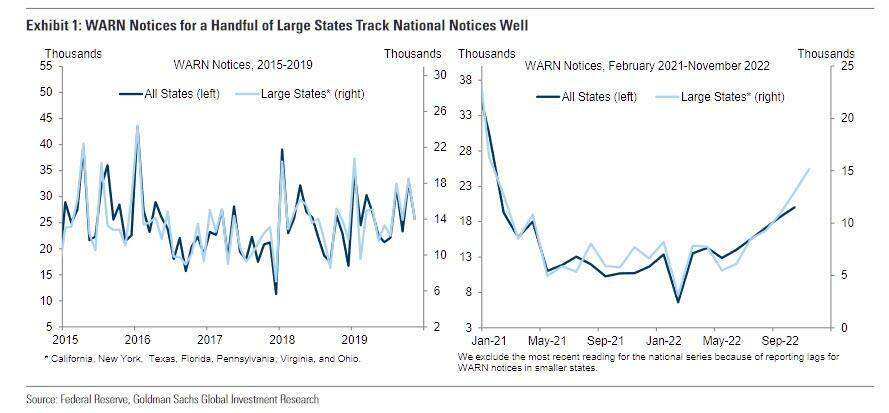
On top of the dismal revision to the Q4, we are seeing WARN notices increasing, particularly for large states. Worker Adjustment and Retraining (WARN) Notices are picking up which points to unemployment claims soon rising and a deterioration in the jobs market, posing a risk to stocks.
Biden’s reign of error continues with horrible policies. With the help of Congress.
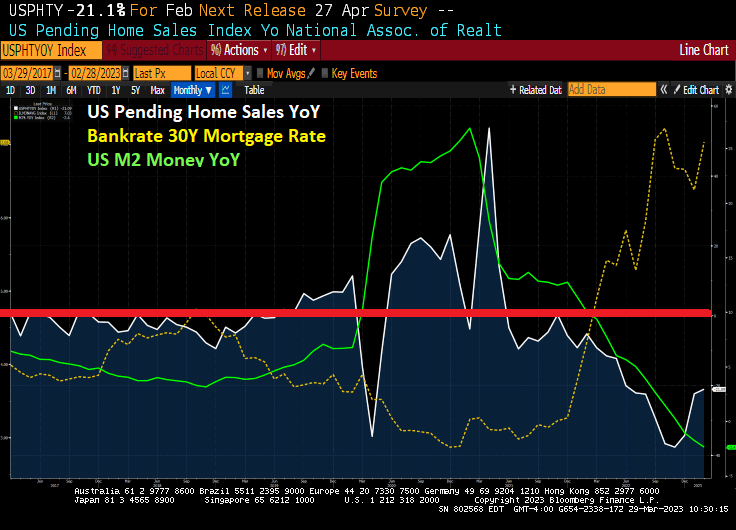
Pending home sales grew in February for the third consecutive month, according to the National Association of REALTORS®. Three U.S. regions posted monthly gains, while the West declined. All four regions saw year-over-year decreases in transactions.
The Pending Home Sales Index (PHSI)* — a forward-looking indicator of home sales based on contract signings — improved 0.8% to 83.2 in February. Year-over-year, pending transactions dropped by 21.1%. An index of 100 is equal to the level of contract activity in 2001.
More notably, the YoY growth rate has been NEGATIVE for 20 of the last 21 months. And 15 straight months.
Biden’s energy policies + insane Federal spending = inflation = Fed slowing M2 Money growth. Hence, pending home sales YoY is down -21.1%.










You must be logged in to post a comment.