Yes, one of the cornerstones of Bidenomics is the massive expansion of (impractical) electric vehicles (or EVs). You know, those mondo expensive cars that run out of power after a couple of hundred miles requiring a lengthy recharge (kind of makes long distance trips the domain of Internal Combustion Engine (ICE) cars.
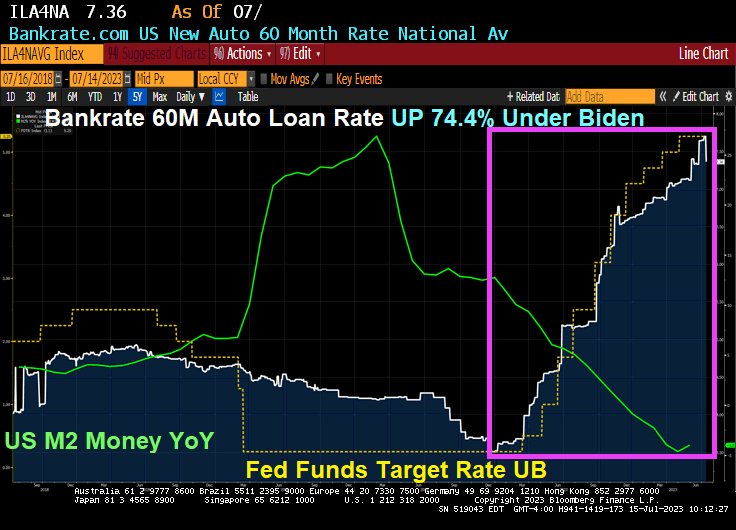
But as Biden/Congress spent trillions on green energy (massive subsidies for anything green), we noticed that 1) inflation hit 40 year highs and 2) The Fed intervened to raise rates. So, now we see that 60-month auto loan rates are now around 7.36%, up 74.4% under “Middle Class Joe.”
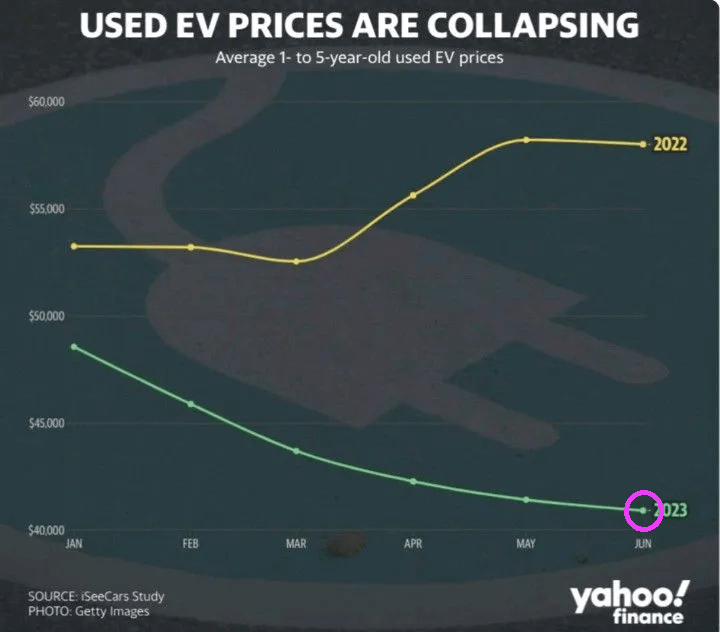
And we see used EV prices collapsing like a week-old soufflé.
Speaking of green energy fraud, here is the leader of the green energy fraud movement, John F’ing Kerry. Aka, Heinz Planes Grifter.
What screams may come! Actually, the aftermath of excessive monetary policies under Bernanke, Yellen and Powell are coming home to bit the big banks.
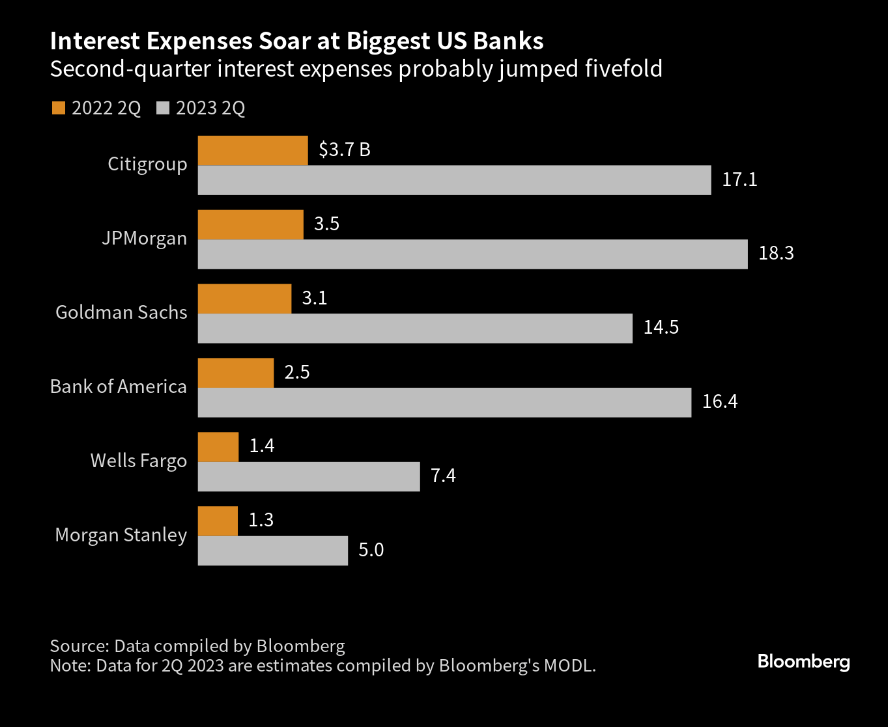
Interest expenses at big US banks are rising much more quickly than interest income. Across the six largest US banks, interest expenses are set to climb to roughly $78.7 billion from $15.5 billion in the same period last year.
There is still $8.3 Trillion in monetary stimulus sloshing around the monetary system.
As M2 Money growth has stalled, we are seeing inflation cool a bit. Core inflation YoY is now down to 4.8% (still >2x Fed target).
The good news? REAL average hourly earnings YoY is finally positive for the second time under Bidenomics. It is now 1.2% YoY. Too bad rent CPI, typically the largest expense for Americans, is still up 8% YoY.
The Taylor Rule, given 4.8% core inflation, gives us a Fed Funds Target rate of 10.42%. So, yes, it looks like Powell and the Gang have more work to do.
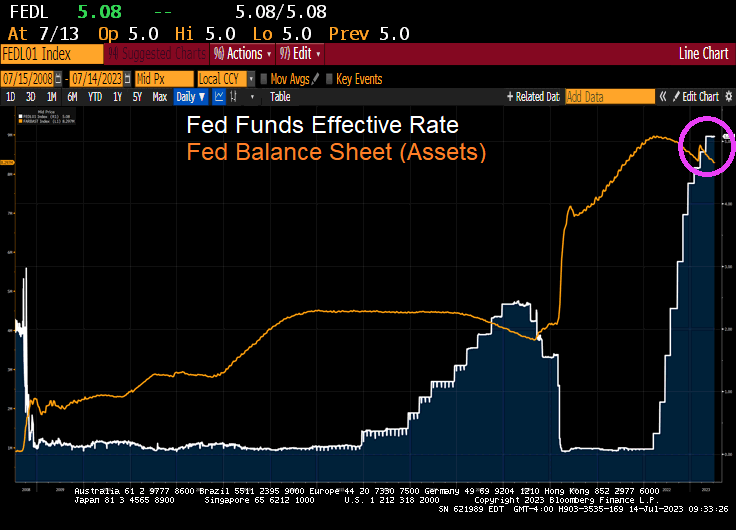
Bidenomics relied of massive Federal spending thanks to Covid and massive monetary expansion. This led to the highest inflation in 40 years (Bidenflation). But now The Fed is slowing M2 Money growth into negative territory and hiking their target rate.
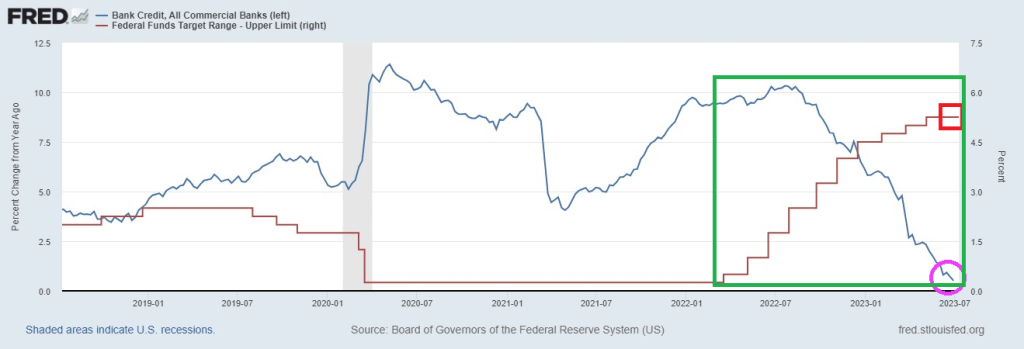
The result? Bank credit growth has crashed to 0.5% YoY. In other words, banks are no longer expanding credit for the first time since the aftermanth of The Great Recession and Financial Crisis of 2008/2009. Of course, Washington DC bailed out their bestest buddies, the banks, while middle America suffered.
As America loses steam under Biden and The Fed, 41+ countries have signed on to the BRICs gold-backed reserve currency. Unlike the USA with its fiat currency (backed by Babbling Biden and Janet “The Midget Marxist” Yellen), this reserve currency will be backed by gold.
Bidenomics, the massive Federal spending spree that helped drive inflation to 40 year highs, is the most top-down Soviet-style command economy model imaginable.
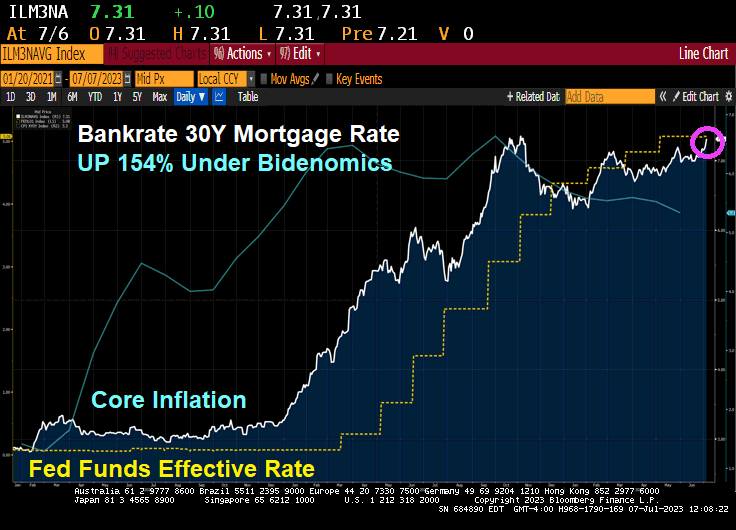
As The Fed battles Bidenflation, the 30-year mortgage rate has now risen to 7.31%, a far cry from 2.88% when Biden was installed as President. That is a 154% increase in the 30-year mortgage rate under Bidenomics.
The good news (if true)? ADP announced that 497k jobs were added in June.
The bad news? A 497k print on jobs (many seasonal, it is summer!) almost guarantees that The FOMC (Fed Open Market Committe) will raises rates again at at the July meeting.
The 2-year Treasury yield is up over 10 basis points.
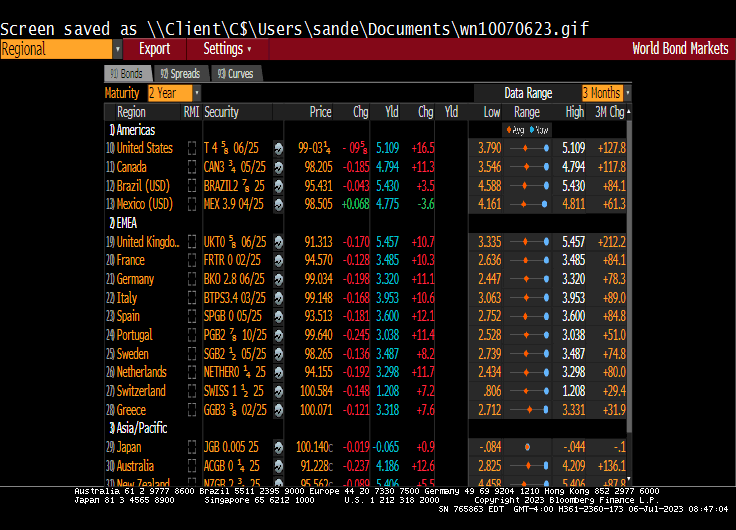
The 2-year Treasury yield is up 16.5 basis points.
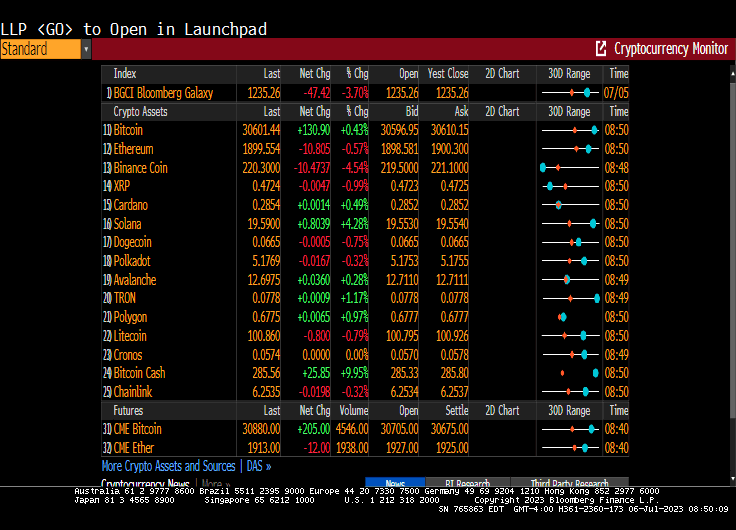
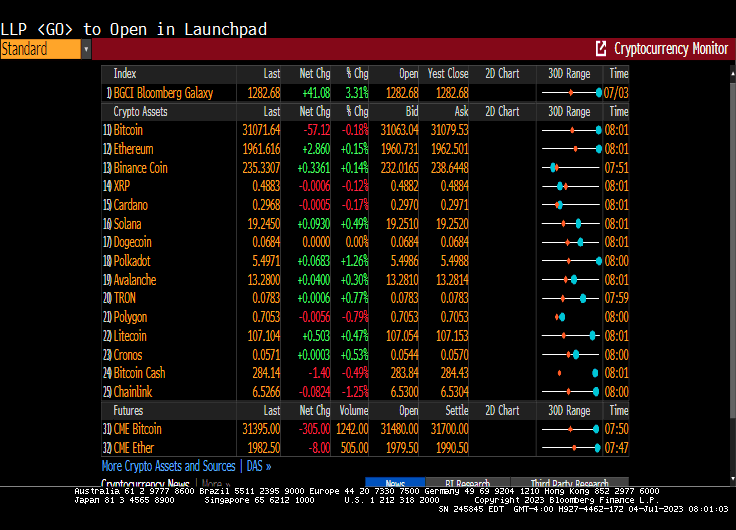
Bticoin Cash is up 10% today.
I should have bought nickel!
Why is Biden sending Treasury Secretary Janet “The Marxist Midget” Yellen to China? A Treasury Secretary and former Federal Reserve Chair? Likely trying to convince China that our $32 TRILLLION AND GROWING national debt is not a problem, since China is the third largest holder of US Treasury debt (after The Fed and Japan). Note that China has decreased its holdings of US Treasuries by -25.6% since January 2018.
Hopefully, Yellen isn’t acting as a bag man for The Biden Crime Family. 10% for The Big Guy?? How much does Yellen get??
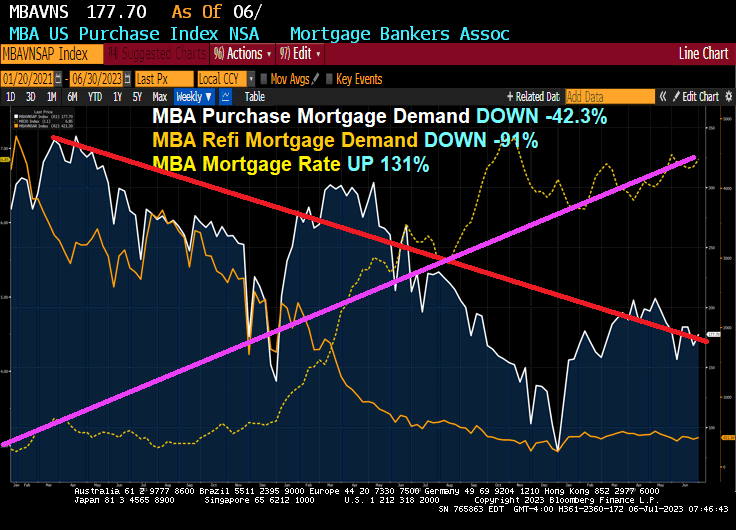
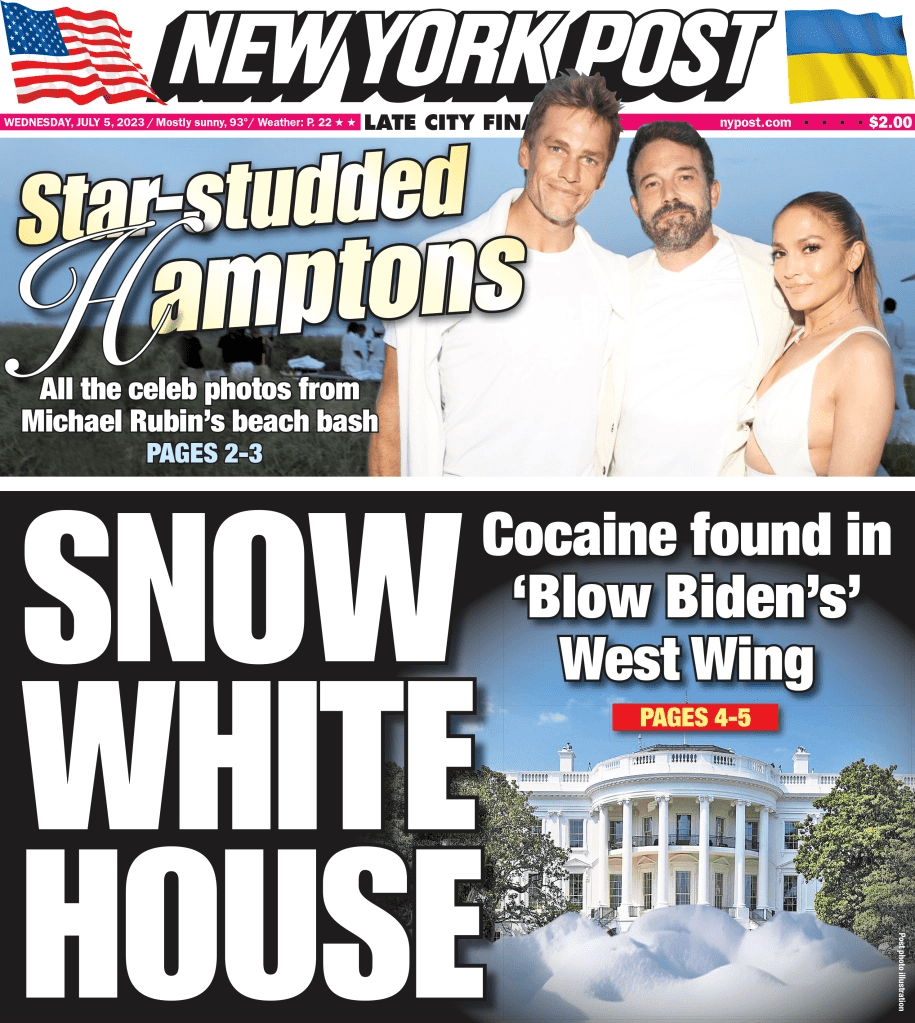
Joe Biden, or “Blow Biden” after the cocaine was discovered in the White House the other day, owns the abysmal mortgage and housing market thanks to The Fed fighting inflation caused by Bidenomics (massive Federal spending and massive Fed stimulus).
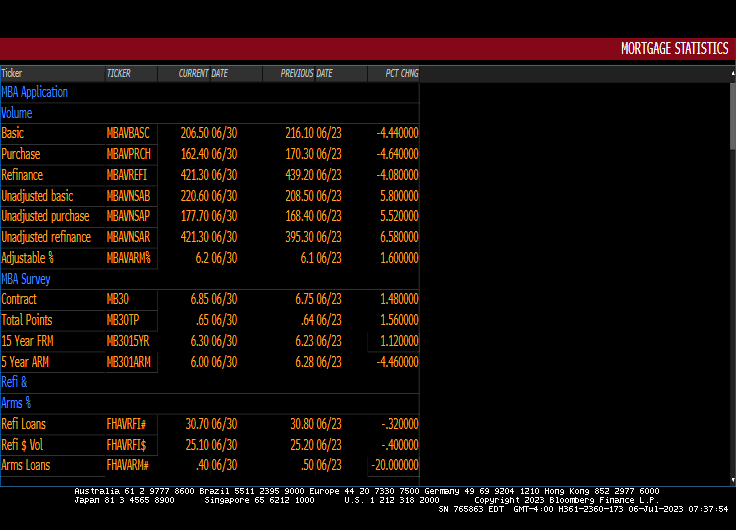
Mortgage applications decreased 4.4 percent from one week earlier, according to data from the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey for the week ending June 30, 2023. Last week’s results included an adjustment for the Juneteenth holiday.
The Market Composite Index, a measure of mortgage loan application volume, decreased 4.4 percent on a seasonally adjusted basis from one week earlier. On an unadjusted basis, the Index increased 6 percent compared with the previous week. The Refinance Index decreased 4 percent from the previous week and was 30 percent lower than the same week one year ago. The seasonally adjusted Purchase Index decreased 5 percent from one week earlier. The unadjusted Purchase Index increased 6 percent compared with the previous week and was 22 percent lower than the same week one year ago.
Here is the rest on the story:
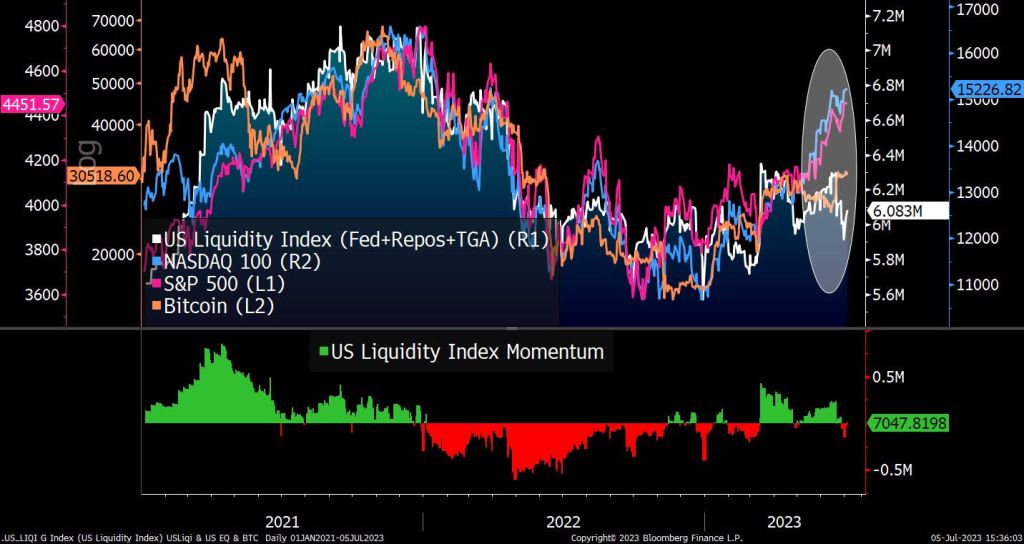
As liquidity dries up under Bidenomics. Or Yellenomics. Take your pick!
Seriously, can The Biden Administration get any more embarrassing? Or dangerous to American civil liberties?
The Federal Home Loan Bank system (aka, FLUBs), a relic of FDR and The Great Depression, subsidizes banks, not individuals. Much like its twin sibling, The Federal Reserve system, it is a Socialist institution that rely of manipulation rather than free markets.
The first sign of deep trouble in US banking this year came from a sunbaked office complex in a San Diego suburb. There, a small firm called Silvergate Capital Corp. assured investors it was weathering a run on deposits. Its lifeline: about $4.3 billion from a Federal Home Loan Bank.
Heads turned across the financial industry.
Silvergate didn’t have a network of branches serving consumers, and it barely offered mortgages. It specialized in moving dollars for cryptocurrency ventures.
Soon it became apparent that a roster of troubled regional banks was leaning on FHLBs — a relic of the Great Depression originally aimed at ensuring financial firms have cash to lend to homebuyers. Yet the banks had little to do with everyday mortgage lending.
Silicon Valley Bank, catering to venture capitalists and tech startups, said it held $15 billion from an FHLB at the end of 2022. Signature Bank, with clients including crypto platforms, had $11 billion. And by April, First Republic Bank, offering mortgages to millionaires on unusually sweet terms, ended up with more than $28 billion. All four banks collapsed.
For many, that was a crystallizing moment for the 90-year-old Federal Home Loan Bank system, which has ballooned to more than $1.5 trillion while playing a growing role as a backstop for banks taking all kinds of risks — and a diminishing role in funding new mortgages. That’s raising questions about the purpose of FHLBs and why the private institutions enjoy so much government support.
As Milton Friedman once said, “Nothing is so permanent as a temporary government program.”
Of course, rate increases are crushing regional banks as well as the middle class. But as M2 Money growth crashes, home price growth is slowing into negative territory.
Its the 4th of July, American Independence Day from England, but under Biden and The Federal Reserve, Americans are DEPENDENT on debt and Federal spending. In other words, Americans are addicted to gov.
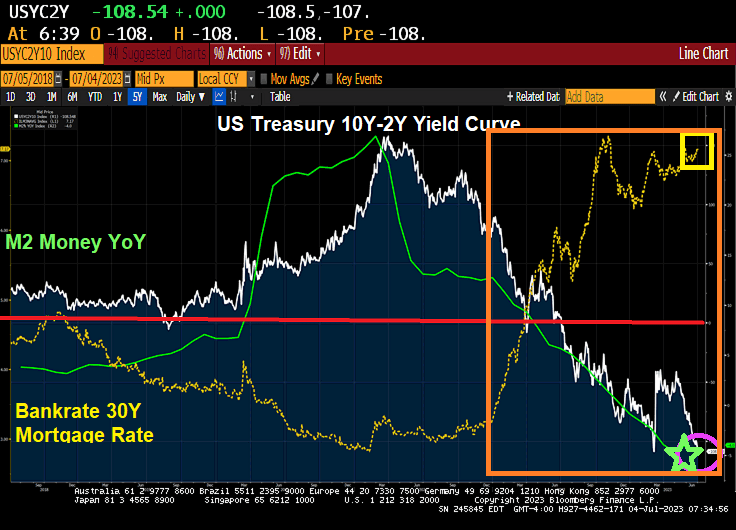
First, Bankrate’s 30-year mortgage rate index is up 150% under Biden. You can see the rapid rise in mortgage rates started with Biden (orange box). Meanwhile, the US Treasury yield curve (10Y-2Y) is the most inverted (negative slope) since 1981. Way to go, Joe!!
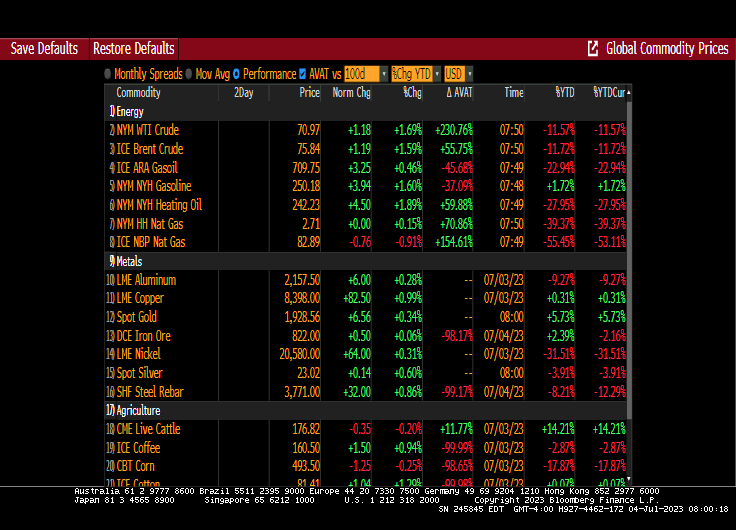
On the metals side, gold and silver are up slightly. (Go silver go!!)
On the crypto side, Polkadot is up 1.26% while Bitcoin is down -0.18%.
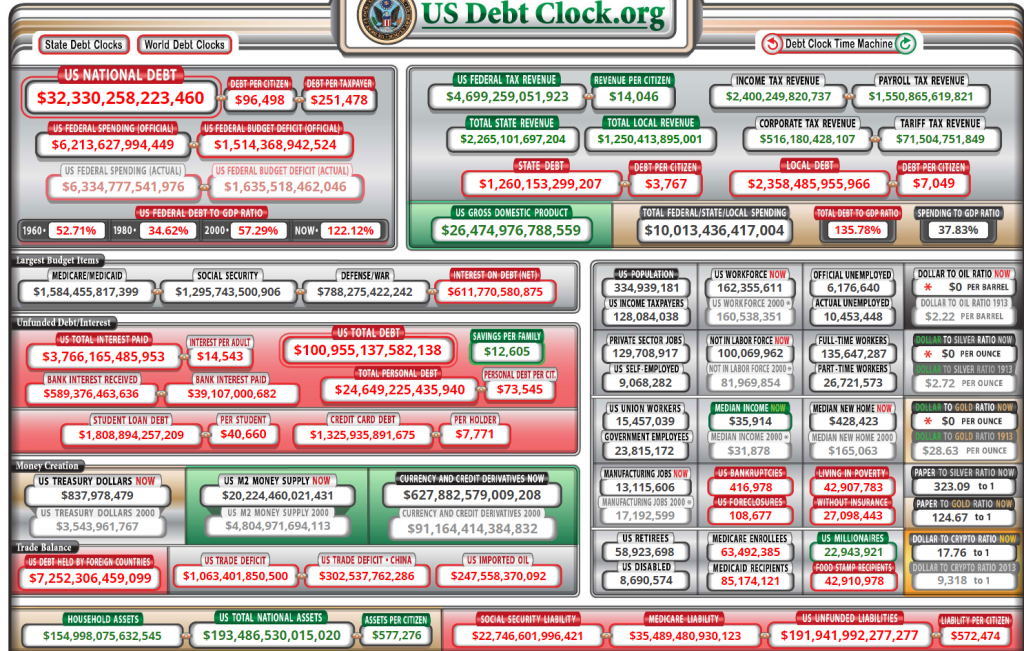
Memo To Fed: keep on printing! Why? US debt is currently $32.33 TRILLION with $192 TRILLION in unfunded Federal liabilties. That is 5 times the current level of debt!!












You must be logged in to post a comment.